
Australia Data Center Storage Market Size, Share & Forecast to 2035
Market at a glance
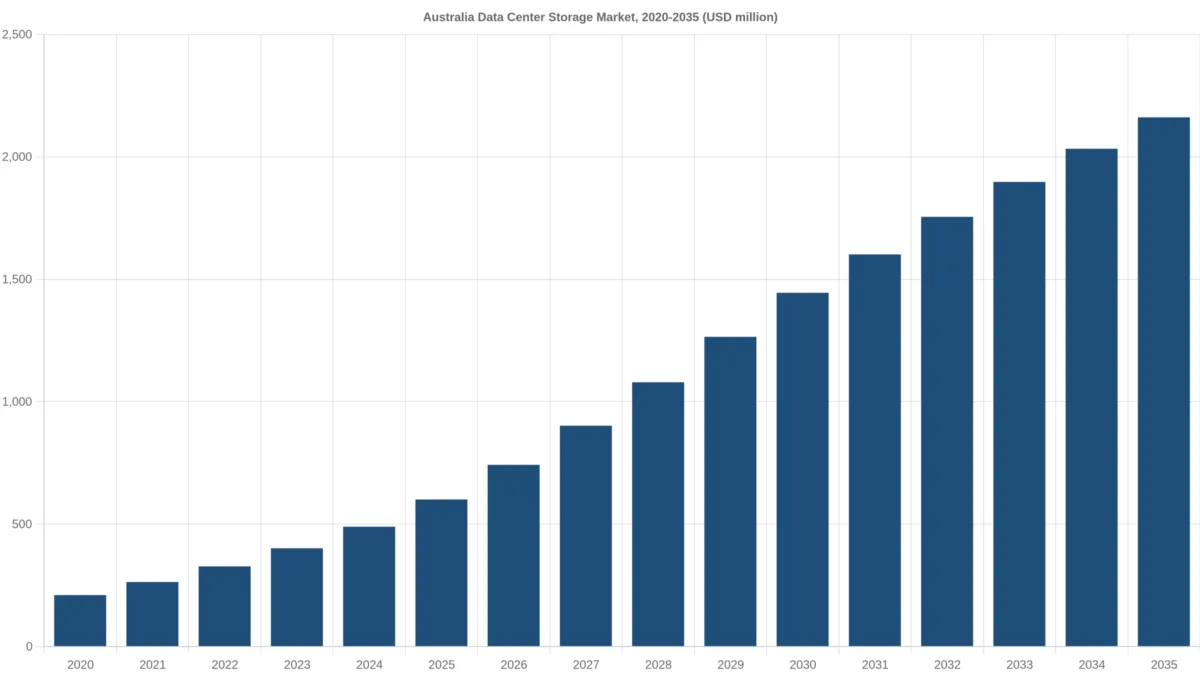
The Australia Data Center Storage market was worth USD 600.8 million in 2025 and is forecast to reach USD 2,160.0 million by 2035, growing at a 13.66% CAGR.
 By Amit Jain, Senior Consultant, ICT & Emerging Technologies
 Reviewed by Deepti Agrawal
Last updated 30 Oct 2026
Base year 2025 PDF + Excel
Key findings
NEXTDC's contracted capacity tripled to 740.1 MW in FY2026
Flash takes the primary tier
Grid connections delay the halls that would hold the arrays
AI cluster storage in Western Sydney and Melbourne West
What is inside the report
- 01Introduction
- 02Executive Summary
- 03Market Scope and Estimate Comparison
- 04Market Drivers
- 05Market Trends
- 06Market Challenges
- 07Market Opportunities
- 08Pricing Analysis
- 09Standards and Regulation
- 10Market Segmentation
- 17chapters
- 2020-2024Historical period
- 2026-2035Forecast period
- —Companies profiled
Segmentation
Recent developments
NEXTDC reported pro forma contracted utilisation of 740.1 MW, three times the prior year (Source: NEXTDC FY2026 results).
AEMO counted 225 data centers with 67 GW of capacity in development (Source: AEMO 2026 Electricity Statement of Opportunities).
the Department of Industry, Science and Resources published the National Expectations for Data Centres and AI Infrastructure (Source: Department of Industry, Science and Resources).
NetApp reported a record USD 1.0 billion all-flash array quarter (Source: NetApp).
NEXTDC and OpenAI signed a non-binding memorandum for the S7 Eastern Creek campus (Source: NEXTDC ASX announcement).
Amazon announced AU$20 billion of Australian data center investment for 2025-2029 (Source: Amazon).
Full analysis
The Australia Data Center Storage Market is valued at USD 742.34 million in 2026 and is projected to reach USD 2.16 billion by 2035, up from USD 600.77 million in 2025, a CAGR of 13.66% from 2025 to 2035 (DC Market Insights estimate). Two things move the money in Australian storage: the installed data center base, which DC Market Insights puts at about 1,571 MW of IT capacity at the end of 2025 against roughly 566 MW in 2020, and the shift of new halls to GPU clusters, which buy high-throughput flash at about USD 1.10 million per megawatt (MW) of AI capacity. The 2025 build receipt is 1,427 MW of average installed capacity × USD 0.34 million of storage spend per MW-year = USD 485.27 million, plus 105 MW of new AI capacity × USD 1.10 million = USD 115.50 million. Sovereignty rules add a third lever: federal agencies must keep classified and sensitive data in facilities certified under the Digital Transformation Agency (DTA) Hosting Certification Framework, which keeps government arrays onshore in Canberra and Sydney rather than in offshore cloud regions. Object storage grows fastest at 17.92% a year, and Queensland is the fastest region at 19.13% as Brisbane campuses add AI capacity.
How Much Do Australian Data Centers Spend on Storage in 2026?
Australian data centers will spend USD 742.34 million on storage systems, storage software and storage services in 2026, 23.56% more than the USD 600.8 million of 2025, DC Market Insights estimates.
- Market size 2025: USD 600.77 million
- Market size 2026: USD 742.34 million
- Market size 2030: USD 1.44 billion
- Market size 2035: USD 2.16 billion
- CAGR 2025-2035: 13.66% (low case 10.50%, high case 16.50%)
- Largest storage type: All-Flash Arrays, 52% of 2025 value
- Fastest architecture: Object Storage, 17.92% CAGR
- Leading region: New South Wales, 62% of 2025 value; fastest region: Queensland, 19.13% CAGR
- Largest location: Western Sydney (Eastern Creek and Kemps Creek), USD 180.24 million in 2025
- Market leaders: Dell Technologies, NetApp and Hewlett Packard Enterprise (HPE), about 47% of external array spend together (DC Market Insights estimate)
Key Takeaways: What Should Storage Buyers in Australia Know?
- All-flash arrays take 52% of 2025 spend and reach 68% by 2035 because AI training halls cannot feed graphics processing units (GPUs) from disk.
- Object storage grows 17.92% a year because model checkpoints, video and backup copies move to S3-compatible capacity tiers.
- Victoria rises from 27% to 32.8% of value by 2035 because Melbourne West campuses add capacity faster than inner Sydney.
- On-premises enterprise storage grows only 8.0% a year because enterprises move arrays into colocation halls and public cloud.
Executive Summary: Australia Data Center Storage Market Size, 2020-2035
The Australia Data Center Storage Market size was valued at USD 210.40 million in 2020, reached USD 600.77 million in 2025, and is anticipated to reach USD 2.16 billion by 2035, at a CAGR of 13.66% during the forecast period. Growth from 2020 to 2025 ran at 23.35% a year because the installed base almost tripled while AI halls started buying flash in bulk.
| Attribute | Detail |
|---|---|
| Historical period | 2020-2024 |
| Base year | 2025 |
| Forecast period | 2026-2035 |
| Market size 2025 | USD 600.77 million |
| Market size 2026 | USD 742.34 million |
| CAGR 2025-2035 | 13.66% |
| Market size 2035 | USD 2.16 billion |
DC Market Insights values installed-base storage refresh and expansion at USD 485.27 million in 2025 and AI cluster storage at USD 115.50 million; by 2035 the two lines reach USD 1.72 billion and USD 438.96 million. The per-megawatt storage rate falls from USD 0.40 million in 2020 to USD 0.25 million in 2035 because each new rack carries more compute power per terabyte stored.
What Does Data Center Storage Cover in Australia?
Australia Data Center Storage covers the storage arrays, file and object systems, tape libraries, storage software and storage support bought for data center halls located in Australia, worth USD 600.77 million in 2025.
Included: all-flash and hybrid arrays, HDD-based systems, tape and archive libraries, Storage Area Network (SAN), Network-Attached Storage (NAS) and scale-out file systems, object storage, direct-attached and hyperconverged storage nodes, storage software (data protection, replication, tiering) and vendor or partner support. Storage that hyperscale and cloud providers build for their own Australian regions is counted at its hardware and software value.
Excluded: servers, networking, power and cooling (covered in the Australia Data Center Infrastructure Market), cloud storage subscription revenue, endpoint and personal storage, and electricity. The Australia Data Center Market is the parent report: it counts storage as one line of total spend, while this edition breaks that line out by storage type, architecture, component, end user and location.
How the segments fit together: each of the four segment dimensions, the five regions and the 12 locations sums to the market total in every year from 2020 to 2035.
Why Do Australia Data Center Storage Market Estimates Differ?
DC Market Insights puts the Australia Data Center Storage Market at USD 742.34 million in 2026; the previous DC Market Insights edition put 2025 at USD 3.73 billion because it counted servers attached to storage and cloud storage revenue. Broader definitions also add consumer and enterprise endpoint storage, storage-as-a-service subscriptions and the data center building space used by storage halls. This edition keeps only storage equipment, software and support bought for data center halls.
| Element | In this report | Why |
|---|---|---|
| Storage arrays and file and object systems | Yes (USD 600.77 million total market 2025) | Core purchase |
| Storage software and support | Yes (USD 204.26 million in 2025) | Bought with the arrays |
| Cloud storage subscriptions | No | Service revenue, not equipment |
| Servers, network, power | No | Covered by sibling reports |
| Endpoint and personal storage | No | Not data center equipment |
Small and mid-sized enterprises are in scope when they place arrays in colocation halls; their spend sits in the Colocation-Hosted Enterprises segment.
Market Drivers: Why Is Australian Data Center Storage Spending Rising?
Australian data center storage spending rises 13.66% a year to 2035 because capacity under contract is tripling, sovereign-data rules keep government data onshore and AI halls buy flash in bulk.
NEXTDC’s contracted capacity tripled to 740.1 MW in FY2026
NEXTDC reported in its FY2026 results of 27 August 2026 that pro forma contracted utilisation tripled to 740.1 MW, with 175.0 MW billing and 287.9 MW built (NEXTDC FY2026 results). Every billed megawatt of tenant IT brings storage purchases: at USD 0.34 million per MW-year, the 175.0 MW billing alone supports about USD 59.5 million of tenant storage spend a year (DC Market Insights estimate). The 565 MW gap between contracted and billing capacity is storage demand that arrives as tenants fit out between 2027 and 2030.
The Hosting Certification Framework keeps government arrays onshore
The Hosting Certification Framework published by the Digital Transformation Agency in March 2021 requires Australian Government data classified up to PROTECTED to sit in facilities with Certified Assured or Certified Strategic status. DC Market Insights estimates that Government and Defence buyers account for 12% of data center storage spend in 2025 and grow 11.61% a year to 2035 as agencies replace arrays in certified Canberra and Sydney halls rather than move them offshore.
Amazon’s AU$20 billion plan brings AI-scale storage halls to Sydney and Melbourne
Amazon announced on 14 June 2025 that it plans to invest AU$20 billion from 2025 to 2029 in Australian data center infrastructure (Amazon announcement). DC Market Insights counts AI cluster storage at USD 115.50 million in 2025, rising to USD 369.88 million by 2030, because AI capacity rises from 35% of new megawatts in 2025 to 60% in 2030 and each AI megawatt needs about USD 1.10 million of high-throughput flash and parallel file systems.
Market Trends: How Is Australian Data Center Storage Changing?
Flash is replacing disk and object storage is replacing file shares: all-flash arrays rise from 52% of 2025 spend to 68% by 2035, DC Market Insights estimates.
Flash takes the primary tier
NetApp reported on 25 February 2026 that its all-flash array revenue grew 11% year on year to a record USD 1.0 billion in its fiscal third quarter, an annualised run rate of USD 4.2 billion (NetApp fiscal Q3 2026 results). In Australia, DC Market Insights puts all-flash arrays at 52% of 2025 spend and 68% by 2035, a 16.75% CAGR, while HDD-based systems grow only 7.17%.
Object storage becomes the capacity tier for AI and backup
Object storage rises from 18% of 2025 spend to 26% by 2035 (17.92% a year) because model checkpoints, media archives and immutable backup copies need S3-compatible capacity at a lower cost per terabyte than block storage. The Australian Signals Directorate’s Essential Eight, which lists regular backups as one of its eight controls, pushes agencies and listed companies toward immutable copies that object platforms provide.
Market Challenges: What Holds Back Australian Data Center Storage Spending?
Grid connection limits and falling cost per terabyte hold growth to 13.66% a year rather than the 23.35% seen from 2020 to 2025.
Grid connections delay the halls that would hold the arrays
The Australian Energy Market Operator (AEMO) reported in its 2026 Electricity Statement of Opportunities that 225 data centers with 67 gigawatts (GW) of combined capacity are in development, against about 5 terawatt-hours (TWh) of data center consumption in FY2026 (AEMO 2026 data centre forecasting overview). Only part of that pipeline will connect before 2030, so DC Market Insights limits new IT capacity to 620 MW in 2030 and 740 MW in 2035, which keeps AI storage near one fifth (20%) of 2035 spend.
Cost per terabyte keeps falling
Storage spend per installed megawatt falls from USD 0.40 million a year in 2020 to USD 0.34 million in 2025 and USD 0.25 million by 2035 in the DC Market Insights model, a 3.0% annual decline after 2025, because data reduction, denser flash modules and higher compute density per rack mean each megawatt of IT needs fewer storage dollars.
Market Opportunities: Where Can Storage Suppliers Win in Australia?
The two largest openings are AI cluster storage in Western Sydney and Melbourne West and sovereign storage for government and regulated industries, together about 30% of 2035 spend on DC Market Insights estimates.
AI cluster storage in Western Sydney and Melbourne West
Western Sydney (Eastern Creek and Kemps Creek) and Melbourne West (Derrimut and Truganina) account for 47% of 2025 storage spend and 54% by 2035. NEXTDC and OpenAI signed a non-binding memorandum on 5 December 2025 for the S7 Eastern Creek campus, with a first phase due in the second half of 2027 (Source: NEXTDC ASX announcement).
Sovereign storage for regulated buyers
Banks and insurers regulated by the Australian Prudential Regulation Authority (APRA) must meet Prudential Standard CPS 230 on operational risk, in force since 1 July 2025, which raises demand for replicated, onshore storage. DC Market Insights estimates that colocation-hosted enterprises, where most regulated buyers sit, hold 22% of 2025 spend and grow 12.58% a year.
How Much Does Data Center Storage Cost per Megawatt in Australia?
Australian data centers spend about USD 0.34 million on storage per installed megawatt each year in 2025, plus about USD 1.10 million one-off per megawatt of new AI capacity, DC Market Insights estimates.
| Year | Installed-base storage (USD million per MW-year) | AI cluster storage (USD million per new AI MW) |
|---|---|---|
| 2020 | 0.40 | 1.22 |
| 2025 | 0.34 | 1.10 |
| 2030 | 0.29 | 0.99 |
| 2035 | 0.25 | 0.90 |
Public anchors: NetApp’s record USD 1.0 billion all-flash quarter (February 2026) and NEXTDC’s FY2026 capital expenditure of AU$3.40 billion (Source: NEXTDC FY2026 results) frame the supply and the halls the arrays go into. The per-megawatt rates are DC Market Insights estimates; vendors do not publish Australian price lists.
Which Rules Shape Data Center Storage in Australia?
Five rules shape where and how USD 600.77 million of Australian data center storage is bought in 2025:
- Hosting Certification Framework (Digital Transformation Agency, March 2021): government data must sit in Certified Assured or Certified Strategic facilities.
- Security of Critical Infrastructure Act 2018, as amended in 2021 and 2022 (Department of Home Affairs): data storage or processing assets are critical infrastructure assets with risk-management duties.
- Privacy and Other Legislation Amendment Act 2024 (Parliament of Australia, December 2024): stronger penalties raise the cost of breaches of stored personal data.
- APRA Prudential Standards CPS 234 (information security, July 2019) and CPS 230 (operational risk, July 2025): regulated entities must keep tested, resilient copies of critical data.
- National Expectations for Data Centres and AI Infrastructure (Department of Industry, Science and Resources, 23 March 2026): new halls should add clean generation or storage and minimise water use.
Which Storage Type Leads the Australia Data Center Storage Market?
All-Flash Arrays lead with USD 312.40 million, 52% of 2025 spend, and Object Storage is the fastest architecture at 17.92% a year.
By Storage Type
| Segment | 2025 (USD million) | Share 2025 | 2035 (USD million) | CAGR 2025-2035 |
|---|---|---|---|---|
| All-Flash Arrays | 312.40 | 52% | 1,469.65 | 16.75% |
| Hybrid Flash Arrays | 144.18 | 24% | 345.80 | 9.14% |
| HDD-Based Systems | 108.14 | 18% | 216.13 | 7.17% |
| Tape and Archive Libraries | 36.05 | 6% | 129.68 | 13.66% |
By Architecture
| Segment | 2025 (USD million) | Share 2025 | 2035 (USD million) | CAGR 2025-2035 |
|---|---|---|---|---|
| Storage Area Network (SAN) | 204.26 | 34% | 518.70 | 9.77% |
| Network-Attached and Scale-Out File | 156.20 | 26% | 605.15 | 14.5% |
| Object Storage | 108.14 | 18% | 561.93 | 17.92% |
| Direct-Attached and Hyperconverged | 132.17 | 22% | 475.48 | 13.66% |
By Component
| Segment | 2025 (USD million) | Share 2025 | 2035 (USD million) | CAGR 2025-2035 |
|---|---|---|---|---|
| Hardware | 396.51 | 66% | 1,296.75 | 12.58% |
| Storage Software | 108.14 | 18% | 475.48 | 15.96% |
| Support and Managed Services | 96.12 | 16% | 389.03 | 15.01% |
By End User
| Segment | 2025 (USD million) | Share 2025 | 2035 (USD million) | CAGR 2025-2035 |
|---|---|---|---|---|
| Hyperscale and Cloud Providers | 276.36 | 46% | 1,253.53 | 16.32% |
| Colocation-Hosted Enterprises | 132.17 | 22% | 432.25 | 12.58% |
| On-Premises Enterprises | 120.15 | 20% | 259.35 | 8.0% |
| Government and Defence | 72.09 | 12% | 216.13 | 11.61% |
DC Exclusive: The Australian Storage Cost-per-MW Teardown
The Australian Storage Cost-per-MW Teardown is a DC Market Insights model built on 7 inputs (installed and new IT capacity from the Australia Data Center Infrastructure model, AI share of new capacity, four hall-type storage rates and the AI flash rate); it shows that an AI training hall buys about 3.2 times the storage of a conventional hyperscale hall per megawatt in its first year.
| Hall type | First-year storage (USD million per MW) | Run-rate storage (USD million per MW-year) | Main architecture |
|---|---|---|---|
| Enterprise and government hall | 0.55 | 0.55 | SAN and all-flash block |
| Retail colocation tenant | 0.40 | 0.40 | All-flash block and NAS |
| Hyperscale cloud hall | 0.34 | 0.26 | Direct-attached and object |
| AI training hall | 1.10 | 0.18 | Parallel file and all-flash |
| Weighted market average 2025 | 0.41 | 0.34 | Mixed |
The teardown explains the forecast shape: as AI halls take 60% of new capacity by 2030, first-year storage per new megawatt stays high, while run-rate spend per installed megawatt falls because hyperscale and AI halls carry less storage per megawatt than enterprise rooms.
Which Australian States Lead Data Center Storage Spending?
New South Wales leads with USD 372.48 million in 2025 (62%), and Queensland grows fastest at 19.13% a year to 2035.
| Region | 2025 (USD million) | Share 2025 | 2035 (USD million) | CAGR |
|---|---|---|---|---|
| New South Wales | 372.48 | 62% | 1,102.24 | 11.46% |
| Victoria | 162.21 | 27% | 708.89 | 15.89% |
| Queensland | 30.04 | 5% | 172.90 | 19.13% |
| Western Australia | 27.03 | 4.5% | 129.68 | 16.98% |
| South Australia ACT Tasmania and Northern Territory | 9.01 | 1.5% | 47.55 | 18.1% |
New South Wales
AEMO’s 2026 statement attributes 66% of FY2026 data center demand in the National Electricity Market to New South Wales, and DC Market Insights puts New South Wales at 51% of storage spend by 2035; the NSW draft Data Centre Policy Framework of 17 August 2026 promises 75-day assessments for qualifying projects (Source: Infrastructure NSW).
Victoria
Victorian data center demand averaged 187 MW in the first quarter of 2026, up 94% from 96 MW a year earlier (Source: AEMO Quarterly Energy Dynamics Q1 2026); Victoria’s storage spend grows 15.89% a year to 32.8% of the market by 2035.
Queensland
Queensland is the fastest region at 19.13% a year, from 5% of spend in 2025 to 8% in 2035, because Brisbane campuses add AI capacity on cheaper land and grid connections than inner Sydney.
Western Australia
Western Australia sits outside the National Electricity Market on the South West Interconnected System; its storage spend rises from 4.5% to 6% of the market as Perth gains sovereign and mining-sector capacity.
South Australia, ACT, Tasmania and Northern Territory
These smaller markets total 1.5% of 2025 spend, led by certified government halls in Canberra, and grow 18.1% a year.
Where Is Australian Data Center Storage Bought, Location by Location?
Western Sydney (Eastern Creek and Kemps Creek) is the largest location at USD 180.24 million in 2025; Brisbane is the fastest large location at 19.13% a year.
| Rank | Location | 2025 (USD million) | 2035 (USD million) | CAGR |
|---|---|---|---|---|
| 1 | Western Sydney (Eastern Creek and Kemps Creek) | 180.24 | 648.37 | 13.66% |
| 2 | Melbourne West (Derrimut and Truganina) | 102.13 | 514.38 | 17.55% |
| 3 | Macquarie Park | 72.09 | 172.90 | 9.14% |
| 4 | Rest of New South Wales | 66.09 | 172.90 | 10.09% |
| 5 | Sydney Inner South (Alexandria and Mascot) | 54.07 | 108.06 | 7.17% |
| 6 | Melbourne Docklands and Port Melbourne | 42.05 | 129.68 | 11.92% |
| 7 | Brisbane | 30.04 | 172.90 | 19.13% |
| 8 | Perth | 27.03 | 129.68 | 16.98% |
| 9 | Rest of Victoria | 18.02 | 64.84 | 13.66% |
| 10 | Canberra | 5.41 | 28.10 | 17.91% |
| 11 | Adelaide | 2.40 | 12.97 | 18.38% |
| 12 | Hobart and Darwin | 1.20 | 6.48 | 18.37% |
Forecast Scenarios: How Large Could Australian Data Center Storage Be by 2035?
The Australia Data Center Storage Market reaches USD 2.16 billion by 2035 in the base case, between USD 1.63 billion in the low case and USD 2.77 billion in the high case.
| Scenario | 2035 (USD million) | CAGR 2025-2035 | Assumption |
|---|---|---|---|
| Low | 1,630.54 | 10.50% | Grid delays hold new IT capacity near 500 MW a year |
| Base | 2,161.26 | 13.66% | New IT capacity 620 MW in 2030, 740 MW in 2035 |
| High | 2,766.73 | 16.50% | AI share of new capacity above 75% from 2030 |
Key Players and Market Share: Who Supplies Data Center Storage in Australia?
Dell Technologies, NetApp and Hewlett Packard Enterprise (HPE) hold about 47% of Australian external array spend together, DC Market Insights estimates from vendor installed-base counts and partner disclosures; hyperscale providers build most of their own storage from direct-attached nodes.
- Dell Technologies
- NetApp
- Hewlett Packard Enterprise (HPE)
- Pure Storage
- IBM
- Hitachi Vantara
- Lenovo
- Nutanix
- Western Digital
- Seagate Technology
- Quantum Corporation
- Cohesity
- Commvault
- Data#3 (reseller and integrator)
NetApp’s all-flash array revenue reached a record USD 1.0 billion in the quarter to January 2026 (Source: NetApp results). NEXTDC, Australia’s largest listed operator, reported 287.9 MW built at 30 June 2026 (Source: NEXTDC FY2026 results), and its tenants are the largest single pool of colocation-hosted storage buyers.
Recent Developments in Australian Data Center Storage
- In August 2026, NEXTDC reported pro forma contracted utilisation of 740.1 MW, three times the prior year (Source: NEXTDC FY2026 results).
- In August 2026, AEMO counted 225 data centers with 67 GW of capacity in development (Source: AEMO 2026 Electricity Statement of Opportunities).
- In March 2026, the Department of Industry, Science and Resources published the National Expectations for Data Centres and AI Infrastructure (Source: Department of Industry, Science and Resources).
- In February 2026, NetApp reported a record USD 1.0 billion all-flash array quarter (Source: NetApp).
- In December 2025, NEXTDC and OpenAI signed a non-binding memorandum for the S7 Eastern Creek campus (Source: NEXTDC ASX announcement).
- In June 2025, Amazon announced AU$20 billion of Australian data center investment for 2025-2029 (Source: Amazon).
Research Methodology: How the Model Sizes Australian Data Center Storage
DC Market Insights sizes the market bottom-up from 16 years of capacity data and 7 model inputs. Installed IT capacity starts at 450 MW at the end of 2019, adds 120 MW of new IT in 2020, 300 MW in 2025, 620 MW in 2030 and 740 MW in 2035, and retires 1% a year, giving 1,571 MW at the end of 2025 and 7,226 MW in 2035 (the same capacity series as the Australia Data Center Infrastructure model). Average installed MW × storage spend per MW-year (USD 0.40 million in 2020, 0.34 in 2025, 0.29 in 2030, 0.25 in 2035) gives the installed-base line; new MW × AI share (5% 2020, 35% 2025, 60% 2030, 66% 2035) × USD 1.10 million per AI MW (−2% a year) gives the AI line. Full method: research methodology.
Three bound checks: (1) ceiling: USD 600.77 million is 2.3% of the Data Center Storage Market of USD 26.17 billion in 2025, against Australia’s roughly 1.4% share of global installed capacity, a premium consistent with higher Australian labour and support costs; (2) ceiling: 2025 storage equals 23% of one year of Amazon’s AU$20 billion five-year plan at USD 0.65 per Australian dollar; (3) floor: NEXTDC’s 175.0 MW billing × USD 0.34 million = USD 59.5 million, about 10% of the market from one operator’s tenants. The United Kingdom Data Center Storage Market uses the same per-megawatt structure for comparison.
Table of contents
- 01Introduction
- 1.1Market Definition and Scope
- 1.2Research Methodology
- 02Executive Summary
- 2.1Market Snapshot, 2025, 2026 and 2035
- 2.2Key Market Statistics
- 2.3Key Takeaways
- 03Market Scope and Estimate Comparison
- 3.1Included and Excluded Spend
- 3.2Why Estimates Differ
- 04Market Drivers
- 4.1NEXTDC Contracted Capacity
- 4.2Hosting Certification Framework
- 4.3Amazon AU$20 Billion Plan
- 05Market Trends
- 5.1Flash Takes the Primary Tier
- 5.2Object Storage as the Capacity Tier
- 06Market Challenges
- 6.1Grid Connection Limits
- 6.2Falling Cost per Terabyte
- 07Market Opportunities
- 7.1AI Cluster Storage in Western Sydney and Melbourne West
- 7.2Sovereign Storage for Regulated Buyers
- 08Pricing Analysis
- 8.1Storage Spend per MW, 2020-2035
- 09Standards and Regulation
- 9.1Hosting Certification Framework
- 9.2SOCI Act 2018
- 9.3Privacy Act Amendments 2024
- 9.4APRA CPS 234 and CPS 230
- 9.5National Expectations for Data Centres
- 10Market Segmentation
- 10.1By Storage Type
- 10.2All-Flash Arrays
- 10.3Hybrid Flash Arrays
- 10.4HDD-Based Systems
- 10.5Tape and Archive Libraries
- 10.6By Architecture
- 10.7Storage Area Network (SAN)
- 10.8Network-Attached and Scale-Out File
- 10.9Object Storage
- 10.10Direct-Attached and Hyperconverged
- 10.11By Component
- 10.12Hardware
- 10.13Storage Software
- 10.14Support and Managed Services
- 10.15By End User
- 10.16Hyperscale and Cloud Providers
- 10.17Colocation-Hosted Enterprises
- 10.18On-Premises Enterprises
- 10.19Government and Defence
- 11DC Exclusive: Australian Storage Cost-per-MW Teardown
- 11.1Storage per MW by Hall Type
- 12Regional Insights
- 12.1New South Wales
- 12.2Victoria
- 12.3Queensland
- 12.4Western Australia
- 12.5South Australia ACT Tasmania and Northern Territory
- 13Location Analysis
- 13.1Western Sydney (Eastern Creek and Kemps Creek)
- 13.2Melbourne West (Derrimut and Truganina)
- 13.3Macquarie Park
- 13.4Rest of New South Wales
- 13.5Sydney Inner South (Alexandria and Mascot)
- 13.6Melbourne Docklands and Port Melbourne
- 13.7Brisbane
- 13.8Perth
- 13.9Rest of Victoria
- 13.10Canberra
- 13.11Adelaide
- 13.12Hobart and Darwin
- 14Forecast Scenarios
- 14.1Low Case
- 14.2Base Case
- 14.3High Case
- 15Competitive Insights
- 15.1Dell Technologies
- 15.2NetApp
- 15.3Hewlett Packard Enterprise (HPE)
- 15.4Pure Storage
- 15.5IBM
- 15.6Hitachi Vantara
- 15.7Lenovo
- 15.8Nutanix
- 15.9Western Digital
- 15.10Seagate Technology
- 15.11Quantum Corporation
- 15.12Cohesity
- 15.13Commvault
- 15.14Data#3
- 16Recent Developments
- 16.1Developments 2025-2026
- 17Research Methodology
- 17.1Model Inputs
- 17.2Bound Checks
- Fig. 1Australia Data Center Storage Market Size, 2020-2035 (USD Million)
- Table 1Market Snapshot
- Table 2Scope Comparison
- Table 3Storage Spend per MW, 2020-2035
- Table 4Market by Storage Type
- Table 5Market by Architecture
- Table 6Market by Component
- Table 7Market by End User
- Table 8Storage Cost-per-MW Teardown
- Table 9Market by Region
- Table 10Market by Location
- Table 11Forecast Scenarios
About this report
Written by Amit Jain and reviewed by Deepti Agrawal, Senior Editor, Research. Figures are built top-down and bottom-up and reconciled before publication, with 2025 as the base year.
Read our methodologyHow we built this
- Historical period2020-2024
- Base year2025
- Forecast period2026-2035
- Sizing approachTop-down + bottom-up
Need more than the report?
Advisory on this market
Due diligence, site selection and market entry work, by the analysts who wrote this report.
See consulting servicesFrequently asked questions
USD 742.34 million in 2026, up 23.56% from USD 600.77 million in 2025, according to DC Market Insights estimates. The market is projected to reach USD 2.16 billion by 2035, a CAGR of 13.66% from 2025.
13.66% a year from 2025 to 2035, DC Market Insights estimates, slower than the 23.35% of 2020-2025 because storage spend per megawatt falls about 3% a year while installed capacity keeps rising.
All-flash arrays, at USD 312.40 million or 52% of 2025 spend, rising to 68% by 2035 because AI clusters need flash throughput to keep GPUs busy.
Object storage, at 17.92% a year from USD 108.14 million in 2025, because AI checkpoints, media archives and immutable backups move to S3-compatible capacity tiers.
New South Wales, with USD 372.48 million or 62% of 2025 spend; Queensland grows fastest at 19.13% a year as Brisbane campuses add AI capacity.
About USD 0.34 million per installed megawatt a year in 2025, plus about USD 1.10 million one-off per megawatt of new AI capacity, DC Market Insights estimates; the yearly rate falls to USD 0.25 million by 2035.
Dell Technologies, NetApp and Hewlett Packard Enterprise hold about 47% of external array spend together (DC Market Insights estimate), followed by Pure Storage, IBM, Hitachi Vantara and Lenovo.
Government and Defence buyers spend USD 72.09 million in 2025 because the Hosting Certification Framework keeps classified and sensitive government data in certified onshore facilities.
Estimates differ by up to 6 times because broader definitions add servers, cloud storage subscriptions and endpoint storage; DC Market Insights counts only storage equipment, software and support bought for data center halls.
Between USD 1.63 billion and USD 2.77 billion, with a base case of USD 2.16 billion, DC Market Insights estimates; grid connection timing decides which case plays out.
Get this report
How do I get the full report?
Request a quote; we reply by email within one business day.
How and when will I receive the report?
By email, within 24-48 business hours of payment.
How can I pay?
Once you accept the quote, we email you a secure payment link.
Can I see a sample first?
Yes. Request a free sample and we will email it to you.
Can the report be tailored to my needs?
Yes. We can add countries, segments or data cuts. Talk to an analyst about the scope you need.
Can I get an invoice or pay against a purchase order?
Write to sales@dcmarketinsights.com and our team will help.