
Iberia Data Center Market Size, Share & Forecast to 2035
Market at a glance
The Iberia Data Center market was worth USD 11.53 billion in 2025 and is forecast to reach USD 22.63 billion by 2035, growing at a 4.6% CAGR.
 By Priyanka Mor, Senior Consultant
 Reviewed by Deepti Agrawal
Last updated 21 Sep 2026
Base year 2025 PDF + Excel
Key findings
Expansion Of AI, Cloud And Hyperscale Computing Infrastructure
Grid Capacity And Power Availability Constraints
AI-Ready And High-Density Data Center Campuses
What is inside the report
- 01Genesis of the market
- 02Executive lens
- 03Data center market forces & industry pulse
- 04Key investment epicenter
- 05Revenue trajectory & wealth mapping
- 06Trade & commerce analysis
- 07Competition analysis
- 08Data center market – by component segment analysis
- 09Data center market – by type segment analysis
- 10Data center market – by deployment model segment analysis
- 15chapters
- USD 8,163.61 Million in 2021Historical period
- 2025-2035Forecast period
- —Companies profiled
Recent developments
Start Campus formally inaugurated SIN01, a 26 MW data center and the first operational facility in its planned 1.2 GW SINES Data Campus in Portugal.
Start Campus announced that SIN01 and planned SIN02 had achieved OCP Ready v2 certification for hyperscale data centers.
CoreWeave and MERLIN Edged announced deployment of an AI supercomputer at the Barcelona Zona Franca data center, with 10,224 NVIDIA H200 GPUs and 15 MW of IT capacity.
DATA4 announced that Arjun Infrastructure Partners and Interogo Holding had joined its shareholder base to support further European expansion.
Equinix inaugurated its MD5 data center in Alcobendas, Madrid, supporting a broader EUR 460 million investment in the campus.
MERLIN Properties reported that its data center division had reached 160 MW of leased capacity.
Full analysis
Executive Summary
The Iberia Data Center Market size was valued at USD 8,163.61 million in 2021, increased to USD 11,530.26 million in 2025 and is anticipated to reach USD 22,627.01 million by 2035. Based on the supplied 2025 and 2035 market values, the overall market trajectory implies growth of approximately 7.0% annually over the forecast period. The market sizing, segmentation and segment-level CAGR figures in this report are retained from the supplied dataset.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Market Size | USD 8,163.61 Million in 2021 |
| Base Year | 2025 |
| Forecast Period | 2025-2035 |
| Iberia Data Center Market Size 2025 | USD 11,530.26 Million |
| Iberia Data Center Market Size 2035 | USD 22,627.01 Million |
| Geographic Coverage | Spain and Portugal |
| Fastest-Growing Data Center Type | Enterprise, CAGR 5.2% |
| Key Markets | Madrid, Barcelona, Bilbao, Lisbon and Sines |
The Iberia data center market is entering a larger infrastructure investment cycle as Spain and Portugal attract hyperscale, AI, cloud, colocation and enterprise computing projects. Madrid remains a central connectivity and colocation hub, while Barcelona, Bilbao and emerging Spanish locations are attracting AI-oriented capacity. Portugal is developing a distinctive position around Lisbon and Sines, supported by large-scale renewable-energy-linked campus developments and subsea connectivity.
Current investment activity illustrates the scale of this transition. Iron Mountain describes its Madrid campus as a 79 MW approved IT capacity development with eight planned facilities, while DATA4 operates and develops a Madrid campus with 100 MW of electrical reserves. In Portugal, Start Campus inaugurated the 26 MW SIN01 facility in April 2025 as the first building of a planned 1.2 GW SINES Data Campus, positioning the site for cloud, AI and HPC workloads.
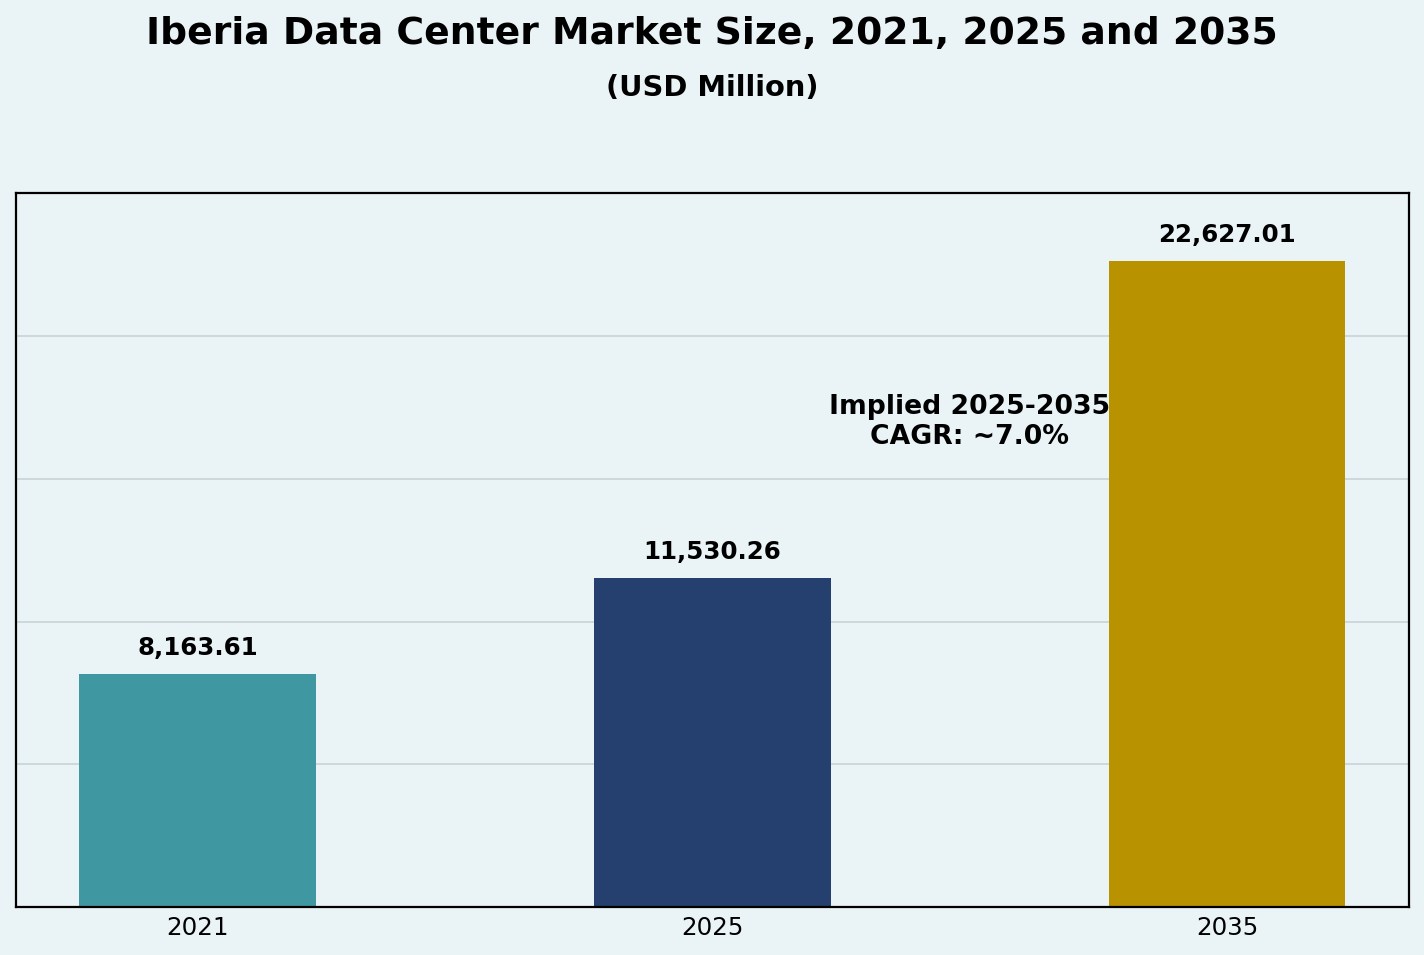
Iberia Data Center Market Size
The Iberia Data Center Market grew from USD 8.16 billion in 2021 to USD 11.53 billion in 2025 and is forecast to reach USD 22.63 billion by 2035. Expansion reflects rising computing demand, growth of cloud platforms, AI infrastructure investment, colocation requirements, enterprise digital transformation and a widening need for high-density power and cooling infrastructure.
Spain is benefiting from established connectivity ecosystems in Madrid and Barcelona, expanding hyperscale and colocation campuses and new AI infrastructure investments. Equinix opened its MD5 facility in Alcobendas in May 2026 as part of a EUR 460 million investment in its Madrid campus. MERLIN Properties also reported that its data center division reached 160 MW leased during the first half of 2026, indicating continued commercial demand for capacity across its infrastructure portfolio.
Portugal is gaining strategic importance through Sines, Lisbon and Porto. Start Campus’ SIN01 is the first operational building of its planned 1.2 GW campus, while NOS Sistemas operates data centers in Greater Lisbon and the Porto metropolitan area and provides cloud, data center, IT management and security services.
Market Dynamics
Market Drivers
Expansion Of AI, Cloud And Hyperscale Computing Infrastructure
The rapid growth of AI training, inference, cloud computing and high-performance workloads is increasing demand for new data center capacity across Iberia. Spain is seeing growing deployment of high-density computing facilities designed around GPUs and accelerated computing. In Barcelona, MERLIN Properties and Edged Energy host a CoreWeave installation with 10,224 NVIDIA H200 GPUs in a 15 MW IT facility, with further expansion planned around Blackwell infrastructure. Portugal is also positioning for AI and HPC deployments. Start Campus describes its Sines development as a gigascale cloud, AI and HPC-ready campus with a planned capacity of 1.2 GW.
Strong Growth In Colocation And Interconnection Demand
Enterprises increasingly rely on carrier-neutral and cloud-connected facilities rather than operating all computing infrastructure internally. This trend supports colocation capacity in Madrid, Barcelona, Lisbon and other regional hubs. DATA4’s Madrid campus provides 100 MW of electrical reserves and access to a broad ecosystem of cloud and telecom providers. Iron Mountain’s Madrid campus is positioned on the Barcelona-Madrid fiber backbone and has 79 MW of approved IT capacity.
Iberia’s Connectivity Between Europe, Africa And The Americas
Spain and Portugal occupy a strategic position between major European markets and international subsea cable routes connecting Europe with the Americas and Africa. This connectivity supports cloud, content, telecom and international enterprise workloads. MERLIN’s Madrid-Getafe data center highlights direct low-latency fiber connections to Bilbao, Barcelona and Lisbon submarine cable landing points, while Iron Mountain describes Madrid as a strategic gateway linking Southern Europe with Latin America, North America and North Africa.
Availability Of Renewable Energy And Sustainable Infrastructure
Renewable electricity availability and growing pressure to improve data center efficiency strengthen Iberia’s appeal for new infrastructure. Operators are increasingly integrating renewable procurement, lower-water cooling and high-efficiency designs into new campuses. Start Campus states that SIN01 is designed for 100% renewable energy and uses seawater cooling, with a design PUE of 1.1 and no consumptive water use for cooling. MERLIN and Edged have also positioned proposed Extremadura AI campuses around abundant local power availability and green energy.
Market Restraints
Grid Capacity And Power Availability Constraints
Data center growth requires large and dependable electricity connections. As planned campuses move from tens of megawatts toward hundreds of megawatts or gigawatt-scale developments, securing grid access can become one of the most important constraints on project timing. The scale of planned projects illustrates this challenge, including Start Campus’ 1.2 GW campus in Sines and other large AI-oriented developments.
Rising Capital Requirements For AI-Ready Facilities
AI and HPC environments require more expensive electrical systems, liquid cooling, high-capacity networking, advanced racks and resilient facility designs. These requirements increase construction and equipment costs compared with conventional enterprise data centers. MERLIN states that its planned AI-oriented infrastructure can support densities of up to 70 kW per rack with air cooling and up to 200 kW per rack with liquid cooling.
Environmental And Regulatory Requirements
Energy efficiency, water consumption, environmental impact and security requirements are becoming more important for Iberian data center developments. Operators must align new facilities with European and national reporting, sustainability and security frameworks. NOS publishes data center energy information in Portugal under Decree-Law No. 84/2024, while MERLIN-Edged has obtained multiple environmental, energy and information-security certifications for its data center operations.
Market Opportunities
AI-Ready And High-Density Data Center Campuses
AI represents one of the largest opportunities for Iberian data center operators. High-density GPU clusters create demand for advanced power distribution, liquid cooling and large-scale capacity. Madrid, Barcelona, Sines and emerging Spanish regions can capture demand from hyperscalers, AI cloud providers and enterprises seeking European compute capacity.
Development Of Portugal As A Large-Scale Data Center Gateway
Portugal has the opportunity to become a major Southern European landing point for cloud and AI infrastructure due to its Atlantic position, renewable generation and expanding international connectivity. Start Campus’ 1.2 GW project is privately funded at approximately EUR 8.5 billion and is designed to serve cloud, AI and HPC demand.
Growth Of Edge And Modular Infrastructure
Edge, micro and modular data centers provide an opportunity as telecom operators, industrial organizations, retailers and public-sector users deploy computing resources closer to users and devices. The segment is relevant for latency-sensitive applications, 5G, autonomous systems, industrial analytics and distributed AI inference. NOS has demonstrated mobile edge computing in Portugal for autonomous mobility use cases over its 5G network.
Enterprise Hybrid Cloud Modernization
Large enterprises and SMEs continue to modernize applications through combinations of on-premises infrastructure, colocation and public cloud services. This supports demand for hybrid deployment models, managed services and connected data center infrastructure. NOS offers AWS Outposts from its Portuguese data center environment for workloads requiring local processing, lower latency or domestic data residency.
Technology Trends
Increasing Rack Density And Liquid Cooling Adoption
AI workloads are increasing rack power density and forcing operators to rethink thermal design. Direct liquid cooling, high-capacity distribution systems and hybrid cooling are becoming more important in new facilities intended for accelerated computing. MERLIN’s current infrastructure strategy includes designs capable of supporting up to 200 kW per rack with liquid cooling.
DCIM, Automation And Infrastructure Orchestration
Operators are increasing use of DCIM, monitoring, orchestration and automation software to improve energy management, capacity planning and operational resilience. These tools become more important as facilities expand in scale and mix conventional enterprise workloads with cloud, HPC and AI infrastructure.
Renewable Energy And Water-Efficient Cooling
Sustainability is becoming a design requirement rather than a secondary feature. Operators are focusing on renewable power procurement, reduced PUE, waterless or low-water cooling and real-time energy monitoring. Start Campus targets a design PUE of 1.1 using renewable energy and seawater cooling, while MERLIN promotes waterless cooling across its digital infrastructure portfolio.
Open Infrastructure For Hyperscale And AI Workloads
Open hardware standards are becoming relevant as hyperscale operators deploy standardized, high-density computing systems. In May 2025, Start Campus announced that SIN01 and planned SIN02 became the first Southern European facilities certified OCP Ready v2 for hyperscale data centers.
Iberia Data Center Market Segmentation
By Country
The Iberia Data Center Market by country includes Spain and Portugal. Spain represents the more established concentration of major commercial data center campuses, particularly around Madrid, with additional activity in Barcelona, Bilbao and new regional locations. Portugal is developing rapidly around Lisbon, Porto and especially Sines, supported by subsea connectivity and large-scale campus development.
By Component
| Component | Segment |
|---|---|
| Hardware | Servers, Storage, Networking, Racks, Power, Cooling, Security Systems |
| Software | DCIM, Virtualization, Orchestration, Automation, Monitoring |
| Services | Consulting, Integration, Managed Services, Maintenance & Support |
Hardware represents the physical foundation of Iberian data center investment, with demand concentrated around servers, storage, networking, racks, power systems and cooling. AI infrastructure is increasing the importance of GPU servers, high-capacity power distribution and liquid cooling. Software is increasingly important as operators require greater visibility into power consumption, thermal performance, asset utilization and workload placement. Services remain important for design, consulting, systems integration, operations, preventive maintenance and managed infrastructure support.
By Type
| Date Center Type | CAGR |
|---|---|
| Hyperscale | 4.6% |
| Colocation | 3.5% |
| Enterprise | 5.2% |
| Edge / Micro / Modular | 3.2% |
| Mega Data Centers | 2.9% |
| Cloud / Internet Data Centers (IDC) | 1.2% |
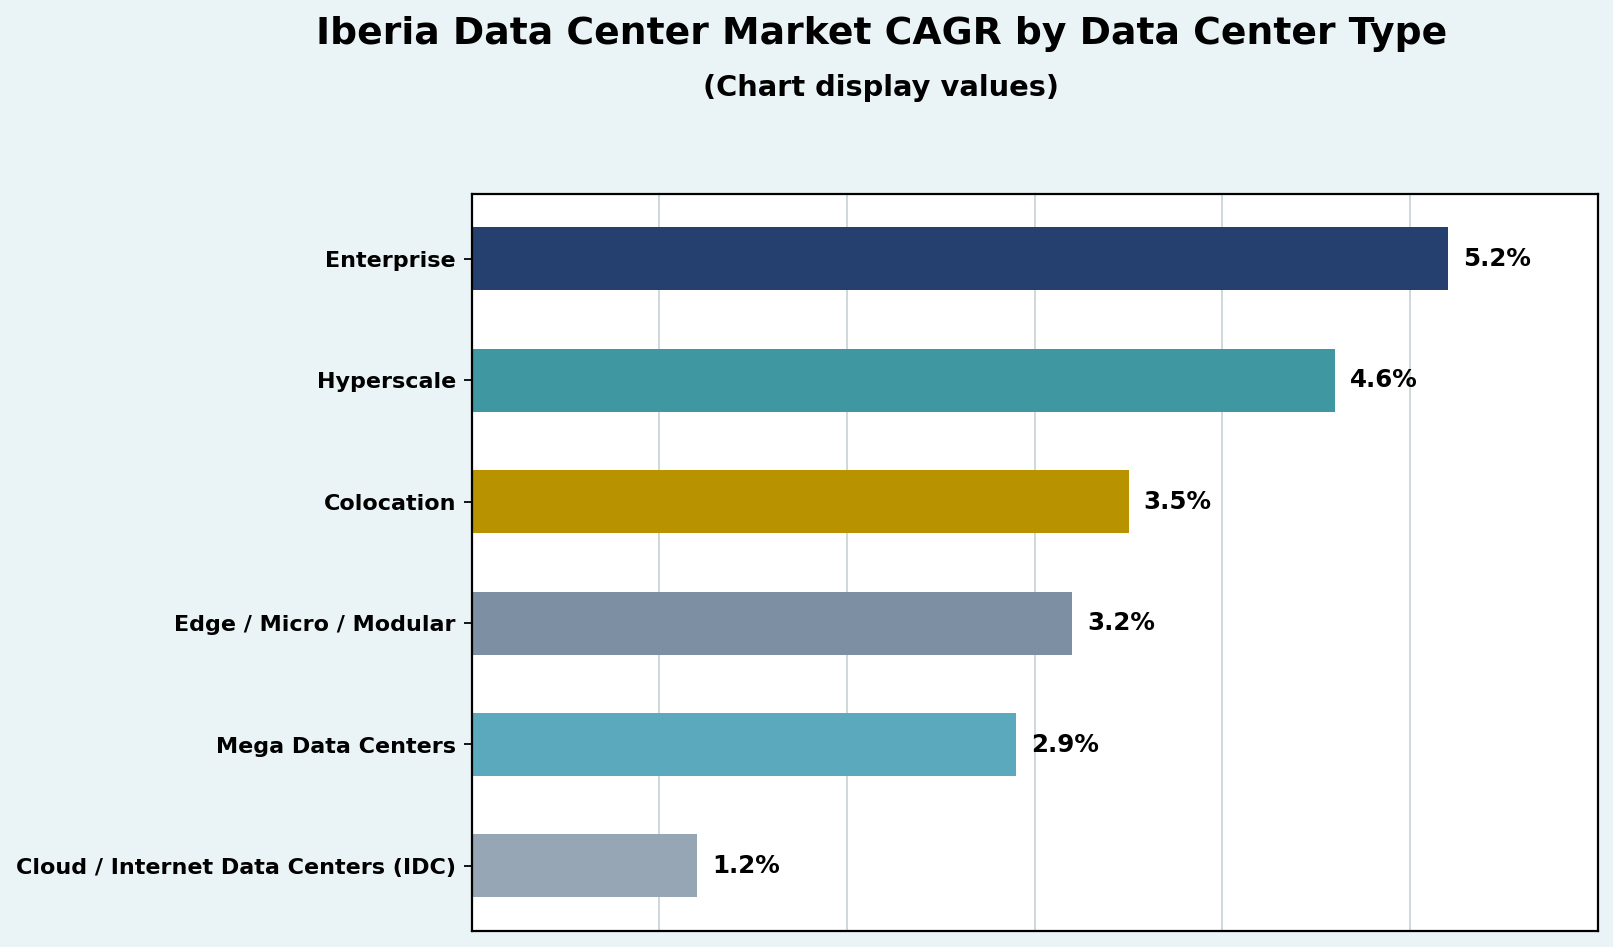
Figure 2. Data Center Type CAGR Comparison
Hyperscale
Hyperscale data centers are projected to grow at a CAGR of 4.6%. Demand is supported by cloud services, AI clusters and large-scale digital platforms. Portugal’s Sines campus and large Spanish AI-oriented infrastructure projects strengthen the segment’s development potential.
Colocation
Colocation data centers are projected to grow at a CAGR of 3.5%. Demand is supported by enterprises seeking secure, connected infrastructure without owning facilities. Madrid remains a major colocation concentration, supported by Equinix, DATA4, Iron Mountain, Digital Realty and other operators.
Enterprise
Enterprise data centers show the highest supplied segment CAGR at 5.2%. Demand is supported by hybrid IT, regulatory requirements, data sovereignty, private cloud and modernization of mission-critical infrastructure.
Edge / Micro / Modular
Edge, micro and modular data centers are projected to grow at a CAGR of 3.2%. Use cases include telecom networks, industrial computing, smart infrastructure, autonomous mobility, retail and latency-sensitive AI applications.
Mega Data Centers
Mega data centers are projected to grow at a CAGR of 2.9%. This category benefits from large cloud and AI campuses that consolidate substantial compute capacity within high-power sites.
Cloud / Internet Data Centers (IDC)
Cloud and internet data centers are projected to grow at a CAGR of 1.2%. Growth is supported by SaaS adoption, digital services and public-cloud expansion, although the supplied CAGR indicates a more moderate growth trajectory relative to other data center types.
By Deployment Model
The market by deployment model includes on-premises, cloud-based and hybrid infrastructure. On-premises deployments remain relevant for organizations requiring direct control, low latency, data sovereignty or specialized infrastructure. Cloud-based environments benefit from continued migration of enterprise applications and digital platforms. Hybrid deployments are becoming increasingly important because organizations need to combine cloud scalability with local infrastructure, colocation capacity and private environments.
By Enterprise Size
The market includes large enterprises and small and medium enterprises (SMEs). Large enterprises generate substantial demand because they operate complex applications, large data estates and hybrid infrastructure. SMEs increasingly rely on colocation, cloud and managed services because these models reduce upfront infrastructure requirements while providing access to enterprise-grade availability and security.
By Application
The Iberia Data Center Market by application includes BFSI, IT & Telecom, Government & Defense, Healthcare, Retail & E-commerce, Media & Entertainment, Manufacturing and Others, including Education, Energy & Utilities and related sectors. IT and telecom are major infrastructure users due to cloud services, network operations, content delivery and digital communications.
By End-user
The market by end-user includes cloud service providers, enterprises, colocation providers, government agencies and others. Cloud service providers require large-scale infrastructure for compute, storage, AI and digital services. Colocation providers are expanding capacity as enterprises seek flexible alternatives to owned infrastructure.
Regional Insights
Spain
Spain forms the largest concentration of established data center infrastructure within Iberia, with Madrid acting as the main commercial hub and Barcelona and Bilbao providing additional capacity. Madrid benefits from extensive fiber connectivity, major cloud availability zones and growing international interconnection. Equinix inaugurated MD5 in Alcobendas in May 2026 as part of a EUR 460 million campus investment. DATA4 operates a Madrid campus with 100 MW of power reserves, while Iron Mountain’s Madrid campus has 79 MW of approved IT capacity and plans eight facilities. Spain is also moving toward AI-intensive data centers, with MERLIN reporting 160 MW of leased data center capacity by the first half of 2026.
Portugal
Portugal is developing into an important Atlantic data center gateway, led by Sines and supported by Lisbon and Porto. The market benefits from subsea connectivity, renewable generation, available land and large-scale campus development. Start Campus inaugurated the 26 MW SIN01 facility in April 2025 as the first building within its planned 1.2 GW SINES Data Campus. NOS Sistemas also maintains established enterprise infrastructure in Greater Lisbon and Porto.
Competitive Insights
| Company | Positioning / Presence |
|---|---|
| Equinix, Inc. | Colocation and interconnection; Madrid expansion |
| Digital Realty Trust, Inc. | Global colocation and hyperscale infrastructure |
| Global Switch | Large-scale carrier-neutral data center infrastructure |
| DATA4 Group | Madrid campus and European data center platform |
| Iron Mountain Data Centers | Madrid campus and hyperscale/colocation capacity |
| Edged Energy / Edged Data Centers | High-density and water-efficient facilities |
| MERLIN Properties | Spain and Portugal digital infrastructure expansion |
| Start Campus | Sines hyperscale AI/HPC campus |
| NOS Sistemas | Portugal data center, cloud and managed IT services |
| Others | Regional and international operators |
The Iberia Data Center Market features global colocation companies, European infrastructure operators, property-backed data center platforms and regional technology providers. Competition increasingly centers on access to power, time-to-market, high-density AI readiness, fiber connectivity, cloud ecosystems, sustainability and expansion pipelines. AI-ready capacity is emerging as an important competitive factor, while sustainability remains a differentiator through renewable power, low PUE, water-efficient cooling and formal environmental certifications.
Recent Developments
- In April 2025, Start Campus formally inaugurated SIN01, a 26 MW data center and the first operational facility in its planned 1.2 GW SINES Data Campus in Portugal.
- In May 2025, Start Campus announced that SIN01 and planned SIN02 had achieved OCP Ready v2 certification for hyperscale data centers.
- In May 2025, CoreWeave and MERLIN Edged announced deployment of an AI supercomputer at the Barcelona Zona Franca data center, with 10,224 NVIDIA H200 GPUs and 15 MW of IT capacity.
- During 2025, MERLIN began construction of its Lisbon data center and continued expansion activity in Bilbao while securing additional sites in Madrid.
- In August 2025, DATA4 announced that Arjun Infrastructure Partners and Interogo Holding had joined its shareholder base to support further European expansion.
- In May 2026, Equinix inaugurated its MD5 data center in Alcobendas, Madrid, supporting a broader EUR 460 million investment in the campus.
- In July 2026, MERLIN Properties reported that its data center division had reached 160 MW of leased capacity.
Table of contents
- 01Genesis of the market
- 1.1Market Prelude – Introduction & Scope
- 1.2The Big Picture – Objectives & Vision
- 1.3Strategic Edge – Unique Value Proposition
- 1.4Stakeholder Compass – Key Beneficiaries
- 02Executive lens
- 2.1Pulse of the Industry – Market Snapshot
- 2.2Growth Arc – Revenue Projections (USD Million)
- 2.3Premium Insights – Based on Primary Interviews
- 03Data center market forces & industry pulse
- 3.1Foundations of Change – Market Overview
- 3.2Catalysts of Expansion – Key Market Drivers
- 3.2.1Momentum Boosters – Growth Triggers
- 3.2.2Innovation Fuel – Disruptive Technologies
- 3.3Headwinds & Crosswinds – Market Restraints
- 3.3.1Regulatory Tides – Compliance Challenges
- 3.3.2Economic Frictions – Inflationary Pressures
- 3.4Untapped Horizons – Growth Potential & Opportunities
- 3.5Strategic Navigation – Industry Frameworks
- 3.5.1Market Equilibrium – Porter’s Five Forces
- 3.5.2Ecosystem Dynamics – Value Chain Analysis
- 3.5.3Macro Forces – PESTEL Breakdown
- 3.6Price Trend Analysis
- 3.6.1Country-wise Price Trend
- 3.6.2Price Trend by Product
- 04Key investment epicenter
- 4.1Country-wise Goldmines – High-Growth Geographies
- 4.2Product Frontiers – Lucrative Product Categories
- 4.3Application Sweet Spots – Emerging Demand Segments
- 05Revenue trajectory & wealth mapping
- 5.1Momentum Metrics – Forecast & Growth Curves
- 5.2Country-wise Revenue Footprint – Market Share Insights
- 5.3Segmental Wealth Flow – Component & Type Revenue
- 06Trade & commerce analysis
- 6.1Import Analysis by Country
- 6.1.1Iberia Data Center Import Revenue By Country
- 6.2Export Analysis by Country
- 6.2.1Iberia Data Center Export Revenue By Country
- 07Competition analysis
- 7.1Company Market Share Analysis
- 7.1.1Iberia Data Center: Company Market Share
- 7.2Iberia Data Center Company Revenue Market Share
- 7.3Strategic Developments
- 7.3.1Acquisitions & Mergers
- 7.3.2New Product Launch
- 7.3.3Country-wise Expansion
- 7.4Competitive Dashboard
- 7.5Company Assessment Metrics, 2025
- 08Data center market – by component segment analysis
- 8.1Data Center Overview by Component Segment
- 8.1.1Data Center Revenue Share By Component
- 8.2Hardware (Servers, Storage, Networking, Racks, Power, Cooling, Security Systems)
- 8.3Software (DCIM, Virtualization, Orchestration, Automation, Monitoring)
- 8.4Services (Consulting, Integration, Managed Services, Maintenance & Support)
- 09Data center market – by type segment analysis
- 9.1Data Center Overview by Type Segment
- 9.1.1Data Center Revenue Share By Type
- 9.2Hyperscale
- 9.3Colocation
- 9.4Enterprise
- 9.5Edge / Micro / Modular
- 9.6Mega Data Centers
- 9.7Cloud / Internet Data Centers (IDC)
- 10Data center market – by deployment model segment analysis
- 10.1Data Center Overview by Deployment Model Segment
- 10.1.1Data Center Revenue Share By Deployment Model
- 10.2On-Premises
- 10.3Cloud-based
- 10.4Hybrid
- 11Data center market – by enterprise size segment analysis
- 11.1Data Center Overview by Enterprise Size Segment
- 11.1.1Data Center Revenue Share By Enterprise Size
- 11.2Large Enterprises
- 11.3Small & Medium Enterprises (SMEs)
- 12Data center market – by application segment analysis
- 12.1Data Center Overview by Application Segment
- 12.1.1Data Center Revenue Share By Application
- 12.2BFSI
- 12.3IT & Telecom
- 12.4Government & Defense
- 12.5Healthcare
- 12.6Retail & E-commerce
- 12.7Media & Entertainment
- 12.8Manufacturing
- 12.9Others (Education, Energy & Utilities, etc.)
- 13Data center market – by end-user segment analysis
- 13.1Data Center Overview by End-user Segment
- 13.1.1Data Center Revenue Share By End-user
- 13.2Cloud Service Providers
- 13.3Enterprises
- 13.4Colocation Providers
- 13.5Government Agencies
- 13.6Others
- 14Data center market – by country segment analysis
- 14.1Data Center Overview by Country Segment
- 14.1.1Data Center Revenue Share By Country
- 14.2Spain
- 14.3Portugal
- 15Company profiles
- 15.1Equinix, Inc.
- 15.1.1Company Overview
- 15.1.2Product Portfolio
- 15.1.3Financial Overview
- 15.1.4Recent Developments
- 15.1.5Growth Strategy
- 15.1.6SWOT Analysis
- 15.2Digital Realty Trust, Inc.
- 15.3Global Switch
- 15.4DATA4 Group
- 15.5Iron Mountain Data Centers
- 15.6Edged Energy / Edged Data Centers
- 15.7MERLIN Properties
- 15.8Start Campus
- 15.9NOS Sistemas
- 15.10Others
About this report
Written by Priyanka Mor and reviewed by Deepti Agrawal, Senior Editor, Research. Figures are built top-down and bottom-up and reconciled before publication, with 2025 as the base year.
Read our methodologyHow we built this
- Historical periodUSD 8,163.61 Million in 2021
- Base year2025
- Forecast period2025-2035
- Sizing approachTop-down + bottom-up
Need more than the report?
Advisory on this market
Due diligence, site selection and market entry work, by the analysts who wrote this report.
See consulting servicesFrequently asked questions
The Iberia Data Center Market was valued at USD 11,530.26 million in 2025, based on the supplied market dataset.
The market is projected to reach USD 22,627.01 million by 2035, compared with USD 8,163.61 million in 2021.
The market covers Spain and Portugal, with major data center clusters in Madrid, Barcelona, Bilbao, Lisbon, Porto and Sines.
Enterprise data centers have the highest supplied CAGR at 5.2%, followed by hyperscale data centers at 4.6% and colocation at 3.5%.
Key factors include AI and cloud computing growth, colocation expansion, enterprise digital transformation, international connectivity, renewable energy availability and demand for high-density computing infrastructure.
Major companies include Equinix, Digital Realty, Global Switch, DATA4 Group, Iron Mountain Data Centers, Edged Energy, MERLIN Properties, Start Campus and NOS Sistemas, along with other regional and international operators.
Licences, delivery and payment
Which licence should I choose?
Single User is a view-only PDF for one person. Multi User adds a printable PDF and the Excel data for unlimited users at one location. Enterprise covers your whole company and includes 100 free analyst hours.
How and when will I receive the report?
By email, within 24–48 business hours of payment, in the formats of your licence.
How can I pay?
Securely through PayPal: with a PayPal account, a debit or credit card, or PayPal Pay Later where available. Prices are in US dollars.
Can I see a sample first?
Yes. Request a free sample and we will email it to you.
Can the report be tailored to my needs?
Yes. We can add countries, segments or data cuts. Talk to an analyst about the scope you need.
Can I get an invoice or pay against a purchase order?
Write to sales@dcmarketinsights.com and our team will help.