
Egypt Data Center Colocation Market Size, Share & Forecast to 2035
Market at a glance
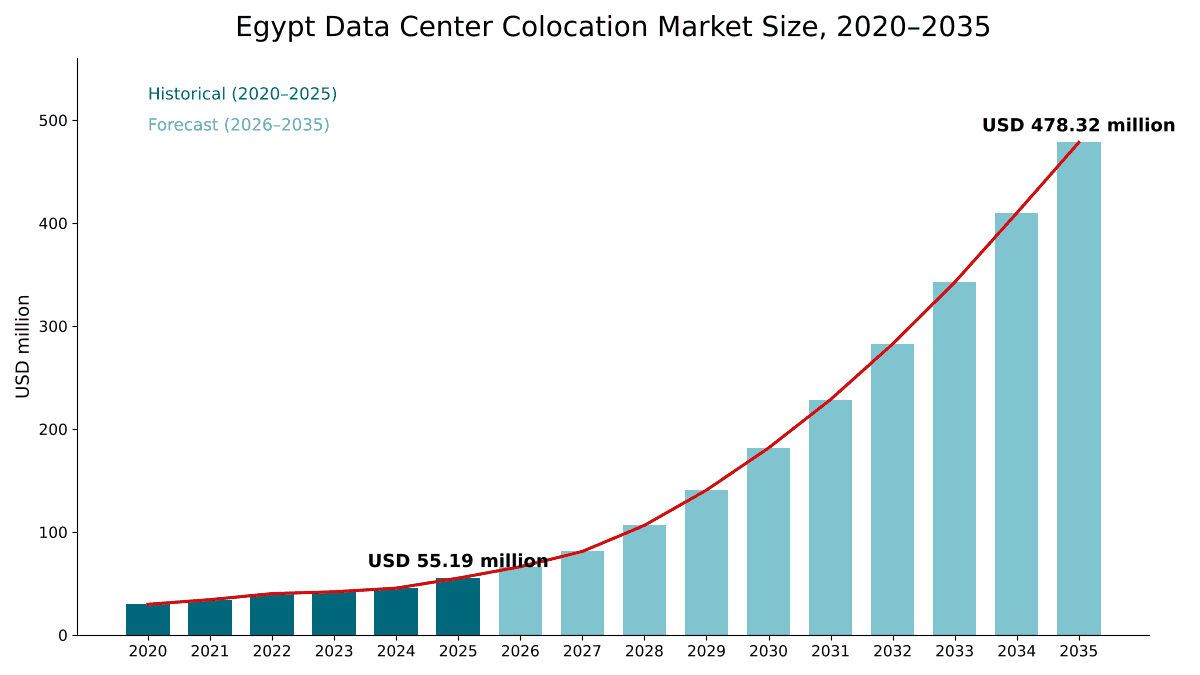
The Egypt Data Center Colocation market was worth USD 55.2 million in 2025 and is forecast to reach USD 478.3 million by 2035, growing at a 24.1% CAGR. Greater Cairo accounts for 85.2% of the market.
 By Amit Jain, Senior Consultant, ICT & Emerging Technologies
 Reviewed by Deepti Agrawal
Last updated 7 Oct 2026
Base year 2025 PDF + Excel
Source: DC Market Insights analysis
Key findings
Ten NTRA Licences in Two Years and More Than 600 MW of Announced Plans
Wholesale Halls for Cloud and AI Tenants Arrive
Currency Swings Cut US Dollar Revenue per kW by 18.4%
Wholesale Colocation Grows 36.70% a Year
What is inside the report
- 01Introduction
- 02Research Methodology
- 03Executive Summary
- 04Market Dynamics
- 05Pricing Analysis
- 06Standards and Regulation
- 07Supply Chain and Capacity
- 08Market Size and Forecast
- 09Market by Colocation Type
- 10Market by Revenue Stream
- 21chapters
- 2020-2024Historical period
- 2026-2035Forecast period
- 13Companies profiled
Regional insights
- Greater Cairo85.2%
- Alexandria and North Coast8.2%
- Suez Canal Economic Zone and Red Sea3.4%
- Rest of Egypt3.2%
Segmentation
Companies profiled
- Telecom Egypt
- GPX Global Systems
- Raya Data Center
- Vodafone Business
- Elsewedy Electric
- Cassava Technologies
- Khazna Data Centers
- Benya Group
- Gulf Data Hub
- Intro Group
- Hassan Allam Digital Infrastructure
- Africa50
- Huawei Cloud
Recent developments
SEA-ME-WE 6 completed its two Egyptian landings, at Port Said and Ras Ghareb (Source: Telecom Egypt press release).
Egypt issued the executive regulations of the Personal Data Protection Law as Ministerial Decree No. 816 of 2025 (Source: Al Tamimi legal briefing).
the NTRA licensed Hassan Allam's new digital arm to operate data centers and provide cloud computing services, with an initial USD 400 million investment (Source: Data Center Dynamics report).
Telecom Egypt decided not to sell a 75% to 80% stake in RDH to Helios Investments and will carve its data center services into a wholly owned subsidiary (Source: Telecom Egypt press release).
Vodafone Business, Elsewedy Electric and Cassava Technologies announced ADC Egypt, expected to launch with 20 MW within three years and scale to 200 MW, offering colocation, hosting and interconnection services (Source: Ahram Online report).
the communications minister reviewed Intro Group's plans for the 80 MW Kemet Data Centre in the SCZONE, with USD 270 million in the first phase (Source: Daily News Egypt report).
Full analysis
The Egypt Data Center Colocation Market covers the revenue that third-party data center operators in Egypt earn from renting space and power to customers, from interconnection and cross-connects, and from managed services sold with that space, across retail and wholesale colocation. DC Market Insights values the Egypt Data Center Colocation Market at USD 55.19 million in 2025 and forecasts USD 478.32 million by 2035, a CAGR of 24.10%. The 2025 value is built from capacity: about 14.40 MW of leased IT load on average during 2025, 10.94 MW of it retail at USD 305 per kW per month and 3.46 MW wholesale at USD 162 per kW per month, gives USD 46.77 million of space and power revenue, and interconnection and managed services add USD 8.42 million. Wholesale colocation is the fastest-growing segment at 36.70% a year as planned campuses of 20 MW to 300 MW come online and, in the DC Market Insights view, lease halls by the MW, and the Suez Canal Economic Zone and Red Sea is the fastest-growing region at 48.86% a year because the 80 MW Kemet campus is planned in the Integrated Sokhna Industrial Zone.
Executive Summary
The Egypt Data Center Colocation Market size was valued at USD 29.82 million in 2020, reached USD 55.19 million in 2025, and is anticipated to reach USD 478.32 million by 2035, at a CAGR of 24.10% during the forecast period.
| Report attribute | Details |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Egypt Data Center Colocation Market Size 2025 | USD 55.19 Million |
| Egypt Data Center Colocation Market, CAGR | 24.10% |
| Egypt Data Center Colocation Market Size 2035 | USD 478.32 Million |
Colocation revenue in Egypt grew 13.10% a year between 2020 and 2025 in the DC Market Insights model. By DC Market Insights estimates, growth slowed to 4.4% in 2023 and 8.4% in 2024 because contracts priced in Egyptian pounds lost value in US dollar terms: on 6 March 2024 the pound fell from a stabilised official rate of around 30.9 to a record low of 50.6 per US dollar, according to AFP. Revenue then rose 21.3% in 2025 in the model, a year in which Telecom Egypt expected to complete the second phase of its Regional Data Hub, with an estimated 4.6 MW of IT load.
In the DC Market Insights view, Egypt’s colocation base is still small. W.Media reported in January 2024 that Egypt operated 13 MW of live IT, alongside a pipeline able to increase that ten-fold. DC Market Insights counts about 20.5 MW of operational third-party colocation capacity at the end of 2025 and forecasts about 173 MW by 2035, as licensed campuses in Greater Cairo and the Suez Canal Economic Zone open in phases. Revenue growth peaks at 32.2% in 2029, when the first large wholesale halls are expected to fill.
Market Scope: What Does Colocation in Egypt Cover?
Colocation in Egypt is worth USD 55.19 million in 2025, by DC Market Insights estimates. The Egypt Data Center Colocation Market is the annual revenue earned by operators that rent data center space, power and connectivity in Egypt to other organizations, valued in current US dollars, with 2025 as the base year and forecasts to 2035.
Included. Retail colocation (racks, cages and private suites sold per rack or per kW), wholesale colocation (powered shells, data halls and build-to-suit capacity leased per MW), power fees billed with the space, interconnection (cross-connects, meet-me rooms, carrier and cloud on-ramps) and managed and other services sold with colocation (remote hands, monitoring, disaster recovery space and managed hosting delivered inside the colocation facility).
Excluded. Construction and equipment spending on data centers, which is covered by the Egypt Data Center Market report, public cloud and software-as-a-service revenue, GPU-as-a-Service compute revenue, enterprise-owned server rooms, subsea cable and landing station fees, and land sales.
How the segments fit together. The colocation type, revenue stream, end-user, enterprise size and tier splits each re-cut the same USD 55.19 million total, and the regional split allocates it across four Egyptian sub-markets.
Market Drivers: What Drives Colocation Demand in Egypt?
In the DC Market Insights view, three factors drive the Egypt Data Center Colocation Market: ten data centre licences issued by Egypt’s regulator in two years, a subsea cable position responsible for about 17% of global internet traffic, and 46% growth in Telecom Egypt’s data revenue in 2025.
Ten NTRA Licences in Two Years and More Than 600 MW of Announced Plans
Egypt’s National Telecommunications Regulatory Authority (NTRA) has issued ten data centre licences over the past two years, the most recent to Hassan Allam for a USD 400 million data centre project expected to host public and private sector clients. Africa Data Centres Egypt (ADC Egypt), formed by Vodafone Business, Elsewedy Electric and Cassava Technologies, is expected to launch with 20 MW within its first three years and scale to 200 MW, and its facilities will provide colocation, hosting, interconnection, cloud enablement, managed infrastructure and disaster-recovery services. Under a 2023 memorandum of understanding, Gulf Data Hub plans three complexes with Elsewedy Data Centers totalling 192 MW and expanding to 300 MW in 5-7 years for USD 2.1 billion, Intro Group’s Kemet Data Centre targets 80 MW, and Khazna Data Centers and Benya Group plan 25 MW in Maadi Technology Park, expandable to 50 MW, which adds up to more than 600 MW of announced plans by DC Market Insights count. DC Market Insights does not assume the whole pipeline is built: the model adds about 152 MW of colocation capacity between 2026 and 2035.
Fourteen Subsea Cable Systems Feed Cairo Interconnection
The Center for Strategic and International Studies (CSIS) counts 14 active cable systems in Egypt, with plans for more than 21 within three years, and estimates that Egypt is responsible for approximately 17% of global internet traffic. SEA-ME-WE 6, a 21,700 km system, completed two Egyptian landings in 2025, at Port Said on the Mediterranean and Ras Ghareb on the Red Sea. According to a 2023 Telecom Egypt release, its Regional Data Hub (RDH) at Smart Village hosted most local internet service providers (ISPs) and more than 22 international customers, including cloud and content providers, and its first phase reached full utilization in one year. Interconnection earns USD 4.91 million in 2025 in the DC Market Insights model, 8.9% of colocation revenue, and grows 25.49% a year.
Telecom Egypt’s Data Revenue Rose 46% in 2025
Telecom Egypt’s total revenue rose 31% to EGP 106.7 billion in 2025, with a 46% rise in data revenue, according to its full-year results. Egypt’s information and communications technology (ICT) sector grew 13.76% in real terms in fiscal year 2024/25, according to the Information and Decision Support Center (IDSC), and an official Ministry of Communications and Information Technology (MCIT) document reviewed by Asharq Bloomberg plans USD 500 million to USD 860 million a year for data centres, cloud and artificial intelligence (AI) infrastructure from fiscal year 2026/27. IT and telecom customers, including ISPs, carriers, cloud and content providers, account for USD 22.63 million of 2025 colocation revenue in the DC Market Insights model, 41.0% of the total.
Market Trends: How Is Colocation in Egypt Changing?
Colocation in Egypt is shifting from retail racks towards wholesale halls: DC Market Insights estimates the wholesale share of leased capacity rises from 24% in 2025 to 55% in 2035.
Wholesale Halls for Cloud and AI Tenants Arrive
In May 2024, W.Media reported that Huawei Cloud had launched its Cairo Region. In September 2026, Vodafone Business announced a separate partnership with Cassava Technologies, alongside ADC Egypt, to offer NVIDIA technologies and GPU-as-a-Service locally to businesses and government entities, and Huawei Cloud’s Cairo Region, the company’s 33rd cloud region, covers 28 African nations. Wholesale colocation earns USD 7.37 million in 2025, 13.4% of revenue, and USD 167.93 million by 2035, 35.1% of revenue, in the DC Market Insights model; in the DC Market Insights view, cloud regions and graphics processing unit (GPU) clusters are leased by the MW rather than by the rack.
Telecom Operators Separate Their Data Center Units
In July 2026 Telecom Egypt decided not to sell a 75% to 80% stake in its Regional Data Hub to Helios Investments, which had valued RDH at USD 230 million with a potential value of up to USD 260 million, and will instead carve its data center services into a wholly owned subsidiary. Data Center Dynamics reports that Telecom Egypt operates 11 data centers across seven Egyptian cities. In the DC Market Insights view, a stand-alone data center company is better placed to sign wholesale leases and raise project finance, and other Egyptian telecom and IT groups may follow the same route.
Capacity Moves Towards the Suez Canal and the Red Sea
Kemet Data Centre will be established in the Integrated Sokhna Industrial Zone, part of the Suez Canal Economic Zone (SCZONE), with first-phase investment of USD 270 million. The Suez Canal Economic Zone and Red Sea region holds 3.4% of 2025 colocation revenue and 21.0% in 2035 in the DC Market Insights model.
Market Challenges: What Holds Colocation in Egypt Back?
A pound that lost more than a third of its value in March 2024, renewable capacity behind target and slow conversion of memoranda into built halls are the main constraints DC Market Insights sees on the Egypt Data Center Colocation Market.
Currency Swings Cut US Dollar Revenue per kW by 18.4%
The DC Market Insights model assumes most domestic colocation contracts are priced in Egyptian pounds, so the fall of the pound from around 30.9 to 50.6 per US dollar in March 2024 reduced the dollar value of existing contracts. In the DC Market Insights model, the average retail price fell from USD 355 per kW per month in 2020 to USD 296 in 2024, a 16.6% decline, and space and power revenue per leased kW fell 18.4%, from about USD 329 to USD 268 per month, over the same period. In the model, international tenants that pay in US dollars soften the effect.
Renewable Capacity Trails the 2030 Goal
Egypt aims to generate 42% of its electricity from renewable sources by 2030, and 7,750 MW of renewable capacity was installed by the end of 2024, according to the US International Trade Administration (ITA). In the DC Market Insights view, cloud and AI tenants weigh access to renewable power when they choose where to lease, so delays in wind and solar projects can delay wholesale colocation demand.
Memoranda Run Far Ahead of Built Capacity
UAE and Egyptian ministries signed a memorandum in December 2023 that could lead to 1 GW of data center capacity, with a first phase of 100 MW. Against that, Egypt operated 13 MW of live IT at the start of 2024, and DC Market Insights counts about 20.5 MW of operational colocation capacity at the end of 2025. The model completes about 52 MW of colocation capacity between 2026 and 2030 because tenants and power, not announcements, set the pace.
Market Opportunities: Where Are the New Revenue Pools in Colocation in Egypt?
Wholesale colocation, growing 36.70% a year, and interconnection in Greater Cairo, worth most of the USD 4.91 million interconnection pool in 2025, are the largest new revenue pools in the Egypt Data Center Colocation Market.
Wholesale Colocation Grows 36.70% a Year
A single new campus can add more capacity than the 13 MW of live IT Egypt operated at the start of 2024: Khazna’s Maadi campus plans 25 MW at first, and ADC Egypt 20 MW in its first three years. Wholesale colocation rises from USD 7.37 million in 2025 to USD 167.93 million by 2035 in the DC Market Insights model, the fastest rate of any segment.
Retail Colocation and Interconnection in Greater Cairo Keep the Lead
GPX Global Systems announced in 2023 an EGP 2.7 billion expansion of its Cairo 2 data center adding 12 MW of power, 1,800 racks and 9,000 m² of space, with phase one targeted to be customer-ready in late Q3 2026. Raya Data Center, in which Africa50 agreed to take a 42.9% stake for a USD 15 million equity investment, operates two data centers in Cairo and is developing a greenfield Tier III-quality data center. Retail colocation in Greater Cairo is worth USD 41.18 million in 2025 in the DC Market Insights matrix, 74.6% of all colocation revenue in Egypt.
Pricing: How Much Does Colocation Cost in Egypt?
Retail colocation in Egypt costs about USD 305 per kW of IT load per month in 2025, and wholesale colocation about USD 162 per kW per month, by DC Market Insights estimates; both prices include power. On a typical 5 kW rack, the retail price is about USD 1,525 per month.
| Price per kW per month (USD) | 2020 | 2025 | 2030 | 2035 |
|---|---|---|---|---|
| Retail colocation | 355.00 | 305.00 | 338.40 | 375.46 |
| Wholesale colocation | 182.00 | 162.00 | 171.95 | 182.51 |
| Wholesale share of leased capacity | 15% | 24% | 44% | 55% |
| Average utilization of operational capacity | 80% | 80% | 74% | 78% |
The blended revenue per leased kW, including interconnection and services, is about USD 319 per month in 2025. Retail prices rise 2.1% a year from 2026 and wholesale prices 1.2% a year in the model, so the blended price falls as wholesale gains share. As a cross-check, Helios’s USD 230 million valuation of RDH equals about 8.85 times the USD 25.99 million a year that RDH’s 7.1 MW of IT load would earn fully leased at the 2025 retail price, a DC Market Insights calculation.
Standards and Regulation: Which Rules Shape Colocation in Egypt?
Four sets of rules shape colocation in Egypt: NTRA licensing, the Personal Data Protection Law, tier and rating certification and the national renewable energy target.
NTRA licensing. The NTRA approved a regulatory framework to establish data centers and provide cloud computing services in August 2021. The US ITA describes the framework for Public Data Center Providers (PDCP) as offering 15-year licences that allow direct submarine cable connectivity without case-by-case approvals.
Personal Data Protection Law. Law No. 151 of 2020 is implemented through executive regulations issued as Ministerial Decree No. 816 of 2025 on 1 November 2025. Controllers and processors must notify the regulator within 72 hours of becoming aware of a personal data breach, and processing of personal data outside Egypt needs a licence and is allowed only to jurisdictions with an adequate level of protection, which, in the DC Market Insights view, favors hosting personal data in Egyptian colocation sites.
Tier and rating certification. Telecom Egypt’s RDH 2 was awarded Tier III design certification, the Administrative Capital for Urban Development (ACUD) data center holds Tier III certifications for design documents and constructed facility, Kemet aims to be the first project in the SCZONE to achieve Tier III classification, Gulf Data Hub targets Uptime Tier III and LEED for each facility, and GPX describes its Cairo site as a Rated-4 certified purpose-built facility.
Renewable energy target. Egypt aims to generate 42% of its electricity from renewable sources by 2030; in the DC Market Insights view, that target sets the green power that wholesale tenants can contract.
Market Segmentation: Which Segment Leads the Egypt Data Center Colocation Market?
Retail colocation leads the Egypt Data Center Colocation Market with 86.6% of 2025 revenue, space and power lead revenue streams with 84.7%, and Tier III facilities lead with 68.0%. Wholesale colocation is the fastest-growing segment at 36.70% a year, against 20.57% for retail, because the model assumes the new campuses are leased in MW blocks.
By Colocation Type: Retail Leads with 86.6%
| Colocation type | 2025 (USD million) | Share 2025 | 2035 (USD million) | CAGR 2025-2035 |
|---|---|---|---|---|
| Retail Colocation | 47.82 | 86.6% | 310.39 | 20.57% |
| Wholesale Colocation | 7.37 | 13.4% | 167.93 | 36.70% |
Retail colocation keeps 64.9% of revenue in 2035 in the model, which assumes banks, government bodies and ISPs keep buying racks and cages rather than whole halls.
By Revenue Stream: Space and Power Leads with 84.7%
| Revenue stream | 2025 (USD million) | Share 2025 | 2035 (USD million) | CAGR 2025-2035 |
|---|---|---|---|---|
| Space and Power | 46.77 | 84.7% | 406.39 | 24.14% |
| Interconnection | 4.91 | 8.9% | 47.55 | 25.49% |
| Managed and Other Services | 3.51 | 6.4% | 24.38 | 21.39% |
Interconnection grows fastest among revenue streams in the model, which assumes more carriers and clouds meet in Cairo facilities as new cable systems land.
By End User: IT and Telecom Leads with 41.0%
| End user | 2025 (USD million) | Share 2025 | 2035 (USD million) | CAGR 2025-2035 |
|---|---|---|---|---|
| IT and Telecom | 22.63 | 41.0% | 227.20 | 25.94% |
| BFSI | 11.87 | 21.5% | 76.53 | 20.49% |
| Government and Defense | 7.17 | 13.0% | 57.40 | 23.12% |
| Energy and Utilities | 2.81 | 5.1% | 21.05 | 22.31% |
| Healthcare | 2.32 | 4.2% | 22.00 | 25.23% |
| Others | 8.39 | 15.2% | 74.14 | 24.35% |
Banking, financial services and insurance (BFSI) customers spend USD 11.87 million on colocation in 2025 and grow more slowly, at 20.49% a year, because, in the DC Market Insights view, large banks keep primary systems in their own data centers and use colocation mainly for disaster recovery.
By Enterprise Size: Large Enterprises Lead with 74.0%
Large enterprises, including carriers, cloud providers, banks and government bodies, spend USD 40.84 million on colocation in 2025 and USD 389.83 million by 2035, a CAGR of 25.31%. Small and medium enterprises (SMEs) spend USD 14.35 million in 2025, 26.0% of revenue, and grow 19.95% a year in the model as more of them choose public cloud instead of racks.
By Tier Standard: Tier III Leads with 68.0%
Tier III facilities earn USD 37.53 million in 2025 and USD 344.39 million by 2035, a CAGR of 24.82%. Tier IV facilities earn USD 5.24 million (9.5%) and grow fastest at 28.07% a year, while Tier I and II facilities earn USD 12.42 million (22.5%) and grow 19.17% a year, as the model assumes older telecom sites are upgraded or retired.
DC Exclusive: The Egypt Colocation Revenue and Leased-MW Matrix
At USD 41.18 million in 2025, retail colocation in Greater Cairo is the largest cell of the matrix and 74.6% of all colocation revenue in Egypt, earned on about 9.43 MW of leased IT load.
| 2025 | Retail revenue (USD million) | Retail leased MW | Wholesale revenue (USD million) | Wholesale leased MW | Total revenue (USD million) |
|---|---|---|---|---|---|
| Greater Cairo | 41.18 | 9.43 | 5.83 | 2.74 | 47.01 |
| Alexandria and North Coast | 3.99 | 0.91 | 0.54 | 0.25 | 4.53 |
| Suez Canal Economic Zone and Red Sea | 1.02 | 0.23 | 0.86 | 0.40 | 1.88 |
| Rest of Egypt | 1.63 | 0.37 | 0.14 | 0.07 | 1.77 |
| Total | 47.82 | 10.94 | 7.37 | 3.46 | 55.19 |
Greater Cairo earns 87.6% of its colocation revenue from retail racks and cages in the model, reflecting ISPs, banks and government users that buy small footprints. The Suez Canal Economic Zone and Red Sea already earns 45.7% of its revenue from wholesale leases, the highest share of any region, because new capacity there is planned as large campuses, led by the 80 MW Kemet Data Centre.
The matrix is a DC Market Insights model, not an operator survey. It is built from 170 inputs: 17 operational capacity points, 16 years each of utilization, retail price, wholesale price, wholesale share, interconnection ratio and managed services ratio, 32 regional and type weights, 12 end-user weights, 4 enterprise size weights, 6 tier weights and 3 regional wholesale ratios. The method is explained on our research methodology page.
Regional Insights: Where Are the Data Centers in Egypt?
Greater Cairo leads with 85.2% of 2025 colocation revenue, and Data Center Map lists 14 data centers from 5 markets in Egypt, 10 of them in Cairo. In the Egypt Data Center Colocation Market, the Suez Canal Economic Zone and Red Sea is the fastest-growing region at 48.86% a year because large new campuses such as Kemet are planned on industrial land there.
Greater Cairo Leads with 85.2% Share
Greater Cairo, including Smart Village, Maadi Technology Park and the New Administrative Capital, earns USD 47.01 million in 2025 and USD 291.77 million by 2035, a CAGR of 20.03%. Telecom Egypt’s RDH, GPX’s Cairo 2 site, Raya Data Center’s two facilities and the planned Khazna and Benya campus are all in Greater Cairo.
Alexandria and North Coast Holds 8.2% Share
Alexandria and the North Coast earn USD 4.53 million in 2025 and USD 52.62 million by 2035, a CAGR of 27.79%. Telecom Egypt operated commercial data center facilities in Greater Cairo and Alexandria in 2020, and Alexandria is the main disaster recovery location for Cairo-based customers in the DC Market Insights view.
Suez Canal Economic Zone and Red Sea Holds 3.4% Share
The Suez Canal Economic Zone and Red Sea, covering Ain Sokhna, Port Said and Ras Ghareb, earns USD 1.88 million in 2025 and USD 100.45 million by 2035, a CAGR of 48.86%, rising to 21.0% of the market as Kemet and other SCZONE campuses open.
Rest of Egypt Holds 3.2% Share
The rest of Egypt, including the Nile Delta, Upper Egypt and Sinai, earns USD 1.77 million in 2025 and USD 33.48 million by 2035, a CAGR of 34.18%, mainly from regional telecom sites and disaster recovery space in the DC Market Insights model.
Forecast Scenarios: How Could the 2035 Forecast Change?
The Egypt Data Center Colocation Market reaches USD 478.32 million by 2035 in the base case, with a range of USD 335.42 million to USD 584.29 million across the low and high scenarios.
| Scenario | Assumption from 2026 | 2035 (USD million) | CAGR 2025-2035 |
|---|---|---|---|
| Low | Capacity additions 30% below base; prices 5% lower | 335.42 | 19.78% |
| Base | Operational capacity reaches about 173 MW by 2035; wholesale reaches 55% of leased capacity | 478.32 | 24.10% |
| High | Capacity additions 20% above base; prices 4% higher | 584.29 | 26.61% |
In the DC Market Insights scenarios, the low case reflects delayed foreign funding and a further currency fall, and the high case assumes ADC Egypt, Kemet and the Khazna campus keep their announced schedules.
Competitive Insights: Which Data Center Companies in Egypt Lead Colocation?
- Telecom Egypt
- GPX Global Systems
- Raya Data Center
- Vodafone Business
- Elsewedy Electric
- Cassava Technologies
- Khazna Data Centers
- Benya Group
- Gulf Data Hub
- Intro Group
- Hassan Allam Digital Infrastructure
- Africa50
- Huawei Cloud
Telecom Egypt leads the Egypt Data Center Colocation Market with about 41% of 2025 revenue, and the top three operators, Telecom Egypt, GPX Global Systems and Raya Data Center, hold about 64%, by DC Market Insights estimates based on their announced capacity and the RDH customer base. According to a 2023 Telecom Egypt release, RDH will reach up to 7.1 MW of IT load after its second phase and up to 16.3 MW across all phases, and Telecom Egypt runs 11 data centers across seven cities. The next wave of competition comes from ADC Egypt, Khazna and Benya, Gulf Data Hub and Kemet, which together have announced plans for more than 600 MW by DC Market Insights count, and from Hassan Allam Digital Infrastructure, licensed in June 2026.
Recent Developments
- In July 2025, SEA-ME-WE 6 completed its two Egyptian landings, at Port Said and Ras Ghareb (Source: Telecom Egypt press release).
- In November 2025, Egypt issued the executive regulations of the Personal Data Protection Law as Ministerial Decree No. 816 of 2025 (Source: Al Tamimi legal briefing).
- In June 2026, the NTRA licensed Hassan Allam’s new digital arm to operate data centers and provide cloud computing services, with an initial USD 400 million investment (Source: Data Center Dynamics report).
- In July 2026, Telecom Egypt decided not to sell a 75% to 80% stake in RDH to Helios Investments and will carve its data center services into a wholly owned subsidiary (Source: Telecom Egypt press release).
- In September 2026, Vodafone Business, Elsewedy Electric and Cassava Technologies announced ADC Egypt, expected to launch with 20 MW within three years and scale to 200 MW, offering colocation, hosting and interconnection services (Source: Ahram Online report).
- In September 2026, the communications minister reviewed Intro Group’s plans for the 80 MW Kemet Data Centre in the SCZONE, with USD 270 million in the first phase (Source: Daily News Egypt report).
We follow these licences, launches and financings as they happen in our data center industry updates. Related reports: Egypt Data Center Market and Egypt Data Center Infrastructure Market.
Methodology: How We Built the Egypt Data Center Colocation Market Model
DC Market Insights built the Egypt Data Center Colocation Market bottom-up from operational third-party colocation capacity at the end of each year from 2019 to 2035, starting at 7.5 MW in 2019 and reaching 20.5 MW at the end of 2025 and about 173 MW at the end of 2035. Average capacity in each year is multiplied by utilization (80% in 2025) to give leased IT load, which is split into retail and wholesale (24% wholesale in 2025, 55% in 2035) and priced per kW per month (USD 305 retail and USD 162 wholesale in 2025). Interconnection adds 10.5% and managed services 7.5% of space and power revenue in 2025. The total was split by 2 colocation types, 3 revenue streams, 6 end-user groups, 2 enterprise sizes, 3 tier groups and 4 regions, and every split sums to the market total. The result was checked top-down against the 13 MW of live IT reported for Egypt in January 2024, the 7.1 MW of IT load at RDH after its second phase and Helios’s USD 230 million valuation of RDH, and against the Egypt Data Center Market model, whose 2025 spending on colocation facilities of USD 120.12 million is about 2.2 times colocation revenue, consistent with a market still building ahead of demand.
Table of contents
- 01Introduction
- 1.1Market Definition and Scope
- 1.2Retail and Wholesale Colocation Defined
- 1.3Report Coverage and Currency
- 1.4Key Stakeholders
- 02Research Methodology
- 2.1Capacity-Based Revenue Model
- 2.2Price per kW Assumptions
- 2.3Data Sources and Fact Verification
- 2.4Top-Down Cross-Checks
- 03Executive Summary
- 3.1Market Snapshot, 2025 and 2035
- 3.2Key Findings
- 3.3Analyst View
- 04Market Dynamics
- 4.1Market Drivers
- 4.2Market Trends
- 4.3Market Challenges
- 4.4Market Opportunities
- 05Pricing Analysis
- 5.1Retail Colocation Price per kW, 2020-2035
- 5.2Wholesale Colocation Price per kW, 2020-2035
- 5.3Currency Effects on US Dollar Revenue
- 5.4Revenue per Leased kW
- 06Standards and Regulation
- 6.1NTRA Data Center Licensing
- 6.2Personal Data Protection Law No. 151 of 2020
- 6.3Tier and Rating Certification
- 6.4Renewable Energy Targets
- 07Supply Chain and Capacity
- 7.1Operational Colocation Capacity, 2019-2035
- 7.2Leased Capacity and Utilization
- 7.3Announced Campus Pipeline
- 7.4Subsea Cable Landings and Interconnection
- 08Market Size and Forecast
- 8.1Market Size, 2020-2035
- 8.2Annual Growth Rates
- 8.3Leased MW, 2020-2035
- 09Market by Colocation Type
- 9.1Retail Colocation
- 9.2Wholesale Colocation
- 10Market by Revenue Stream
- 10.1Space and Power
- 10.2Interconnection
- 10.3Managed and Other Services
- 11Market by End User
- 11.1IT and Telecom
- 11.2BFSI
- 11.3Government and Defense
- 11.4Energy and Utilities
- 11.5Healthcare
- 11.6Others
- 12Market by Enterprise Size
- 12.1Large Enterprises
- 12.2Small and Medium Enterprises
- 13Market by Tier Standard
- 13.1Tier III
- 13.2Tier IV
- 13.3Tier I and II
- 14DC Exclusive: Egypt Colocation Revenue and Leased-MW Matrix
- 14.1Revenue by Region and Colocation Type, 2025
- 14.2Leased MW by Region and Colocation Type, 2025
- 14.3Matrix Inputs
- 15Market by Region
- 15.1Greater Cairo (Smart Village, Maadi, New Administrative Capital)
- 15.2Alexandria and North Coast
- 15.3Suez Canal Economic Zone and Red Sea (Ain Sokhna, Port Said, Ras Ghareb)
- 15.4Rest of Egypt (Nile Delta, Upper Egypt, Sinai)
- 16Regional Cross-Sections
- 16.1Colocation Type by Region
- 16.2Regional Shares, 2025 and 2035
- 17Forecast Scenarios
- 17.1Low Scenario
- 17.2Base Scenario
- 17.3High Scenario
- 18Competitive Landscape
- 18.1Market Share Estimates, 2025
- 18.2Announced Capacity by Operator
- 18.3Recent Developments
- 19Company Profiles
- 19.1Telecom Egypt
- 19.2GPX Global Systems
- 19.3Raya Data Center
- 19.4Vodafone Business
- 19.5Elsewedy Electric
- 19.6Cassava Technologies
- 19.7Khazna Data Centers
- 19.8Benya Group
- 19.9Gulf Data Hub
- 19.10Intro Group
- 19.11Hassan Allam Digital Infrastructure
- 19.12Africa50
- 19.13Huawei Cloud
- 20Customer Insights
- 20.1Buying Criteria of Retail Customers
- 20.2Wholesale Lease Terms
- 21Analyst Recommendations
- 21.1For Colocation Operators
- 21.2For Enterprise and Government Buyers
- 21.3For Investors
- Fig. 1Egypt Data Center Colocation Market Size, 2020-2035
- Fig. 2Operational and Leased Colocation Capacity, 2019-2035
- Fig. 3Retail and Wholesale Price per kW per Month, 2020-2035
- Fig. 4Market Share by Colocation Type, 2025 and 2035
- Fig. 5Market Share by Revenue Stream, 2025 and 2035
- Fig. 6Market Share by End User, 2025 and 2035
- Fig. 7Market Share by Region, 2025 and 2035
- Fig. 8Forecast Scenarios, 2035
- Table 1Report Attributes
- Table 2Price per kW per Month, 2020, 2025, 2030 and 2035
- Table 3Market by Colocation Type, 2025 and 2035
- Table 4Market by Revenue Stream, 2025 and 2035
- Table 5Market by End User, 2025 and 2035
- Table 6Market by Enterprise Size, 2025 and 2035
- Table 7Market by Tier Standard, 2025 and 2035
- Table 8DC Exclusive Revenue and Leased-MW Matrix, 2025
- Table 9Market by Region, 2025 and 2035
- Table 10Forecast Scenarios, 2035
- Table 11Announced Colocation Campus Pipeline
About this report
Written by Amit Jain and reviewed by Deepti Agrawal, Senior Editor, Research. Figures are built top-down and bottom-up and reconciled before publication, with 2025 as the base year.
Read our methodologyHow we built this
- Historical period2020-2024
- Base year2025
- Forecast period2026-2035
- Sizing approachTop-down + bottom-up
Need more than the report?
Advisory on this market
Due diligence, site selection and market entry work, by the analysts who wrote this report.
See consulting servicesFrequently asked questions
USD 55.19 million in 2025, by DC Market Insights estimates, rising to USD 478.32 million by 2035 at a CAGR of 24.10%. The value covers space and power, interconnection and managed services sold by colocation operators in Egypt.
About USD 305 per kW of IT load per month for retail colocation and USD 162 per kW per month for wholesale colocation in 2025, by DC Market Insights estimates, with power included. A typical 5 kW rack costs about USD 1,525 per month.
14 data centers from 5 markets are listed by Data Center Map, 10 of them in Cairo. DC Market Insights counts about 20.5 MW of operational third-party colocation capacity in Egypt at the end of 2025.
About 41% of 2025 colocation revenue goes to Telecom Egypt, by DC Market Insights estimates, and the top three, Telecom Egypt, GPX Global Systems and Raya Data Center, hold about 64%. ADC Egypt, Khazna and Benya, Gulf Data Hub and Intro Group plan new campuses.
36.70% a year is the growth rate of wholesale colocation from 2025 to 2035, the fastest of any segment, against 20.57% for retail. Wholesale rises from USD 7.37 million in 2025 to USD 167.93 million by 2035.
85.2% of 2025 colocation revenue comes from Greater Cairo, worth USD 47.01 million. The Suez Canal Economic Zone and Red Sea grows fastest, at 48.86% a year, as the 80 MW Kemet Data Centre is planned in the Integrated Sokhna Industrial Zone.
Ten data centre licences issued by the NTRA in two years, 14 active subsea cable systems counted by CSIS and a 46% rise in Telecom Egypt’s data revenue in 2025 drive demand. Interconnection earns USD 4.91 million in 2025 and grows 25.49% a year.
USD 335.42 million to USD 584.29 million is the 2035 range across the low and high scenarios, around a base case of USD 478.32 million. The low case assumes 30% fewer capacity additions and 5% lower prices.
Get this report
How do I get the full report?
Request a quote; we reply by email within one business day.
How and when will I receive the report?
By email, within 24–48 business hours of payment.
How can I pay?
Once you accept the quote, we email you a secure payment link.
Can I see a sample first?
Yes. Request a free sample and we will email it to you.
Can the report be tailored to my needs?
Yes. We can add countries, segments or data cuts. Talk to an analyst about the scope you need.
Can I get an invoice or pay against a purchase order?
Write to sales@dcmarketinsights.com and our team will help.