
Mexico AI Data Center Market Size, Share & Forecast to 2035
Market at a glance
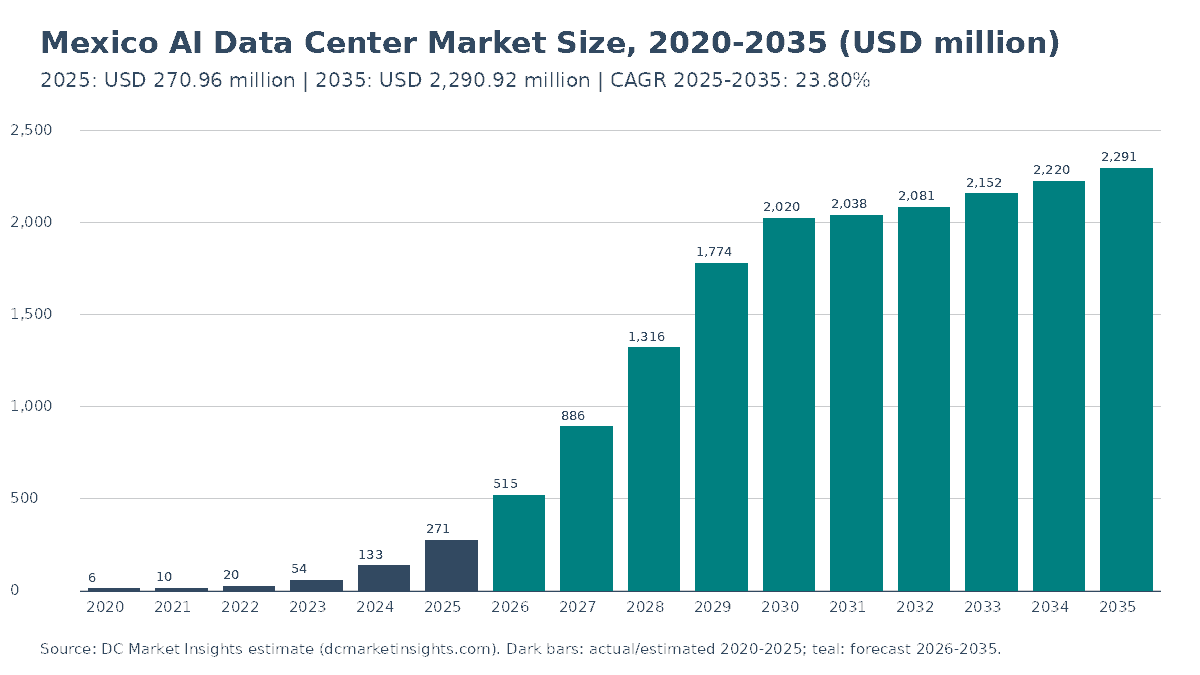
The Mexico AI Data Center market was worth USD 271.0 million in 2025 and is forecast to reach USD 2,290.0 million by 2035, growing at a 23.8% CAGR.
 By Amit Jain, Senior Consultant, ICT & Emerging Technologies
 Reviewed by Deepti Agrawal
Last updated 19 Oct 2026
Base year 2025 PDF + Excel
Key findings
CFE transmission in the Bajío lags campus plans
What is inside the report
- 01Introduction
- 02Research Methodology
- 03Executive Summary
- 04Market Dynamics
- 05Pricing Analysis
- 06Standards and Regulation
- 07Market Segmentation
- 08DC Exclusive: Mexico AI Campus Power Tracker
- 09Regional Insights
- 10State Analysis
- 13chapters
- 2020-2024Historical period
- 2026-2035Forecast period
- —Companies profiled
Segmentation
Full analysis
The Mexico AI Data Center Market is valued at USD 515.23 million in 2026 and is projected to reach USD 2.29 billion by 2035, up from USD 270.96 million in 2025, a CAGR of 23.80% from 2025 to 2035 (DC Market Insights estimate). How fast that money is spent depends on substations in Querétaro: the Federal Electricity Commission (CFE) energised only 26.8 MW for Amazon Web Services (AWS), Abbott and ODATA in January 2026, and in September 2026 CFE and the Mexican Data Center Association (MEXDC) agreed to review 1,705 MW of pending data center demand project by project (Source: CFE and MEXDC). Querétaro alone holds 72% of national data center operations, according to the state’s Secretariat of Sustainable Development (SEDESU), so every substation that CFE finishes in the Bajío decides how fast AI halls can open. The Mexico AI Data Center Market covers the facility infrastructure built and run for artificial intelligence (AI) workloads in Mexico: electrical systems, cooling, the building shell, fit-out and racks, the AI network fabric, and operations services and software; graphics processing unit (GPU) servers are excluded. The 2025 build receipt is 50% of 18.2 MW of new AI IT capacity completed in 2025 × USD 10.00 million per AI MW (USD 91.00 million) plus 50% of 34.2 MW due in 2026 × USD 10.20 million (USD 174.42 million), plus USD 0.40 million of services on each of 13.85 MW of installed AI capacity (USD 5.54 million). Operations Services and Software is the fastest-growing segment at 58.50% a year as the installed AI base climbs from 32 MW to 1,241 MW, and the North-Central and Northwest region is the fastest-growing region at 48.09% a year because the 250 MW Fermaca Digital City campus in Durango sits outside the congested Bajío grid.
Key Market Statistics: How Big Is the Mexico AI Data Center Market in 2026?
DC Market Insights values the Mexico AI Data Center Market at USD 515.23 million in 2026, 90.15% above 2025. The jump comes as new AI IT capacity nearly doubles from 18.2 MW to 34.2 MW.
- Market size 2025: USD 270.96 million (USD 271.0 million rounded)
- Market size 2026: USD 515.23 million
- Market size 2030: USD 2.02 billion
- Market size 2035: USD 2.29 billion
- CAGR 2025-2035: 23.80% (low case 18.87%, high case 26.52%)
- Largest component: Electrical Infrastructure, 35.26% of 2025 spend (USD 95.55 million)
- Fastest component: Operations Services and Software, 58.50% a year; fastest workload: AI Inference, 28.92% a year
- Leading region: Bajío (Querétaro and Guanajuato), 72% of 2025 spend; fastest-growing region: North-Central and Northwest, 48.09% a year
- Largest state: Querétaro, USD 178.83 million in 2025
- Market leader: Schneider Electric, about 13% of 2025 equipment and services value (DC Market Insights estimate)
Key Takeaways: What Do Querétaro’s Grid Queue and 100 kW Racks Mean for Mexico AI Data Center Buyers?
DC Market Insights draws four takeaways for buyers in the Mexico AI Data Center Market, which grows from USD 270.96 million in 2025 to USD 2.29 billion in 2035.
- Querétaro falls from 66% to 50% of spend by 2035 because CFE plans only 800 MW of new transmission there.
- An AI megawatt costs about USD 10.00 million before servers because 100 kW racks need liquid cooling loops.
- AI Inference reaches 60% of 2035 spend because Mexican banks, retailers and agencies run models rather than train them.
- Operations Services and Software grows 58.50% a year because the installed AI base rises from 32 MW to 1,241 MW.
Mexico AI Data Center Market Summary: What Did AI-Ready Halls in Mexico Cost Buyers in 2025?
The Mexico AI Data Center Market size was valued at USD 5.88 million in 2020, reached USD 270.96 million in 2025, and is anticipated to reach USD 2.29 billion by 2035, at a CAGR of 23.80% during the forecast period. DC Market Insights estimates that Mexico spent USD 270.96 million on AI data center facilities in 2025, up from USD 132.91 million in 2024.
| Report attribute | Details |
|---|---|
| Historical period | 2020-2024 |
| Base year | 2025 |
| Forecast period | 2026-2035 |
| Market size 2025 | USD 270.96 million |
| Market size 2026 | USD 515.23 million |
| CAGR 2025-2035 | 23.80% |
| Market size 2035 | USD 2.29 billion |
| Segments covered | Component, Workload, Data Center Type |
| Regions covered | Bajío, Valley of Mexico, Northeast, North-Central and Northwest, West and South; 12 states |
Growth runs at 90.15% in 2026 and 71.95% in 2027, then slows to 3.18% by 2035 because annual completions peak at 300 MW in 2030 and settle near 230 MW, while the AI share of new capacity rises only from 57% to 62%. Mexico’s installed data center IT load climbs from 220 MW at the end of 2025 to 1,175 MW in 2030 and 2,351 MW in 2035 in the DC Market Insights model; the AI part of it rises from 32 MW to 1,241 MW. The AI facility spend modelled here is a slice of the Mexico Data Center Market, which also counts conventional IT and non-AI halls.
What Counts as a Mexico AI Data Center, and What Is Left Out?
The Mexico AI Data Center Market is USD 270.96 million of facility spend in 2025 on halls that host AI training and inference clusters, plus the services that keep them running.
Included
Medium-voltage substations on campus, switchgear, uninterruptible power supply (UPS) systems, busway and rack power distribution; chillers, dry coolers, coolant distribution units (CDUs), rear-door heat exchangers and direct-to-chip liquid loops; the building shell, raised or slab floors, containment and racks rated above 30 kW; the AI network fabric (spine-leaf cabling, optical trunks and in-hall switching enclosures); and operations, monitoring and lifecycle services for AI halls. The Mexico Data Center Cooling Market sizes the cooling layer for all halls in Mexico, AI and conventional.
Excluded
GPU servers, accelerators and storage, land, grid electricity bills, CFE transmission works paid by the utility, colocation rent, cloud AI service revenue and AI software. Data science platforms, AI data management software (searched as the Mexico AI data management market) and other analytics software sit outside the scope: they run on top of the halls and are not facility spend.
How the segments fit together
Every component, workload and data center type split sums to USD 270.96 million in 2025 and USD 2.29 billion in 2035. Capital spend is 97.96% of 2025 value and operations services 2.04%; by 2035 services reach 24.21% as the installed AI base passes 1,200 MW.
Why Do Mexico AI Data Center Market Estimates Differ?
Estimates differ because the Mexico AI Data Center Market is USD 515.23 million in 2026 only when it is measured as facility spend; counting the servers inside the halls multiplies it several times.
Broader definitions add GPU servers (about USD 25-35 million of accelerated IT per AI MW), cloud AI service revenue, colocation rent, electricity, and AI software such as data science platforms. The previous edition of this page counted hardware, software and services together and reached USD 582.42 million in 2025 with a 17.50% CAGR. The scope used here stops at the building and its power, cooling and network, so it can be checked against megawatts that CFE energises and that operators report.
| Element | In scope here | Why |
|---|---|---|
| Power, cooling, shell, racks, AI fabric | Yes, USD 265.42 million in 2025 | Facility capital spend per AI MW |
| Operations services and software | Yes, USD 5.54 million in 2025 | Runs on the installed AI base |
| GPU servers and storage | No | IT equipment, sized per server |
| Colocation rent and cloud AI revenue | No | Revenue, not spend on facilities |
| Electricity and CFE grid works | No | Operating cost and utility capital |
The in-scope buyers are hyperscale cloud providers, wholesale colocation developers, the federal government and universities, and enterprises, including small and medium-sized enterprises (SMEs) that rent AI racks in colocation halls.
Why Are Hyperscalers and Campus Developers Pouring Money Into Mexico AI Data Centers?
Mexico AI Data Center spending rises 90.15% in 2026 because three groups of buyers commit capital at once: hyperscale clouds, wholesale campus developers in Querétaro and public compute programmes.
AWS, Microsoft, Google and Oracle cloud regions anchor demand in Querétaro
Four hyperscale clouds now run Mexican regions. Microsoft started its Mexico Central region in May 2024 and announced a USD 1.3 billion cloud and AI pledge over three years in September 2024; Google opened its 41st region in Querétaro in December 2024 (Google Cloud Querétaro region); AWS launched its Mexico (Central) Region with three Availability Zones in January 2025 and committed more than USD 5 billion over 15 years (AWS Mexico (Central) Region launch); Oracle runs regions in Querétaro and Monterrey, the second inside the Telmex-Triara data center (Source: Oracle). DC Market Insights counts Hyperscale and Cloud Self-Build at USD 130.06 million in 2025, 48% of the market.
Wholesale AI campuses: ODATA QR03, CloudHQ and KIO QRO3
ODATA energised its QR03 campus in Querétaro in February 2026, a project of more than USD 3 billion for up to 300 MW of IT with a 72 MW first building, according to ODATA. CloudHQ raised its Querétaro campus to nearly USD 6 billion and about 1,000 MW of power capacity in October 2026, up from USD 4.8 billion for six buildings and 900 MW announced at the presidential press conference in September 2025 (Source: CloudHQ). KIO Data Centers plans more than USD 200 million of spend in Mexico in 2026 and a potential USD 1.3 billion, about 100 MW, for its QRO3 expansion to 2030, according to KIO. Wholesale Colocation AI Campuses carry USD 108.38 million in 2025 and grow 24.40% a year.
Public compute: the Coatlicue supercomputer and state AI centers
The federal Agencia de Transformación Digital announced in November 2025 the Coatlicue public supercomputer: 6 billion Mexican pesos (MXN), 314 petaflops and about 14,480 GPUs in roughly 200 liquid-cooled cabinets, with a build of about 24 months from January 2026 (Source: Agencia de Transformación Digital). The Nuevo León government announced a USD 1 billion high-performance computing (HPC) and AI center in November 2025, although NVIDIA Corporation (NVIDIA) said it had no financial investment plans in the state. Government, Research and Enterprise AI is USD 24.39 million in 2025 and USD 252.00 million in 2035.
Which Technology and Siting Shifts Are Reshaping Mexico AI Data Center Halls?
Mexico AI Data Center halls are moving to 100 kW racks, campus-scale power and sites outside Querétaro, which lifts the facility content per AI MW from USD 9.06 million in 2020 to USD 12.19 million in 2035.
Liquid-cooled halls become the default for new Bajío buildings
ODATA describes QR03 as built for the AI era, and Coatlicue’s 200 cabinets are liquid-cooled; DC Market Insights models Cooling Infrastructure rising from USD 82.28 million in 2025 to USD 573.01 million in 2035, a 21.42% CAGR, faster than electrical systems.
Durango and Nuevo León attract campuses with their own power plans
Fermaca announced Fermaca Digital City in Durango in December 2025 as a 250 MW AI-ready campus on NVIDIA technology, funded by Fermaca, and met the Durango government and NVIDIA in Santa Clara in January 2026 to review progress (Source: Fermaca). Durango grows from USD 4.06 million in 2025 to USD 206.18 million in 2035 in the model, 48.11% a year.
Self-supply plants of 0.7-20 MW sit beside AI halls
The energy regulator’s Diario Oficial de la Federación (DOF) self-supply agreement of September 2025 set a simplified permit route for grid-connected self-supply plants of 0.7-20 MW, so operators add on-site generation and storage to cover the gap before CFE lines arrive. DC Market Insights counts this switchgear and integration inside Electrical Infrastructure, the largest component at 35.26% of 2025 spend.
Market Restraints: Can CFE Deliver Enough Power for Mexico AI Data Centers?
Transmission capacity in the Bajío and the timing of federal grid works are the two limits that cut the 2035 Mexico AI Data Center value to USD 1.53 billion in the low case.
CFE transmission in the Bajío lags campus plans
CFE plans about MXN 9 billion of transmission and substations for Querétaro in 2026-2030, and its works there are to add up to 800 MW of transmission capacity, while Governor Mauricio Kuri said the limit is transmission and distribution, not generation (Source: CFE; Querétaro state government, September 2026). The national power plan for 2025-2030 adds 29,074 MW of generation and MXN 124.5 billion of transmission across 158 projects, according to the Secretaría de Energía (SENER, April 2025). The low case (25% fewer completions from 2027, a 5-point lower AI share and 5% lower prices) cuts 2035 spend by 33%.
Federal caution on water and energy use
President Claudia Sheinbaum said on 18 August 2026 that Mexico needs data centers for AI but should not necessarily be the data center of other countries, citing energy and water, and that grid investment in some areas could take one to three years (Source: Presidency press conference). DC Market Insights keeps the AI share of new capacity at 57% in 2030, below the 60% global average, to reflect this.
Which Mexico AI Data Center Opportunities Pay Suppliers Best After 2027?
Suppliers to the Mexico AI Data Center Market can win most in services and in the AI network fabric, which together hold 30.27% of 2035 value in the DC Market Insights model.
Operations and lifecycle services for a 1,241 MW AI base
Operations Services and Software grows 58.50% a year as installed AI capacity rises from 32 MW in 2025 to 1,241 MW in 2035 at USD 0.40-0.50 million per MW a year, the fastest of all segments.
AI network fabric inside wholesale halls
AI Network Fabric holds 7% of new-build capital, USD 18.58 million in 2025, and grows 22.28% a year because inference halls built for Mexican enterprises need dense optical cabling between GPU racks.
How Much Does a Megawatt of AI Data Center Capacity Cost in Mexico?
In the Mexico AI Data Center Market, facility infrastructure for one AI megawatt costs about USD 10.00 million per MW in 2025, before GPU servers, and the per-MW price climbs 2% a year (DC Market Insights estimate).
| Price point | 2020 | 2025 | 2030 | 2035 |
|---|---|---|---|---|
| Facility content per new AI MW (USD million) | 9.06 | 10.00 | 11.04 | 12.19 |
| Operations services per installed AI MW a year (USD million) | 0.30 | 0.40 | 0.45 | 0.50 |
| AI share of new IT capacity | 3% | 28% | 57% | 62% |
Public anchors bracket the figure: ODATA QR03 at more than USD 3 billion for up to 300 MW of IT implies about USD 10.0 million per MW including the shell; KIO’s potential USD 1.3 billion for about 100 MW implies USD 13.0 million; CloudHQ’s nearly USD 6 billion for about 900 MW of IT implies USD 6.7 million because the first phases are cloud halls. Electricity is not a price point here, but large users pay CFE’s industrial tariffs on top.
What Mexican Laws, Permits and Standards Apply to AI Data Centers?
Four federal instruments shape the Mexico AI Data Center Market, worth USD 515.23 million in 2026: the Electricity Sector Law, the self-supply permit route, the Plan México tax decree and the federal personal-data law.
- Ley del Sector Eléctrico (Electricity Sector Law), promulgated 18 March 2025: generation permits start at 0.7 MW, and isolated and grid-connected self-supply cover plants of 0.7 MW and more, with CFE holding at least 54% in mixed schemes (Source: Diario Oficial de la Federación).
- Simplified procedure for grid-connected self-supply of 0.7-20 MW, agreement of the Comisión Nacional de Energía (CNE) signed 11 September 2025 (Source: DOF).
- Plan México decree of 21 January 2025: immediate deduction for new fixed assets until 30 September 2030 and an extra 25% deduction on training and innovation spending, which lowers the after-tax cost of AI hall equipment (Source: DOF).
- Ley Federal de Protección de Datos Personales en Posesión de los Particulares, reissued in March 2025, which keeps regulated personal data under Mexican rules and supports in-country inference for banks and health providers (Source: DOF).
- Design standards used by Mexican operators: ANSI/TIA-942 (American National Standards Institute and Telecommunications Industry Association) for data center ratings and the ASHRAE (American Society of Heating, Refrigerating and Air-Conditioning Engineers) thermal guidelines for liquid-cooled equipment.
Which Mexico AI Data Center Segment Leads by Component, Workload and Data Center Type?
Electrical Infrastructure carries the most value, USD 95.55 million or 35.26% of 2025 spend, and Operations Services and Software grows fastest at 58.50% a year.
Mexico AI Data Center Market by Component
| Component | 2025 | Share 2025 | 2035 | CAGR 2025-2035 |
|---|---|---|---|---|
| Electrical Infrastructure | USD 95.55 million | 35.26% | USD 607.74 million | 20.32% |
| Cooling Infrastructure | USD 82.28 million | 30.37% | USD 573.01 million | 21.42% |
| Building Shell, Fit-Out and Racks | USD 69.01 million | 25.47% | USD 416.74 million | 19.70% |
| AI Network Fabric | USD 18.58 million | 6.86% | USD 138.91 million | 22.28% |
| Operations Services and Software | USD 5.54 million | 2.04% | USD 554.52 million | 58.50% |
| Total | USD 270.96 million | 100.00% | USD 2.29 billion | 23.80% |
Cooling Infrastructure gains on electrical systems because liquid loops cost more per MW than air-side equipment; the shell and rack share falls from 25.47% to 18.19%.
Mexico AI Data Center Market by Workload
| Workload | 2025 | Share 2025 | 2035 | CAGR 2025-2035 |
|---|---|---|---|---|
| AI Training | USD 162.58 million | 60.00% | USD 916.37 million | 18.88% |
| AI Inference | USD 108.38 million | 40.00% | USD 1.37 billion | 28.92% |
| Total | USD 270.96 million | 100.00% | USD 2.29 billion | 23.80% |
AI Inference grows 28.92% a year and passes training halls in 2030, because banks, retailers and government agencies in Mexico deploy models close to users.
Mexico AI Data Center Market by Data Center Type
| Data center type | 2025 | Share 2025 | 2035 | CAGR 2025-2035 |
|---|---|---|---|---|
| Hyperscale and Cloud Self-Build | USD 130.06 million | 48.00% | USD 985.09 million | 22.44% |
| Wholesale Colocation AI Campuses | USD 108.38 million | 40.00% | USD 962.19 million | 24.40% |
| Government, Research and Enterprise AI | USD 24.39 million | 9.00% | USD 252.00 million | 26.30% |
| Edge AI Data Centers | USD 8.13 million | 3.00% | USD 91.64 million | 27.41% |
| Total | USD 270.96 million | 100.00% | USD 2.29 billion | 23.80% |
Wholesale Colocation AI Campuses grow faster than hyperscale self-build because ODATA, CloudHQ, KIO and Terranova lease AI halls to clouds and to GPU cloud providers.
DC Exclusive: The Mexico AI Campus Power Tracker, 9 Projects and 1,550 MW of Named IT Capacity
For the Mexico AI Data Center Market, DC Market Insights built this tracker from 14 inputs: nine named projects and grid programmes hold 1,550 MW of named IT capacity, against 980 MW of total completions and 503 MW of AI completions modelled for 2026-2030; the gap is a modelled estimate of how much of the pipeline gets power in time.
| Project | State | IT capacity | Investment | Status (date) |
|---|---|---|---|---|
| ODATA QR03 | Querétaro | Up to 300 MW (72 MW first building) | More than USD 3 billion | 200 MW of power energised (Feb 2026) |
| CloudHQ Querétaro campus | Querétaro | About 900 MW (about 1,000 MW of power) | Nearly USD 6 billion | Raised from USD 4.8 billion (Oct 2026) |
| KIO QRO3 expansion | Querétaro | About 100 MW | Up to USD 1.3 billion to 2030 | More than USD 200 million in 2026 (Aug 2026) |
| Fermaca Digital City | Durango | 250 MW AI-ready | Funded by Fermaca | Announced (Dec 2025) |
| Terranova first Mexico campus | Querétaro | Land and power for up to 1 GW (not counted) | Part of a USD 1.5 billion three-country plan | Opened (Feb 2026) |
| Nuevo León HPC and AI center | Nuevo León | Not stated | USD 1 billion initial (state claim) | Phases 2026-2030 (Nov 2025) |
| Coatlicue public supercomputer | Site not announced | About 200 liquid-cooled cabinets | MXN 6 billion | Build from Jan 2026 |
| AWS Mexico (Central) Region | Querétaro | Three Availability Zones | More than USD 5 billion over 15 years | 2 MW energised by CFE (Jan 2026) |
| CFE Querétaro grid programme | Querétaro | Up to 800 MW of transmission | About MXN 9 billion, 2026-2030 | 1,705 MW under review with MEXDC (Sep 2026) |
The tracker shows why Querétaro’s share falls: the 1,300 MW of named Querétaro IT capacity exceeds the 800 MW of transmission CFE plans to add there, so DC Market Insights shifts part of the 2028-2035 build to Guanajuato, Nuevo León and Durango.
Querétaro or Durango: Where Is Mexico AI Data Center Spending Heading by Region?
In the Mexico AI Data Center Market, the Bajío leads with USD 195.09 million, 72% of 2025 spend, and the North-Central and Northwest region grows fastest at 48.09% a year from a USD 5.42 million base.
| Region | 2025 | Share 2025 | 2035 | CAGR 2025-2035 |
|---|---|---|---|---|
| Bajío (Querétaro and Guanajuato) | USD 195.09 million | 72.00% | USD 1.33 billion | 21.15% |
| Valley of Mexico (Mexico City and State of Mexico) | USD 37.93 million | 14.00% | USD 274.91 million | 21.90% |
| Northeast (Nuevo León and Coahuila) | USD 24.39 million | 9.00% | USD 297.82 million | 28.43% |
| North-Central and Northwest (Durango, Chihuahua, Sonora, Baja California) | USD 5.42 million | 2.00% | USD 274.91 million | 48.09% |
| West and South (Jalisco, Hidalgo and other states) | USD 8.13 million | 3.00% | USD 114.55 million | 30.28% |
| Total | USD 270.96 million | 100.00% | USD 2.29 billion | 23.80% |
Bajío (Querétaro and Guanajuato)
The Bajío falls from 72% to 58% of spend by 2035 but still reaches USD 1.33 billion; Querétaro reports more than USD 12 billion of announced data center investment, according to state economic development secretary Marco Del Prete (August 2026).
Valley of Mexico (Mexico City and State of Mexico)
The Valley of Mexico grows 21.90% a year to USD 274.91 million, led by enterprise and edge inference halls in the State of Mexico and Mexico City, where Scala Data Centers opened a Tepotzotlán site with 5 MW of initial critical capacity.
Northeast (Nuevo León and Coahuila)
The Northeast grows 28.43% a year to USD 297.82 million, helped by Oracle’s Monterrey region and the state HPC programme.
North-Central and Northwest (Durango, Chihuahua, Sonora, Baja California)
This region rises from 2% to 12% of spend, USD 274.91 million in 2035, as Fermaca’s 250 MW Durango campus comes online in phases.
West and South (Jalisco, Hidalgo and other states)
West and South grows 30.28% a year to USD 114.55 million, led by Guadalajara inference demand in Jalisco.
Which Mexican States Host the Most AI Data Center Spend?
Querétaro leads with USD 178.83 million in 2025, 66% of the Mexico AI Data Center Market, and Durango is the fastest-growing large state at 48.11% a year.
| Rank | State | 2025 | 2035 | CAGR 2025-2035 | Region |
|---|---|---|---|---|---|
| 1 | Querétaro | USD 178.83 million | USD 1.15 billion | 20.41% | Bajío |
| 2 | Estado de México | USD 24.39 million | USD 160.36 million | 20.72% | Valley of Mexico |
| 3 | Nuevo León | USD 21.68 million | USD 252.00 million | 27.80% | Northeast |
| 4 | Guanajuato | USD 16.26 million | USD 183.27 million | 27.41% | Bajío |
| 5 | Mexico City | USD 13.55 million | USD 114.55 million | 23.80% | Valley of Mexico |
| 6 | Jalisco | USD 5.96 million | USD 82.47 million | 30.05% | West and South |
| 7 | Durango | USD 4.06 million | USD 206.18 million | 48.11% | North-Central and Northwest |
| 8 | Coahuila | USD 2.71 million | USD 45.82 million | 32.68% | Northeast |
| 9 | Hidalgo | USD 1.35 million | USD 20.62 million | 31.34% | West and South |
| 10 | Chihuahua | USD 0.81 million | USD 34.36 million | 45.46% | North-Central and Northwest |
| 11 | Sonora | USD 0.27 million | USD 18.33 million | 52.47% | North-Central and Northwest |
| 12 | Baja California | USD 0.27 million | USD 16.04 million | 50.45% | North-Central and Northwest |
| – | Other states | USD 0.82 million | USD 11.46 million | – | West and South |
Nuevo León (11% of 2035 spend) and Guanajuato (8%) rank next by 2035; the Mexico Data Center Infrastructure Market gives the all-hall picture for the same states.
What If CFE Connects Campuses Faster or Slower? Mexico AI Data Center Scenarios to 2035
The 2035 Mexico AI Data Center Market forecast ranges from USD 1.53 billion to USD 2.85 billion around the USD 2.29 billion base case, depending on how fast CFE connects new campuses.
| Scenario | Assumption from 2027 | 2035 value | CAGR 2025-2035 |
|---|---|---|---|
| Low | New capacity −25%, AI share −5 points, price −5% | USD 1.53 billion | 18.87% |
| Base | 230-300 MW a year, AI share 57-62% | USD 2.29 billion | 23.80% |
| High | New capacity +20%, price +5% | USD 2.85 billion | 26.52% |
The low case matches a grid build that takes the full three years the President mentioned in August 2026; the high case matches CFE clearing most of the 1,705 MW under review by 2029.
Which Companies Equip and Develop Mexico AI Data Centers, and How Concentrated Are They?
Schneider Electric leads Mexico AI Data Center Market equipment and services with about 13% of 2025 value, and the top five suppliers hold about 45% (DC Market Insights estimate, based on installed-base presence in Querétaro campuses).
- Schneider Electric
- Vertiv
- Eaton
- ABB
- Siemens
- Johnson Controls
- Trane Technologies
- ODATA
- CloudHQ
- KIO Data Centers
- Triara (Telmex)
- Equinix
- Scala Data Centers
- Terranova
- Fermaca
- Amazon Web Services (AWS)
- Microsoft
On the buyer side, ODATA, CloudHQ and KIO hold most of the wholesale AI capacity under construction in Querétaro. Equinix entered Mexico in 2019 by buying three Axtel data centers for USD 175 million, two of them in Querétaro, according to the Equinix Mexico entry release. Google and Oracle also run cloud regions. The AI Data Center Market gives the global context for these suppliers.
Which 2026 Announcements Moved the Mexico AI Data Center Market?
Six dated events in 2026 moved the Mexico AI Data Center Market toward USD 515.23 million for the year.
- In January 2026, CFE energised 26.8 MW in Querétaro: 2 MW for AWS, 6 MW for Abbott and 18.8 MW for ODATA (Source: CFE).
- In February 2026, ODATA energised QR03, a more than USD 3 billion campus for up to 300 MW of IT (Source: ODATA).
- In February 2026, Terranova opened its first Mexico campus in Querétaro with land and power for up to 1 GW (Source: Terranova).
- In August 2026, KIO Data Centers announced more than USD 200 million of investment in Mexico for 2026 and up to USD 1.3 billion for QRO3 (Source: KIO).
- In September 2026, CFE and MEXDC agreed to review 1,705 MW of new data center demand, with three pilot projects (Source: CFE and MEXDC).
- In October 2026, CloudHQ raised its Querétaro campus to nearly USD 6 billion and about 1,000 MW of power (Source: CloudHQ).
Methodology: How Is the Mexico AI Data Center Model Calculated?
The Mexico AI Data Center Market model multiplies megawatts by money: DC Market Insights runs 16 yearly completion cohorts through 12 inputs. The inputs are new IT MW completed in Mexico (15 MW in 2020, 65 MW in 2025, 300 MW in 2030, 230 MW in 2035), calibrated to MEXDC’s 115 MW in 2023 and 279 MW in 2026; the AI share of new capacity (3%, 28%, 57%, 62%); AI facility content of USD 10.00 million per MW in 2025 rising 2% a year, booked 50% in the completion year and 50% in the year before; and services of USD 0.30-0.50 million per installed AI MW a year (1% retired a year).
Two ceilings and one floor test the total. First, installed IT load of 1,175 MW in 2030 stays below MEXDC’s 1,500 MW sector target, and 1,443 MW in 2031 below the 1.73 GW MEXDC projects as required (ceiling). Second, modelled AI facility capital of USD 6.15 billion in 2026-2030 equals 51% of the more than USD 12 billion of data center investment announced for Querétaro, a figure that also covers land and conventional halls (ceiling). Third, KIO’s more than USD 200 million plan for 2026 alone equals 39% of the USD 515.23 million modelled for 2026 (floor). Component, workload, type, region and state tables all add up to the yearly total, and each CAGR comes from the 2025 and 2035 endpoints; method notes sit on the DC Market Insights research methodology page.
Table of contents
- 01Introduction
- 1.1Market Definition and Scope
- 1.2Included and Excluded Elements
- 1.3How the Segments Fit Together
- 1.4Why Mexico AI Data Center Market Estimates Differ
- 02Research Methodology
- 2.1Bottom-Up Model: AI MW × Content per MW
- 2.2Bound Checks
- 2.3Source Ledger
- 03Executive Summary
- 3.1Market Snapshot, 2025, 2026 and 2035
- 3.2Key Market Statistics
- 3.3Key Takeaways
- 04Market Dynamics
- 4.1Driver: AWS, Microsoft, Google and Oracle Cloud Regions
- 4.2Driver: ODATA QR03, CloudHQ and KIO QRO3 Campuses
- 4.3Driver: Coatlicue Supercomputer and State AI Centers
- 4.4Trend: Liquid-Cooled Halls in the Bajío
- 4.5Trend: Durango and Nuevo León Campuses
- 4.6Trend: Self-Supply Plants of 0.7-20 MW
- 4.7Restraint: CFE Transmission in the Bajío
- 4.8Restraint: Federal Caution on Water and Energy
- 4.9Opportunity: Operations and Lifecycle Services
- 4.10Opportunity: AI Network Fabric
- 05Pricing Analysis
- 5.1Cost per AI MW, 2020-2035
- 5.2Public Price Anchors
- 06Standards and Regulation
- 6.1Ley del Sector Eléctrico 2025
- 6.2Self-Supply Permit Route of 0.7-20 MW
- 6.3Plan México Tax Decree
- 6.4Federal Personal Data Law
- 6.5ANSI/TIA-942 and ASHRAE Guidelines
- 07Market Segmentation
- 7.1By Component: Electrical Infrastructure
- 7.2By Component: Cooling Infrastructure
- 7.3By Component: Building Shell, Fit-Out and Racks
- 7.4By Component: AI Network Fabric
- 7.5By Component: Operations Services and Software
- 7.6By Workload: AI Training
- 7.7By Workload: AI Inference
- 7.8By Data Center Type: Hyperscale and Cloud Self-Build
- 7.9By Data Center Type: Wholesale Colocation AI Campuses
- 7.10By Data Center Type: Government, Research and Enterprise AI
- 7.11By Data Center Type: Edge AI Data Centers
- 08DC Exclusive: Mexico AI Campus Power Tracker
- 8.1Nine Projects and 1,550 MW of Named IT Capacity
- 8.2Pipeline Versus Modelled Completions
- 09Regional Insights
- 9.1Bajío (Querétaro and Guanajuato)
- 9.2Valley of Mexico
- 9.3Northeast
- 9.4North-Central and Northwest
- 9.5West and South
- 10State Analysis
- 10.1Querétaro
- 10.2Estado de México
- 10.3Nuevo León
- 10.4Guanajuato
- 10.5Mexico City
- 10.6Jalisco
- 10.7Durango
- 10.8Coahuila
- 10.9Hidalgo
- 10.10Chihuahua
- 10.11Sonora
- 10.12Baja California
- 11Forecast Scenarios
- 11.1Low Case
- 11.2Base Case
- 11.3High Case
- 12Competitive Insights
- 12.1Schneider Electric
- 12.2Vertiv
- 12.3Eaton
- 12.4ABB
- 12.5Siemens
- 12.6Johnson Controls
- 12.7Trane Technologies
- 12.8ODATA
- 12.9CloudHQ
- 12.10KIO Data Centers
- 12.11Triara (Telmex)
- 12.12Equinix
- 12.13Scala Data Centers
- 12.14Terranova
- 12.15Fermaca
- 12.16Amazon Web Services (AWS)
- 12.17Microsoft
- 13Recent Developments
- 13.1Dated Events, January-October 2026
- Fig. 1Mexico AI Data Center Market Size, 2020-2035
- Table 1Report Attributes
- Table 2Scope Comparison
- Table 3Price per AI MW, 2020-2035
- Table 4Market by Component
- Table 5Market by Workload
- Table 6Market by Data Center Type
- Table 7Mexico AI Campus Power Tracker
- Table 8Market by Region
- Table 9Top 12 States
- Table 10Forecast Scenarios
About this report
Written by Amit Jain and reviewed by Deepti Agrawal, Senior Editor, Research. Figures are built top-down and bottom-up and reconciled before publication, with 2025 as the base year.
Read our methodologyHow we built this
- Historical period2020-2024
- Base year2025
- Forecast period2026-2035
- Sizing approachTop-down + bottom-up
Need more than the report?
Advisory on this market
Due diligence, site selection and market entry work, by the analysts who wrote this report.
See consulting servicesFrequently asked questions
USD 515.23 million in 2026, up 90.15% from USD 270.96 million in 2025, according to DC Market Insights estimates. The market is projected to reach USD 2.29 billion by 2035, a CAGR of 23.80% from 2025, as Querétaro campuses get CFE power.
USD 270.96 million of 2025 facility spend on halls for AI training and inference in Mexico: electrical systems, cooling, shell and racks, AI network fabric, and operations services. GPU servers, land, electricity, colocation rent and AI software such as data science platforms are excluded.
Operations Services and Software grows fastest at 58.50% a year, from USD 5.54 million in 2025 to USD 554.52 million in 2035, because the installed AI base rises from 32 MW to 1,241 MW. Electrical Infrastructure is the largest component at 35.26% of 2025 spend.
About USD 10.00 million per AI MW in 2025 for facility infrastructure before GPU servers, rising to USD 12.19 million by 2035 (DC Market Insights estimate). ODATA QR03 at more than USD 3 billion for up to 300 MW implies a similar USD 10.0 million per MW.
USD 195.09 million, 72% of 2025 spend, goes to the Bajío (Querétaro and Guanajuato), the leading region. North-Central and Northwest Mexico grows fastest at 48.09% a year because Fermaca’s 250 MW Durango campus has power outside the Bajío grid.
279 MW of installed data center capacity in 2026, up from 115 MW in 2023, with 205 MW under construction, according to MEXDC. DC Market Insights models 1,175 MW by 2030 and 2,351 MW by 2035, of which 1,241 MW is AI capacity.
About 13% of 2025 equipment and services value goes to Schneider Electric, the leader, and the top five suppliers hold about 45% (DC Market Insights estimate). ODATA, CloudHQ, KIO Data Centers, AWS, Microsoft, Google and Oracle lead on the buyer side.
Up to 800 MW of new transmission is what CFE plans for Querétaro, with about MXN 9 billion of grid works in 2026-2030, while 1,705 MW of data center demand is under review. A slower grid build cuts the 2035 value to USD 1.53 billion in the low case.
USD 515.23 million in 2026 is facility spend only. Estimates that add GPU servers, cloud AI revenue, colocation rent or AI software come out several times larger; the previous edition of this page, which mixed hardware, software and services, showed USD 582.42 million for 2025.
USD 270.96 million of 2025 spend covers power, cooling, buildings and AI network fabric for data centers, so the answer is no. Data science platforms and AI data management tools are analytics software that runs on those halls, so they fall outside this market.
Get this report
How do I get the full report?
Request a quote; we reply by email within one business day.
How and when will I receive the report?
By email, within 24-48 business hours of payment.
How can I pay?
Once you accept the quote, we email you a secure payment link.
Can I see a sample first?
Yes. Request a free sample and we will email it to you.
Can the report be tailored to my needs?
Yes. We can add countries, segments or data cuts. Talk to an analyst about the scope you need.
Can I get an invoice or pay against a purchase order?
Write to sales@dcmarketinsights.com and our team will help.