
South Korea Data Center Cooling Market Size, Share & Forecast to 2035
Market at a glance
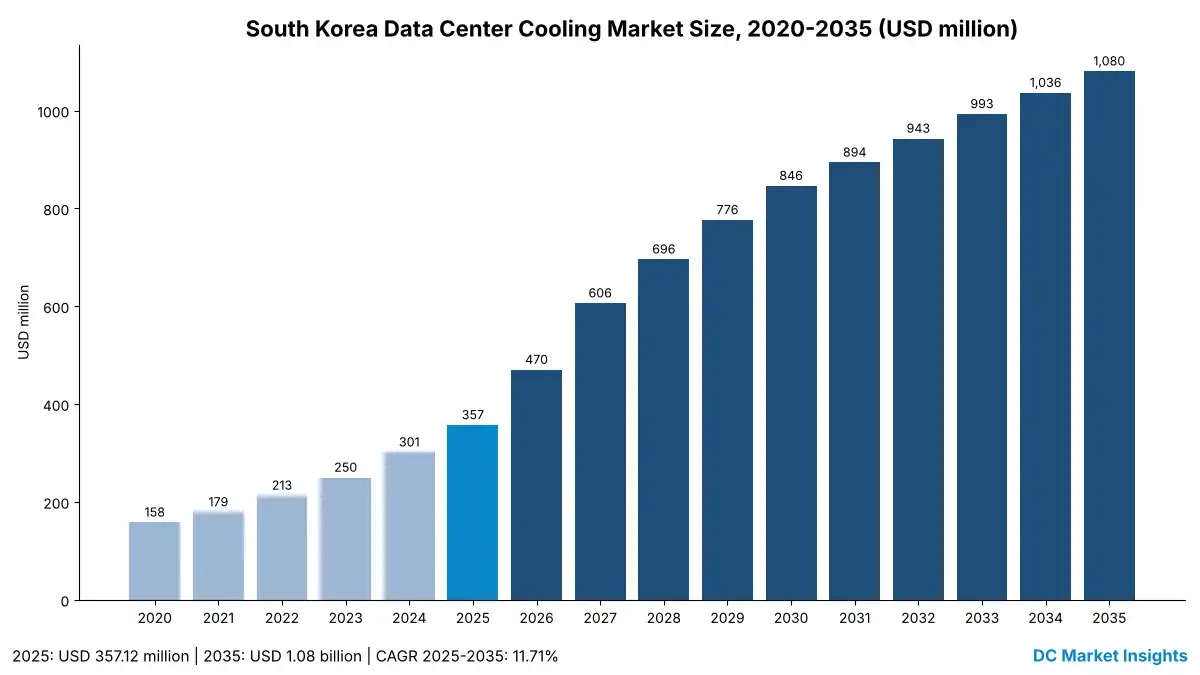
The South Korea Data Center Cooling market was worth USD 357.1 million in 2025 and is forecast to reach USD 1,080.0 million by 2035, growing at a 11.71% CAGR. Capital Region accounts for 66% of the market.
 By Amit Jain, Senior Consultant, ICT & Emerging Technologies
 Reviewed by Deepti Agrawal
Last updated 11 Oct 2026
Base year 2025 PDF + Excel
Source: DC Market Insights analysis
Key findings
260,000 GPUs Lift the Market to USD 846.20 million by 2030
Direct-to-Chip Cooling Grows from USD 32.14 million to USD 259.27 million
Grid Rules Push Large Loads out of the Capital Region
Honam and Yeongnam Add USD 252.58 million by 2035
What is inside the report
- 01Introduction
- 02Research Methodology
- 03Executive Summary
- 04Market Scope and Definition
- 05South Korea Data Center Cooling Market Drivers
- 06Market Trends
- 07Market Challenges
- 08Market Opportunities
- 09Pricing Analysis: Cooling Content per MW and Electricity Tariffs
- 10Standards and Regulation
- 23chapters
- 2020-2024Historical period
- 2026-2035Forecast period
- 12Companies profiled
Regional insights
- Capital Region66%
- Chungcheong Region12%
- Yeongnam Region11%
- Honam Region6%
- Gangwon and Jeju5%
Segmentation
Companies profiled
- LG Electronics
- Samsung C&T
- SK Enmove
- GRC (Green Revolution Cooling)
- Vertiv
- Schneider Electric
- Daikin
- Trane Technologies
- Carrier
- Johnson Controls
- Mitsubishi Electric
- Stulz
Recent developments
LG Electronics signed a long-term supply agreement for air-cooled centrifugal chillers for North American AI data centers. (Source: LG Electronics)
LG Electronics expanded air-cooled chiller production lines for AI data centers in Pyeongtaek and Changwon. (Source: LG Electronics)
LG Electronics showed CDUs for direct-to-chip cooling and immersion systems at Data Center World Asia 2026. (Source: LG Electronics)
NAVER, Brookfield and NVIDIA agreed to expand the GAK Sejong AI factory from 55 MW to 200 MW. (Source: NAVER)
Vertiv appointed BBR Company as its Korean distributor for thermal products. (Source: Vertiv)
the Samsung SDS-led consortium set a target of more than 15,000 GPUs by 2028 for the National AI Computing Center in Haenam. (Source: Samsung SDS)
Full analysis
The South Korea Data Center Cooling Market covers the equipment and services that remove heat from data center (DC) white space in South Korea: chillers and cooling towers, precision air conditioning and air handling, direct-to-chip liquid cooling with coolant distribution units (CDUs), rear-door and in-row coolers, immersion cooling tanks and fluids, and the installation, maintenance and retrofit services around them. DC Market Insights values the market at USD 357.12 million in 2025 and forecasts USD 1.08 billion by 2035, a compound annual growth rate (CAGR) of 11.71%. The build receipt for 2025 is 230 megawatts (MW) of new information technology (IT) capacity × USD 1.25 million of cooling content per MW = USD 287.50 million of new-build spend, plus 1,547 MW installed × USD 45 thousand per MW of service and refresh spend = USD 69.61 million. Immersion cooling is the fastest segment at 26.00% a year because racks for graphics processing units (GPUs) exceed what air can remove, and the Honam Region is the fastest region at 19.72% as national artificial intelligence (AI) computing capacity is placed in Jeollanam-do.
Executive Summary: How Big Is the South Korea Data Center Cooling Market?
The market is worth USD 357.12 million in 2025. The South Korea Data Center Cooling Market size was valued at USD 158.00 million in 2020, reached USD 357.12 million in 2025, and is anticipated to reach USD 1.08 billion by 2035, at a CAGR of 11.71% during the forecast period. Between 2020 and 2025 the market grew at 17.71% a year as new IT capacity rose from 120 MW to 230 MW a year.
| Report Attribute | Details |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| South Korea Data Center Cooling Market Size 2025 | USD 357.12 million |
| South Korea Data Center Cooling Market CAGR (2025-2035) | 11.71% |
| South Korea Data Center Cooling Market Size 2035 | USD 1.08 billion |
DC Market Insights estimates that liquid-based cooling rises from 16.00% of spend in 2025 to 40.00% in 2035, worth USD 432.12 million, as the 260,000 GPUs announced for Korea in October 2025 (Source: NVIDIA) move into service. Hyperscale and AI data centers grow from 38.00% to 52.00% of the market, and the Capital Region share falls from 66.00% to 50.00% as new campuses move south. The wider picture for the host market is in the South Korea Data Center Market report.
Market Scope: What Is the South Korea Data Center Cooling Market?
It is USD 357.12 million (2025) of spend on heat-rejection equipment and cooling services for data centers located in South Korea, counted at the price paid by the operator.
Included: chillers (air-cooled, water-cooled and centrifugal), cooling towers and dry coolers, computer room air handlers (CRAH) and computer room air conditioners (CRAC), fan walls, CDUs, cold plates and secondary fluid networks, rear-door heat exchangers, in-row coolers, immersion tanks and dielectric fluids, cooling controls sold with the equipment, and installation, maintenance, retrofit and refresh services. Excluded: IT hardware, electrical systems (uninterruptible power supplies and switchgear), building shell, comfort cooling for offices, and the electricity used for cooling.
How the segments fit together: each of the three dimensions (solution type, data center type and cooling technique) splits the same USD 357.12 million total in 2025 and the same USD 1.08 billion total in 2035. Services (USD 62.50 million in 2025) sit inside solution type; in cooling technique they are allocated to the air or liquid system they maintain. Readers who need the full thermal chain, including heat reuse and controls software, can compare this market with the South Korea Data Center Thermal Management Market.
Market Drivers: What Drives the South Korea Data Center Cooling Market?
New IT capacity of 300 MW in 2026 drives the market. DC Market Insights estimates that South Korea adds 300 MW of IT load in 2026, rising to 470 MW in 2030, and each MW carries USD 1.29 million to USD 1.45 million of cooling content.
260,000 GPUs Lift the Market to USD 846.20 million by 2030
In October 2025 NVIDIA Corporation (NVIDIA), the Korean government, Samsung, SK Group (SK), Hyundai and NAVER Corporation (NAVER) announced the deployment of 260,000 NVIDIA GPUs in Korea (Source: NVIDIA), including up to 50,000 GPUs for the Ministry of Science and ICT (MSIT) sovereign AI programme (Source: NVIDIA). At roughly 1.2 to 1.5 kilowatts per GPU including networking and overhead, 260,000 GPUs need about 310 MW to 390 MW of IT load, which is 1.0 to 1.3 times Korea’s entire 2026 build in this model. DC Market Insights models the market rising from USD 357.12 million in 2025 to USD 846.20 million in 2030. Global data centre electricity demand rose 17% in 2025 (Source: IEA), so heat rejection, not floor space, is the binding constraint.
Hyperscale Campuses Commit More Than USD 15 Billion
Amazon Web Services (AWS) plans to invest USD 5.88 billion in Korea by 2027, and its Ulsan AI data center with SK Group is scheduled to begin operations by 2027 (Source: SK Telecom). In July 2026 NAVER, Brookfield and NVIDIA agreed to lift the AI factory at GAK Sejong (NAVER’s Sejong data center campus) from 55 MW to 200 MW in a USD 10 billion project (Source: NAVER). The 145 MW Sejong increment alone represents about USD 199 million of cooling equipment at the 2028 content rate of USD 1.37 million per MW.
Rack Densities Push Content per MW from USD 1.05 Million to USD 1.55 Million
Cooling content per new MW rises from USD 1.05 million in 2020 to USD 1.25 million in 2025 and USD 1.55 million in 2035 in the DC Market Insights model, because direct-to-chip loops add CDUs, manifolds and a secondary fluid network on top of the chillers that air-cooled halls already need. The SK-AWS Ulsan design uses a hybrid cooling system combining air and liquid cooling (Source: SK Telecom), which is the pattern behind the 22.42% CAGR of liquid-based cooling.
Market Trends: What Are the South Korea Data Center Cooling Market Trends?
The three trends in the South Korea Data Center Cooling Market are the move to direct-to-chip liquid cooling (9.00% of 2025 spend, 24.00% by 2035), Korean groups building immersion cooling supply chains, and chillers designed for warmer water.
Direct-to-Chip Cooling Grows from USD 32.14 million to USD 259.27 million
Direct-to-chip liquid cooling grows at 23.22% a year. In September 2026 LG Electronics showed its chip-to-chiller portfolio at Data Center World Asia 2026, presenting the CDU as a key component of a direct-to-chip system (Source: LG Electronics). CDUs, cold-plate loops and facility water units together form about USD 0.30 million of the USD 1.45 million per MW content in 2030, in DC Market Insights estimates.
Korean Groups Build an Immersion Cooling Supply Chain
Immersion cooling is the fastest growing solution type at 26.00%, from USD 5.36 million in 2025 to USD 54.01 million in 2035. In March 2025 SK Telecom, Giga Computing and SK Enmove agreed to validate all three common liquid cooling methods (Source: SK Telecom), and in October 2025 LG Electronics, SK Enmove and GRC (Green Revolution Cooling) signed a memorandum of understanding (MOU) under which LG integrates the cooling system, SK Enmove supplies fluids and GRC supplies tanks (Source: LG Electronics).
Chillers Stay the Largest Line at USD 324.09 million in 2035
Chillers and cooling towers fall from 36.00% to 30.00% of spend but still grow at 9.69% a year, because every liquid loop still rejects heat to a chiller or dry cooler. In October 2026 LG Electronics said it is expanding air-cooled chiller production lines for AI data centers in Pyeongtaek and Changwon (Source: LG Electronics).
Market Challenges: What Holds the South Korea Data Center Cooling Market Back?
Grid access and a 10.2% power price rise are the two main challenges. Together they can delay part of the USD 505.40 million of new-build cooling spend modelled for 2027.
Grid Rules Push Large Loads out of the Capital Region
The Special Act on Activation of Distributed Energy, promulgated in June 2023, requires a power system impact assessment from users that intend to draw electricity above a threshold set by Presidential Decree (Source: Korea Legislation Research Institute). About 70% of Korean data center power demand was in the Capital Region at end-2022 (Source: Kyunghyang Shinmun, citing MOTIE). DC Market Insights models a USD 235.70 million Capital Region market in 2025 that grows at only 8.65%, below the national 11.71%.
Industrial Power Prices Rose 10.2% in October 2024
Korea Electric Power Corporation (KEPCO) raised the large-user industrial rate from KRW 165.8 to KRW 182.7 per kilowatt-hour (kWh) in October 2024 (Source: Korea Times). At that rate a 10 MW IT hall whose cooling draws 0.30 MW per MW of IT load uses 26,280 megawatt-hours a year for cooling and pays about KRW 4.8 billion, which raises the payback value of efficient chillers but also squeezes operator budgets for new equipment.
Market Opportunities: Where Are the New Revenue Pools in the South Korea Data Center Cooling Market?
Non-capital campuses add USD 252.58 million by 2035. The two largest new revenue pools are non-capital AI campuses, which add USD 252.58 million in Honam and Yeongnam by 2035, and the installed base, which reaches USD 289.80 million of service and refresh spend in 2035.
Honam and Yeongnam Add USD 252.58 million by 2035
The consortium led by Samsung SDS (Samsung Data Systems) for the National AI Computing Center in Haenam targets more than 15,000 GPUs by 2028 (Source: Samsung SDS), and Samsung affiliates signed with MSIT to evaluate AI data centers outside the Seoul Metropolitan Area (Source: OpenAI). Honam grows from USD 21.43 million to USD 129.64 million and Yeongnam from USD 39.28 million to USD 183.65 million.
Installed-Base Service and Retrofit Reaches USD 289.80 million
Installed IT capacity rises from 1,547 MW in 2025 to 5,269 MW in 2035 in the DC Market Insights model, and spend per installed MW rises from USD 45 thousand to USD 55 thousand as air halls are retrofitted with rear-door and in-row coolers. Installed-base spend grows from USD 69.61 million to USD 289.80 million.
Pricing: What Does Data Center Cooling Cost per MW in South Korea?
Data center cooling in South Korea cost about USD 1.25 million per MW of new IT load in 2025, in DC Market Insights estimates, rising to USD 1.55 million per MW by 2035 as liquid cooling spreads.
| Year | Cooling content per new MW (USD million) | Service and refresh per installed MW (USD thousand) | New IT capacity (MW) |
|---|---|---|---|
| 2020 | 1.05 | 40.0 | 120 |
| 2025 | 1.25 | 45.0 | 230 |
| 2030 | 1.45 | 50.0 | 470 |
| 2035 | 1.55 | 55.0 | 510 |
Public anchors: Korean data center development cost including land is about KRW 17.6 billion (USD 13 million) per MW (Source: Financial News, citing Cushman & Wakefield), so cooling at USD 1.25 million is about 9.6% of the total build. Electricity for cooling is priced at KEPCO’s KRW 182.7 per kWh large-user industrial rate (Source: Korea Times).
Standards and Regulation: Which Rules Shape the South Korea Data Center Cooling Market?
Three rule sets shape the USD 357.12 million market. They are grid-impact rules for large loads, international thermal guidelines, and refrigerant phase-down.
- Special Act on Activation of Distributed Energy (2023): power system impact assessment for large electricity users (Source: Korea Legislation Research Institute); it steers new MW, and so cooling spend, toward regions with grid headroom.
- ASHRAE TC 9.9 thermal guidelines: the American Society of Heating, Refrigerating and Air-Conditioning Engineers (ASHRAE) allowable inlet ranges and liquid-cooling water classes, which Korean operators use to set supply temperatures (ASHRAE Datacom Series).
- Kigali Amendment to the Montreal Protocol: hydrofluorocarbon (HFC) phase-down, which moves chillers toward lower-global-warming refrigerants (UNEP Ozone Secretariat).
Market Segmentation: Which Segment Leads the South Korea Data Center Cooling Market, and What Is the Fastest Growing Segment?
Chillers and Cooling Towers lead the South Korea Data Center Cooling Market with 36.00% of 2025 spend (USD 128.56 million), and Immersion Cooling is the fastest growing segment at 26.00% a year to 2035.
By Solution Type: Chillers and Cooling Towers Lead with 36.00%
| Segment | 2025 (USD million) | Share 2025 | 2035 (USD million) | CAGR 2025-2035 |
|---|---|---|---|---|
| Chillers and Cooling Towers | 128.56 | 36.00% | 324.09 | 9.69% |
| Precision Air Conditioning and Air Handling | 103.56 | 29.00% | 194.45 | 6.50% |
| Direct-to-Chip Liquid Cooling | 32.14 | 9.00% | 259.27 | 23.22% |
| Rear-Door and In-Row Cooling | 25.00 | 7.00% | 75.62 | 11.71% |
| Immersion Cooling | 5.36 | 1.50% | 54.01 | 26.00% |
| Services | 62.50 | 17.50% | 172.85 | 10.71% |
Direct-to-chip liquid cooling grows at 23.22%, from USD 32.14 million to USD 259.27 million, while precision air conditioning and air handling grow at 6.50% as new AI halls need fewer air handlers per MW.
By Data Center Type: Hyperscale and AI Data Centers Lead with 38.00%
| Segment | 2025 (USD million) | Share 2025 | 2035 (USD million) | CAGR 2025-2035 |
|---|---|---|---|---|
| Hyperscale and AI Data Centers | 135.70 | 38.00% | 561.75 | 15.26% |
| Colocation Data Centers | 132.13 | 37.00% | 334.89 | 9.75% |
| Enterprise and Public Data Centers | 74.99 | 21.00% | 129.64 | 5.63% |
| Edge Data Centers | 14.28 | 4.00% | 54.01 | 14.23% |
Hyperscale and AI data centers reach USD 561.75 million by 2035 at 15.26%; colocation grows at 9.75%, supported by about 255 MW of capacity pre-leased in the first half of 2026 (Source: Financial News, citing Cushman & Wakefield).
By Cooling Technique: Air-Based Cooling Leads with 84.00%
| Segment | 2025 (USD million) | Share 2025 | 2035 (USD million) | CAGR 2025-2035 |
|---|---|---|---|---|
| Air-Based Cooling | 299.98 | 84.00% | 648.18 | 8.01% |
| Liquid-Based Cooling | 57.14 | 16.00% | 432.12 | 22.42% |
Liquid-based cooling grows at 22.42% and reaches 40.00% of the market by 2035; air-based cooling still grows at 8.01% because every liquid loop keeps an air system for residual heat.
DC Exclusive: The South Korea Cooling Content per MW Model and Solution × Data Center Type Matrix
Hyperscale and AI sites buy 78.6% of 2025 direct-to-chip spend. This is a modelled estimate by DC Market Insights, built from 4 inputs (new IT MW, installed IT MW, cooling content per new MW and service spend per installed MW, each for 16 years) and checked against the 22 facts in the source ledger. The matrix splits the 2025 market of USD 357.12 million by solution type and data center type; rows and columns sum to the segment totals above.
| Solution type (USD million, 2025) | Hyperscale and AI Data Centers | Colocation Data Centers | Enterprise and Public Data Centers | Edge Data Centers | Total |
|---|---|---|---|---|---|
| Chillers and Cooling Towers | 50.51 | 52.33 | 24.04 | 1.67 | 128.56 |
| Precision Air Conditioning and Air Handling | 26.99 | 39.94 | 28.55 | 8.07 | 103.56 |
| Direct-to-Chip Liquid Cooling | 25.26 | 5.41 | 1.21 | 0.25 | 32.14 |
| Rear-Door and In-Row Cooling | 9.23 | 10.43 | 3.91 | 1.42 | 25.00 |
| Immersion Cooling | 4.02 | 0.84 | 0.35 | 0.15 | 5.36 |
| Services | 19.69 | 23.18 | 16.92 | 2.71 | 62.50 |
| Total | 135.70 | 132.13 | 74.99 | 14.28 | 357.12 |
Hyperscale and AI data centers already buy USD 25.26 million of the USD 32.14 million direct-to-chip market (78.6%), while colocation buys USD 39.94 million of precision air, the largest single air cell.
Regional Insights: Which Region Leads the South Korea Data Center Cooling Market, and Which Grows Fastest?
The Capital Region leads the South Korea Data Center Cooling Market with 66.00% of 2025 spend (USD 235.70 million), and the Honam Region grows fastest at 19.72% a year to 2035.
| Region | 2025 (USD million) | Share 2025 | 2035 (USD million) | CAGR 2025-2035 |
|---|---|---|---|---|
| Capital Region | 235.70 | 66.00% | 540.15 | 8.65% |
| Chungcheong Region | 42.85 | 12.00% | 162.04 | 14.23% |
| Yeongnam Region | 39.28 | 11.00% | 183.65 | 16.68% |
| Honam Region | 21.43 | 6.00% | 129.64 | 19.72% |
| Gangwon and Jeju | 17.86 | 5.00% | 64.82 | 13.76% |
Capital Region Holds 66.00% Share
The Capital Region cooling market was USD 235.70 million in 2025 and reaches USD 540.15 million by 2035 at 8.65%. Seoul, Incheon and Gyeonggi held about 70% of data center power demand at end-2022 (Source: Kyunghyang Shinmun, citing MOTIE); growth slows to 8.65% as grid assessments bite.
Chungcheong Region Holds 12.00% Share
The Chungcheong Region cooling market was USD 42.85 million in 2025 and reaches USD 162.04 million by 2035 at 14.23%. NAVER’s GAK Sejong expansion from 55 MW to 200 MW (Source: NAVER) makes Sejong City the largest single cooling project outside the capital.
Yeongnam Region Holds 11.00% Share
The Yeongnam Region cooling market was USD 39.28 million in 2025 and reaches USD 183.65 million by 2035 at 16.68%. The SK-AWS AI data center in Ulsan, due by 2027 with hybrid air and liquid cooling (Source: SK Telecom), lifts Ulsan to USD 66.11 million by 2035.
Honam Region Holds 6.00% Share
The Honam Region cooling market was USD 21.43 million in 2025 and reaches USD 129.64 million by 2035 at 19.72%. The National AI Computing Center in Haenam targets more than 15,000 GPUs by 2028 (Source: Samsung SDS), so Jeollanam-do grows at 22.83%.
Gangwon and Jeju Holds 5.00% Share
The Gangwon and Jeju cooling market was USD 17.86 million in 2025 and reaches USD 64.82 million by 2035 at 13.76%. Cool ambient air in Gangwon-do lowers chiller run hours, and the region grows from USD 17.86 million to USD 64.82 million.
Province and City Analysis: Where in South Korea Is Data Center Cooling Spend Concentrated?
Gyeonggi Province is the largest local market at USD 117.85 million in 2025, and Jeollanam-do is the fastest growing large province at 22.83%.
| Rank | Province or city | Region | 2025 (USD million) | Share 2025 | 2035 (USD million) | CAGR 2025-2035 |
|---|---|---|---|---|---|---|
| 1 | Gyeonggi Province | Capital Region | 117.85 | 33.00% | 270.07 | 8.65% |
| 2 | Seoul | Capital Region | 84.85 | 23.76% | 172.85 | 7.37% |
| 3 | Incheon | Capital Region | 33.00 | 9.24% | 97.23 | 11.41% |
| 4 | Sejong City | Chungcheong Region | 17.14 | 4.80% | 77.78 | 16.33% |
| 5 | Busan | Yeongnam Region | 15.71 | 4.40% | 58.77 | 14.10% |
| 6 | Chungcheongnam-do | Chungcheong Region | 12.86 | 3.60% | 45.37 | 13.44% |
| 7 | Daejeon | Chungcheong Region | 12.86 | 3.60% | 38.89 | 11.71% |
| 8 | Gangwon-do | Gangwon and Jeju | 12.50 | 3.50% | 46.67 | 14.08% |
| 9 | Jeollanam-do | Honam Region | 10.28 | 2.88% | 80.37 | 22.83% |
| 10 | Ulsan | Yeongnam Region | 8.64 | 2.42% | 66.11 | 22.57% |
| 11 | Gyeongsangbuk-do | Yeongnam Region | 8.64 | 2.42% | 33.06 | 14.36% |
| 12 | Gwangju | Honam Region | 6.43 | 1.80% | 25.93 | 14.97% |
Forecast Scenarios: How Could the 2035 South Korea Data Center Cooling Market Forecast Change?
The 2035 South Korea Data Center Cooling Market ranges from USD 864.24 million to USD 1.32 billion, with a base case of USD 1.08 billion.
| Scenario | 2035 size | CAGR 2025-2035 | Assumption |
|---|---|---|---|
| Low | USD 864.24 million | 9.24% | Grid-impact reviews delay about one fifth of planned AI campuses; liquid cooling share stays near 30% |
| Base | USD 1.08 billion | 11.71% | New IT capacity of 470 MW in 2030 and 510 MW in 2035; liquid share 40% |
| High | USD 1.32 billion | 13.95% | All announced GPU programmes built on time; immersion cooling above 8% of spend |
Competitive Insights: Who Are the Leading South Korea Data Center Cooling Market Companies, and What Is the Market Share by Company?
The leading companies in the South Korea Data Center Cooling Market are LG Electronics, Vertiv, Schneider Electric, Trane Technologies and Carrier; DC Market Insights estimates these five hold about 48% of 2025 spend, based on its supplier mapping of announced Korean projects and chiller and air-handler installed base.
- LG Electronics
- Samsung C&T
- SK Enmove
- GRC (Green Revolution Cooling)
- Vertiv
- Schneider Electric
- Daikin
- Trane Technologies
- Carrier
- Johnson Controls
- Mitsubishi Electric
- Stulz
LG Electronics is the domestic leader: its ES (Eco Solution) company reported 2025 revenue of KRW 9.32 trillion (Source: LG Electronics) and says it will keep pursuing AI data center cooling (Source: LG Electronics). Vertiv extended its Korean reach in March 2026 by appointing BBR Company to distribute thermal products including CoolChip CDUs (Source: Vertiv). SK Enmove and GRC compete in immersion cooling through their MOU with LG (Source: LG Electronics), and Samsung SDS designs and operates the Stargate AI data centers it develops with OpenAI (Source: Samsung), which makes Samsung group firms large cooling buyers as well as builders.
Recent Developments: What Changed in the South Korea Data Center Cooling Market in 2026?
Six dated events between January 2026 and October 2026 shaped the market.
- In October 2026, LG Electronics signed a long-term supply agreement for air-cooled centrifugal chillers for North American AI data centers. (Source: LG Electronics)
- In October 2026, LG Electronics expanded air-cooled chiller production lines for AI data centers in Pyeongtaek and Changwon. (Source: LG Electronics)
- In September 2026, LG Electronics showed CDUs for direct-to-chip cooling and immersion systems at Data Center World Asia 2026. (Source: LG Electronics)
- In July 2026, NAVER, Brookfield and NVIDIA agreed to expand the GAK Sejong AI factory from 55 MW to 200 MW. (Source: NAVER)
- In March 2026, Vertiv appointed BBR Company as its Korean distributor for thermal products. (Source: Vertiv)
- In January 2026, the Samsung SDS-led consortium set a target of more than 15,000 GPUs by 2028 for the National AI Computing Center in Haenam. (Source: Samsung SDS)
More country and segment studies are listed under DC Market Insights industries; for the host market see the South Korea Data Center Market.
Methodology: How Did DC Market Insights Build the South Korea Data Center Cooling Market Model?
The model multiplies 230 MW by USD 1.25 million per MW for 2025. DC Market Insights built the South Korea Data Center Cooling Market bottom-up: new IT capacity (230 MW in 2025, 510 MW in 2035) × cooling content per MW (USD 1.25 million to USD 1.55 million) gives new-build spend, and installed IT capacity (1,547 MW to 5,269 MW, with 2.5% a year retired) × service and refresh spend per MW gives installed-base spend. Segment, region and province splits are set for 2020, 2025 and 2035, interpolated and normalised so that every split sums to the total every year.
Three bound checks:
- Ceiling 1: 2025 new-build cooling spend of USD 287.50 million equals 9.6% of total development cost for 230 MW at USD 13 million per MW (Source: Financial News, citing Cushman & Wakefield), inside the usual 8% to 15% mechanical share.
- Ceiling 2: the whole 2025 market of USD 357.12 million is 5.4% of LG Electronics ES revenue of KRW 9.32 trillion (about USD 6.56 billion at KRW 1,420 per USD) (Source: LG Electronics), consistent with data centers being a small part of one supplier’s heating, ventilation and air conditioning sales.
- Floor: 1,547 MW installed × USD 45 thousand per MW of service spend gives USD 69.61 million before any new build.
Full approach: DC Market Insights research methodology.
Table of contents
- 01Introduction
- 1.1Market Definition
- 1.2Historical Period, Base Year and Forecast Period
- 1.3Report Attributes
- 02Research Methodology
- 2.1Build Receipt: New IT Capacity × Cooling Content per MW
- 2.2Installed-Base Service and Refresh Spend
- 2.3Segment, Region and Province Splits
- 2.4Bound Checks: Development Cost Ceiling, Supplier Revenue Ceiling and Installed-Base Floor
- 03Executive Summary
- 3.1Market Snapshot, 2020, 2025 and 2035
- 3.2Key Market Statistics
- 3.3Liquid Cooling, Hyperscale and Regional Share Shifts
- 04Market Scope and Definition
- 4.1Included: Chillers, Air Handling, Liquid Cooling, Immersion and Services
- 4.2Excluded: IT Hardware, Electrical Systems, Building Shell and Electricity
- 4.3How the Segments Fit Together
- 05South Korea Data Center Cooling Market Drivers
- 5.1260,000 GPUs Lift the Market to USD 846.20 million by 2030
- 5.2Hyperscale Campuses Commit More Than USD 15 Billion
- 5.3Rack Densities Push Content per MW from USD 1.05 Million to USD 1.55 Million
- 06Market Trends
- 6.1Direct-to-Chip Cooling Grows from USD 32.14 million to USD 259.27 million
- 6.2Korean Groups Build an Immersion Cooling Supply Chain
- 6.3Chillers Stay the Largest Line at USD 324.09 million in 2035
- 07Market Challenges
- 7.1Grid Rules Push Large Loads out of the Capital Region
- 7.2Industrial Power Prices Rose 10.2% in October 2024
- 08Market Opportunities
- 8.1Honam and Yeongnam Add USD 252.58 million by 2035
- 8.2Installed-Base Service and Retrofit Reaches USD 289.80 million
- 09Pricing Analysis: Cooling Content per MW and Electricity Tariffs
- 9.1Cooling Content per New MW, 2020-2035
- 9.2Service and Refresh Spend per Installed MW
- 9.3Public Anchors: Development Cost per MW and KEPCO Industrial Rate
- 10Standards and Regulation
- 10.1Special Act on Activation of Distributed Energy (2023)
- 10.2ASHRAE TC 9.9 Thermal Guidelines
- 10.3Kigali Amendment to the Montreal Protocol
- 11South Korea Data Center Cooling Market, By Solution Type
- 11.1Chillers and Cooling Towers
- 11.2Precision Air Conditioning and Air Handling
- 11.3Direct-to-Chip Liquid Cooling
- 11.4Rear-Door and In-Row Cooling
- 11.5Immersion Cooling
- 11.6Services
- 12South Korea Data Center Cooling Market, By Data Center Type
- 12.1Hyperscale and AI Data Centers
- 12.2Colocation Data Centers
- 12.3Enterprise and Public Data Centers
- 12.4Edge Data Centers
- 13South Korea Data Center Cooling Market, By Cooling Technique
- 13.1Air-Based Cooling
- 13.2Liquid-Based Cooling
- 14DC Exclusive: Cooling Content per MW Model and Solution × Data Center Type Matrix
- 14.1Model Inputs and Source Ledger
- 14.2Solution × Data Center Type Matrix, 2025
- 14.3Direct-to-Chip and Precision Air Concentration
- 15South Korea Data Center Cooling Market, By Region
- 15.1Capital Region
- 15.2Chungcheong Region
- 15.3Yeongnam Region
- 15.4Honam Region
- 15.5Gangwon and Jeju
- 16Province and City Analysis
- 16.1Gyeonggi Province
- 16.2Seoul
- 16.3Incheon
- 16.4Sejong City
- 16.5Busan
- 16.6Chungcheongnam-do
- 16.7Daejeon
- 16.8Gangwon-do
- 16.9Jeollanam-do
- 16.10Ulsan
- 16.11Gyeongsangbuk-do
- 16.12Gwangju
- 17Forecast Scenarios 2035
- 17.1Low Scenario
- 17.2Base Scenario
- 17.3High Scenario
- 18Competitive Landscape
- 18.1Market Share Analysis, 2025
- 18.2Domestic Leader: LG Electronics
- 18.3Immersion Cooling Partners: SK Enmove and GRC
- 18.4Global Thermal Suppliers in Korea
- 19Company Profiles
- 19.1LG Electronics
- 19.2Samsung C&T
- 19.3SK Enmove
- 19.4GRC (Green Revolution Cooling)
- 19.5Vertiv
- 19.6Schneider Electric
- 19.7Daikin
- 19.8Trane Technologies
- 19.9Carrier
- 19.10Johnson Controls
- 19.11Mitsubishi Electric
- 19.12Stulz
- 20Recent Developments
- 20.1LG Electronics North American Chiller Supply Agreement (October 2026)
- 20.2LG Electronics Expands Chiller Production in Pyeongtaek and Changwon (October 2026)
- 20.3LG Electronics Shows CDUs at Data Center World Asia 2026 (September 2026)
- 20.4GAK Sejong AI Factory Expansion to 200 MW (July 2026)
- 20.5Vertiv Appoints BBR Company in Korea (March 2026)
- 20.6National AI Computing Center in Haenam Targets 15,000 GPUs (January 2026)
- 21Analyst Recommendations
- 22Appendix
- 23Glossary
- 23.1Abbreviations: DC, MW, IT, CDU, CRAH, CRAC, GPU, AI, CAGR, MSIT, KEPCO, HFC, MOU
- Fig. 1South Korea Data Center Cooling Market Size, 2020-2035 (USD Million)
- Table 1Report Attributes
- Table 2Cooling Content per MW, 2020/2025/2030/2035
- Table 3Market by Solution Type (USD Million)
- Table 4Market by Data Center Type (USD Million)
- Table 5Market by Cooling Technique (USD Million)
- Table 6Solution × Data Center Type Matrix, 2025
- Table 7Market by Region (USD Million)
- Table 8Top 12 Provinces and Cities
- Table 9Forecast Scenarios 2035
About this report
Written by Amit Jain and reviewed by Deepti Agrawal, Senior Editor, Research. Figures are built top-down and bottom-up and reconciled before publication, with 2025 as the base year.
Read our methodologyHow we built this
- Historical period2020-2024
- Base year2025
- Forecast period2026-2035
- Sizing approachTop-down + bottom-up
Need more than the report?
Advisory on this market
Due diligence, site selection and market entry work, by the analysts who wrote this report.
See consulting servicesFrequently asked questions
USD 357.12 million in 2025. DC Market Insights values the South Korea Data Center Cooling Market at USD 357.12 million in 2025, up from USD 158.00 million in 2020, and forecasts USD 1.08 billion by 2035.
11.71% a year from 2025 to 2035. The South Korea Data Center Cooling Market grows from USD 357.12 million to USD 1.08 billion as new IT capacity rises from 230 MW to 510 MW a year.
A USD 357.12 million market in 2025 for chillers, cooling towers, precision air conditioning, direct-to-chip liquid cooling, rear-door and in-row coolers, immersion cooling and related services in Korean data centers.
Immersion Cooling at 26.00% a year, from USD 5.36 million in 2025 to USD 54.01 million in 2035. Direct-to-chip liquid cooling follows at 23.22%.
About USD 1.25 million per MW of new IT load in 2025, rising to USD 1.55 million by 2035, in DC Market Insights estimates. That is about 9.6% of a USD 13 million per MW build.
LG Electronics, Vertiv, Schneider Electric, Trane Technologies and Carrier hold about 48% of 2025 spend, in DC Market Insights estimates. SK Enmove and GRC lead immersion cooling with LG.
The Capital Region with 66.00% (USD 235.70 million) in 2025. The Honam Region grows fastest at 19.72% a year as AI campuses move to Jeollanam-do.
Liquid-based cooling rises from 16.00% of spend in 2025 to 40.00% by 2035, Korean groups build immersion supply chains, and chillers stay the largest line at USD 324.09 million in 2035.
Licences, delivery and payment
Which licence should I choose?
Single User is a view-only PDF for one person. Multi User adds a printable PDF and the Excel data for unlimited users at one location. Enterprise covers your whole company and includes 100 free analyst hours.
How and when will I receive the report?
By email, within 24–48 business hours of payment, in the formats of your licence.
How can I pay?
Securely through PayPal: with a PayPal account, a debit or credit card, or PayPal Pay Later where available. Prices are in US dollars.
Can I see a sample first?
Yes. Request a free sample and we will email it to you.
Can the report be tailored to my needs?
Yes. We can add countries, segments or data cuts. Talk to an analyst about the scope you need.
Can I get an invoice or pay against a purchase order?
Write to sales@dcmarketinsights.com and our team will help.