
Latin America Data Center Thermal Management Market Size, Share & Forecast to 2035
Market at a glance
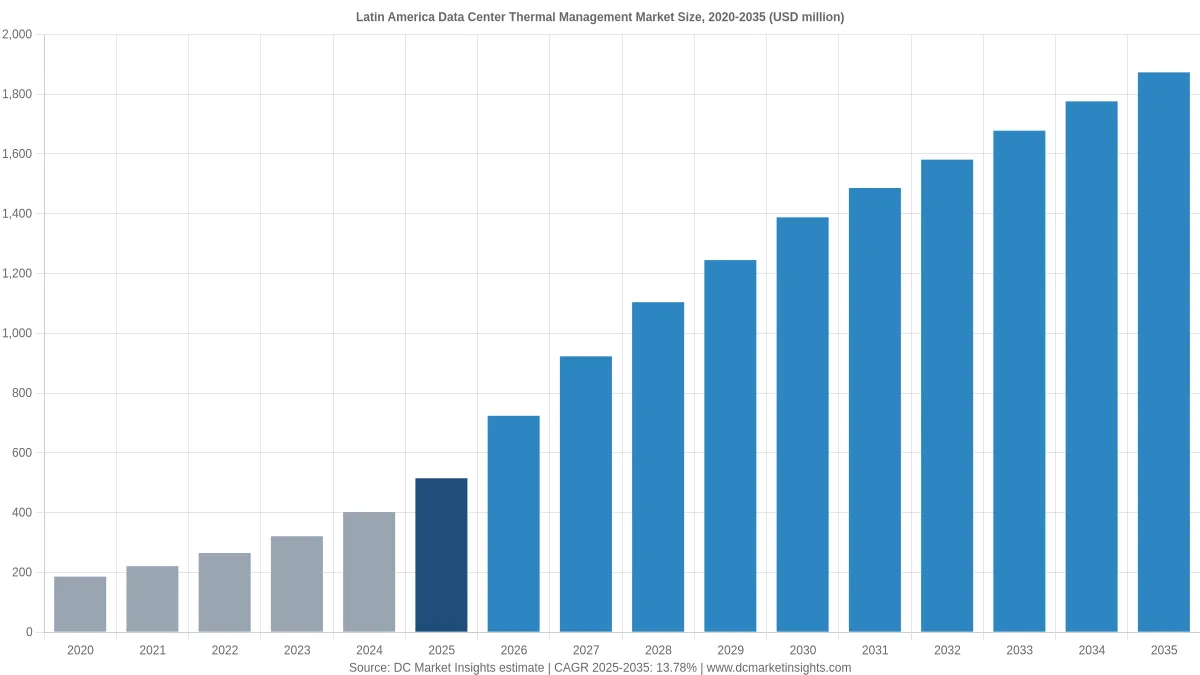
The Latin America Data Center Thermal Management market was worth USD 515.1 million in 2025 and is forecast to reach USD 1,870.0 million by 2035, growing at a 13.78% CAGR.
 By Amit Jain, Senior Consultant, ICT & Emerging Technologies
 Reviewed by Deepti Agrawal
Last updated 30 Oct 2026
Base year 2025 PDF + Excel
Key findings
REDATA's 0.05 L/kWh Water Limit Re-Prices Brazilian Cooling Plants
Waterless Cooling Becomes a Marketing Claim for AI Campuses
Water Stress in Northern Chile, Querétaro and São Paulo
Service Contracts on a 7.8 GW Operating Base
What is inside the report
- 01Key Market Statistics: How Big Is the Latin America Data Center Thermal Management Market in 2026?
- 02Key Takeaways: What Should Buyers of Data Center Cooling in Latin America Plan For?
- 03Latin America Data Center Thermal Management Market Summary: How Much Did the Region Spend on Data Center Heat Removal in 2025?
- 04What Does the Latin America Data Center Thermal Management Market Include?
- 05Why Do Latin America Data Center Thermal Management Market Estimates Differ?
- 06Market Drivers: Why Is Latin America Data Center Cooling Spending Rising?
- 07Market Trends: How Is Data Center Cooling in Latin America Changing?
- 08Market Challenges: What Holds Back Latin America Data Center Thermal Management Projects?
- 09Market Opportunities: Where Can Thermal Management Suppliers Win in Latin America?
- 10Pricing: How Much Does Data Center Thermal Management Cost per MW in Latin America?
- 19chapters
- 2020-2024Historical period
- 2026-2035Forecast period
- —Companies profiled
Segmentation
Recent developments
the ONS first access season of 2026 allocated 228 MW at the Replan 440 kV substation in São Paulo (Source: ONS).
Brazil enacted Law 15,504 (REDATA) with a 0.05 L/kWh WUE limit (Source: Chamber of Deputies, Brazil).
Google reported that it returned more water to Chile's Maipo basin than its Quilicura data center used in 2025 (Source: Google).
Uruguay's Presidency put Google's Canelones data center at about USD 850 million of total investment (Source: Presidency of Uruguay).
Vertiv installed liquid cooling training systems at its Barueri academy in São Paulo (Source: Vertiv).
Elea announced Rio AI City with waterless cooling and about 80 MW at RJO2 in 2026 (Source: Elea Data Centers).
Full analysis
The Latin America Data Center Thermal Management Market is valued at USD 724.48 million in 2026 and is projected to reach USD 1.87 billion by 2035, up from USD 515.10 million in 2025, a CAGR of 13.78% from 2025 to 2035 (DC Market Insights estimate). The money in this market is moved by water as much as by heat: Brazil’s Law 15,504 of 15 September 2026 (REDATA) grants its data center tax regime only to sites with a water usage effectiveness (WUE) of 0.05 litres per kWh or lower (Source: Chamber of Deputies, Brazil), which rules out open evaporative towers for most new Brazilian halls and shifts spending toward closed-loop chillers, dry coolers and direct-to-chip liquid loops. The 2025 receipt is 300 MW of new IT capacity × USD 1.34 million of thermal content per MW = USD 402.00 million of new build, plus 1,414 MW of operating IT load × USD 80 thousand a year = USD 113.10 million of maintenance, software and engineering (DC Market Insights estimate). Latin America data center thermal management covers the cooling plant, containment, temperature and humidity sensing, thermal software and the engineering that keeps IT equipment within its limits across Brazil, Mexico, the Southern Cone, the Andean countries and Central America. Immersion cooling is the fastest heat-removal method at 25.51% a year from a 3.00% base, and Brazil is the fastest region at 14.24% a year because the national grid operator ONS adds 2,157 MW of average data center load to its 2030 plan.
Key Market Statistics: How Big Is the Latin America Data Center Thermal Management Market in 2026?
The Latin America data center thermal management market is worth USD 724.48 million in 2026, 40.65% more than in 2025, according to DC Market Insights.
- Market size 2025: USD 515.10 million; 2026: USD 724.48 million; 2030: USD 1.39 billion; 2035: USD 1.87 billion.
- CAGR 2025-2035: 13.78% in the base case, 11.68% in the low case and 15.78% in the high case.
- Largest component: cooling equipment and installation, 75.50% of 2025 value.
- Fastest component: thermal monitoring software and sensors, 20.08% a year to 2035.
- Fastest heat-removal method: immersion cooling, 25.51% a year; direct-to-chip liquid cooling rises from 17.00% to 40.00% of value.
- Leading region: Brazil, 48.00% of 2025 value; it is also the fastest region at 14.24% a year.
- Largest country after Brazil: Mexico with 24.00% of 2025 value; fastest country: Uruguay at 19.26% a year.
- New IT capacity: 300 MW in 2025, 420 MW in 2026 and 800 MW in 2035 across the region.
- Market leader: Vertiv with about 17% of 2025 value (DC Market Insights estimate).
Key Takeaways: What Should Buyers of Data Center Cooling in Latin America Plan For?
Four facts frame Latin America data center thermal management spending to 2035, each with its reason.
- Spending rises 40.65% in 2026 because new IT capacity climbs from 300 MW to 420 MW as Elea’s RJO2 (about 80 MW) and other campuses energise.
- Liquid cooling (direct-to-chip plus immersion) rises from 20.00% to 48.00% of value because racks above 30 kW grow from 22.00% to 56.00% of value.
- Services and software together rise from 18.50% to 29.00% of value because the operating base grows from about 1.69 GW to 7.76 GW.
- Water rules, not only heat, decide the design, because REDATA’s 0.05 L/kWh WUE limit and Chile’s northern water stress penalise evaporative cooling.
Latin America Data Center Thermal Management Market Summary: How Much Did the Region Spend on Data Center Heat Removal in 2025?
The Latin America Data Center Thermal Management Market size was valued at USD 186.26 million in 2020, reached USD 515.10 million in 2025, and is anticipated to reach USD 1.87 billion by 2035, at a CAGR of 13.78% during the forecast period.
| Report Attribute | Details |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Latin America Data Center Thermal Management Market Size 2025 | USD 515.10 million |
| Latin America Data Center Thermal Management Market Size 2026 | USD 724.48 million |
| Latin America Data Center Thermal Management Market, CAGR | 13.78% (2025-2035) |
| Latin America Data Center Thermal Management Market Size 2035 | USD 1.87 billion |
Latin America data center thermal management spending grew 22.56% a year from 2020 to 2025 as new IT capacity rose from 120 MW to 300 MW a year, and it slows to 13.78% a year to 2035 as additions level off near 800 MW a year while the share of AI halls rises from 20% to 60% of new capacity (DC Market Insights estimate). Heat removal per new MW climbs from USD 1.16 million in 2020 to USD 1.53 million in 2030 because liquid-cooled AI halls carry about USD 1.90 million of thermal content per MW against USD 1.20 million for an air-cooled hall.
What Does the Latin America Data Center Thermal Management Market Include?
The Latin America data center thermal management market, worth USD 515.10 million in 2025, covers every product and service that removes data center heat (DC Market Insights estimate). That spans cooling plant, containment, sensing, software and thermal services.
Included
- Cooling equipment and its installation: chillers, dry coolers, computer room air handlers (CRAH), in-row coolers, rear-door heat exchangers, coolant distribution units (CDU), cold plates and immersion tanks.
- Airflow management and containment: hot-aisle and cold-aisle containment, blanking panels, raised-floor and ceiling airflow parts.
- Thermal monitoring software and sensors: temperature, humidity and leak sensors, thermal modules of data center infrastructure management (DCIM) and building management systems (BMS), computational fluid dynamics (CFD) studies.
- Thermal maintenance and engineering services: preventive maintenance, coolant management, retrofits and thermal design.
Excluded
- Server-level heat sinks and fans sold inside IT equipment.
- Power equipment (UPS, switchgear, generators) and the electricity used for cooling.
- Building shell, land and general construction; these sit in the Latin America Data Center Infrastructure Market.
- Comfort air conditioning in offices attached to data centers.
How the Segments Fit Together
The four segment views (component, heat removal method, facility type and rack density) each add up to the same USD 515.10 million 2025 total, and the five regions and twelve countries add up to it as well. The Latin America Data Center Market counts the full facility and IT spend; thermal management is a slice of it, and this edition counts only the heat-removal layer. Edge sites up to 5 MW are counted here only for their cooling content, which keeps the boundary with the Latin America Edge Data Center Market clean.
Why Do Latin America Data Center Thermal Management Market Estimates Differ?
Latin America data center thermal management estimates differ because some definitions add IT-side cooling and electricity, while DC Market Insights counts USD 724.48 million of facility-side heat removal in 2026.
The earlier DC Market Insights edition put 2025 at USD 1.28 billion because it applied a cooling share to total data center spending, including IT equipment; this edition builds the value bottom-up from 300 MW of new IT capacity and 1,414 MW of operating load, which gives USD 515.10 million. Broader definitions also add server fans and heat sinks, the electricity bill for cooling, comfort cooling, and cooling for telecom shelters and industrial control rooms. Those items can double a headline figure without a single extra MW of data center heat being removed. Small and medium enterprises that run server rooms are in scope through the enterprise and government and the edge segments.
| Element | In this report | Why |
|---|---|---|
| Chillers, dry coolers, CRAH, in-row and rear-door units | Yes | Core heat-removal plant of a data hall |
| CDUs, cold plates, immersion tanks | Yes | Liquid cooling for racks above 30 kW |
| Containment and airflow parts | Yes | Thermal performance of the room |
| Thermal sensors, DCIM thermal modules, CFD | Yes | Thermal control and reporting |
| Maintenance, retrofits, thermal engineering | Yes | Recurring spend on the operating base |
| Server heat sinks and fans | No | Sold inside IT equipment |
| Electricity for cooling | No | Operating cost, not equipment or service |
| Comfort cooling in offices | No | Not data center heat |
Market Drivers: Why Is Latin America Data Center Cooling Spending Rising?
Latin America data center thermal management spending rises 40.65% in 2026 because three forces arrive together. They are a water limit in Brazilian tax law, a grid plan that expects 2,157 MW of extra data center load and hyperscale regions in Chile and Mexico.
REDATA’s 0.05 L/kWh Water Limit Re-Prices Brazilian Cooling Plants
Brazil’s REDATA regime was created by Provisional Measure 1,318 on 17 September 2025 and became Law 15,504 of 15 September 2026, and it suspends federal taxes on data center equipment only for sites that buy 100% clean or renewable power, keep WUE at or below 0.05 L/kWh measured yearly and offer at least 10% of capacity to the domestic market (Source: Chamber of Deputies, Brazil). A WUE of 0.05 L/kWh is far below what open cooling towers use in a São Paulo summer, so a REDATA site needs closed-loop chillers, adiabatic dry coolers with a small water budget, or direct liquid cooling. DC Market Insights estimates that a REDATA-compliant air-cooled hall in São Paulo carries about USD 1.30 million of thermal content per MW, about 8% more than an evaporative design, and Brazil holds 48.00% of regional thermal spending in 2025.
ONS Plans for 2,157 MW of Extra Data Center Load in Brazil by 2030
The Brazilian grid operator ONS and the energy research company EPE added a data center scenario to their 2026-2030 load forecast that raises average load by 321 MW in 2026 and 2,157 MW in 2030, with 1,312 MW in the Southeast and Center-West and 716 MW in the Northeast (Source: ONS, April 2026). At a power usage effectiveness (PUE) of about 1.35, 2,157 MW of average load equals roughly 1.6 GW of IT load, which DC Market Insights reads as the Brazilian part of the regional additions that lift new IT capacity from 300 MW in 2025 to 700 MW in 2030. Each of those MW carries about USD 1.53 million of heat-removal content by 2030.
AWS Regions in Chile and Mexico Set an Air-First Design Standard
Amazon Web Services (AWS) launched its Mexico (Central) Region in Querétaro in January 2025 with more than USD 5 billion planned over 15 years and said the region is air-cooled with no ongoing cooling water (Source: Amazon). In May 2025 Amazon published an investment plan for Chile of more than USD 4 billion, with an AWS Region due by the end of 2026 that is mostly air-cooled (Source: Amazon). Mexico and the Southern Cone together hold 39.00% of 2025 thermal spending, and the air-first specification keeps perimeter and in-row air cooling at 71.00% of regional value in 2025.
Market Trends: How Is Data Center Cooling in Latin America Changing?
Liquid cooling rises from 20.00% of Latin America data center thermal value in 2025 to 48.00% in 2035 (DC Market Insights estimate). Designs move from evaporative towers and perimeter air toward waterless and liquid loops.
Waterless Cooling Becomes a Marketing Claim for AI Campuses
Elea Data Centers said in its May 2025 Rio AI City announcement that the campus will use cooling systems that eliminate water use, with RJO2 delivering about 80 MW in 2026 and RJO3 and RJO4 adding 120 MW more, inside a first phase of 1.5 GW (Source: Elea Data Centers). Google said in September 2026 that it returned more water to the Maipo basin than its Quilicura data center in Chile used in 2025 and is funding a USD 1.2 million canal project (Source: Google). Waterless claims push buyers toward dry coolers and closed liquid loops that cost about 5-10% more per MW but use almost no water.
Liquid Cooling Skills Arrive Through Vendor Training Centres
Vertiv said in November 2025 that its Vertiv Academy in Barueri, São Paulo, installed the region’s first AI liquid cooling thermal management solutions for training (Source: Vertiv). DC Market Insights counts direct-to-chip liquid cooling at 17.00% of Latin American thermal value in 2025, below the share in the United States, because few local technicians had worked on CDUs and cold plates before 2025.
Gigawatt Campuses Shift Cooling Orders to Long Framework Contracts
Brazil’s Ministry of Mines and Energy (MME) approved a grid reservation for Scala AI City in Eldorado do Sul, Rio Grande do Sul, with an initial IT capacity of 54 MW, an initial investment of BRL 3 billion and a planned build-out of 4.75 GW (Source: Government of Rio Grande do Sul, May 2025). Campuses of this size buy cooling in multi-phase framework contracts, which favour suppliers with local assembly and service teams.
Market Challenges: What Holds Back Latin America Data Center Thermal Management Projects?
Water stress and grid queues that delay 20-30% of planned MW by a year or more hold back Latin America data center thermal management (DC Market Insights estimate). Both bite hardest in the largest hubs.
Water Stress in Northern Chile, Querétaro and São Paulo
The committee of Chile’s national data center plan recorded in September 2025 that cooling accounts for 30% to 40% of data center energy use and that water is the main challenge in the north of the country (Source: Ministry of Science, Chile). Water limits raise the thermal bill per MW by about USD 0.10 million where dry coolers replace towers, and they push some projects to cooler southern sites, which slows the first year of spending.
Grid Queues Delay Cooling Orders
In the first ONS access season of 2026, a competitive process held on 6 October 2026 allocated 228 MW at the Replan 440 kV substation in São Paulo while one large applicant was not served, at an average winning premium of BRL 817.15 per kW (Source: ONS, October 2026). Cooling orders follow the energisation date, so every quarter of grid delay moves about 25% of a year’s new-build thermal spend into the next year; DC Market Insights models this as part of the gap between the low and the base case.
Market Opportunities: Where Can Thermal Management Suppliers Win in Latin America?
Service contracts and direct-to-chip retrofits are the largest Latin America data center thermal management opportunities, as the operating base grows to 7.76 GW by 2035. Retrofits help lift liquid cooling to 48.00% of value in 2035 (DC Market Insights estimate).
Service Contracts on a 7.8 GW Operating Base
Maintenance and engineering services rise from 15.00% to 23.00% of value by 2035 because the operating IT base grows from 1,693 MW to 7,756 MW, and every operating MW carries about USD 80 thousand to USD 88 thousand a year of thermal service, software and engineering.
Direct-to-Chip Retrofits in Colocation Halls
Colocation facilities hold 30.00% of 2025 value, and many halls built for 8-15 kW racks now take AI tenants at 40-130 kW per rack. Converting one 2 MW hall to direct-to-chip cooling with a CDU and a dry-cooler loop costs about USD 0.9 million per MW (DC Market Insights estimate), which is why direct-to-chip liquid cooling rises to 40.00% of value by 2035.
Pricing: How Much Does Data Center Thermal Management Cost per MW in Latin America?
Data center thermal management in Latin America costs about USD 1.20 million per MW for air-cooled halls and USD 1.90 million for liquid-cooled AI halls in 2025. Service adds about USD 80 thousand per operating MW a year (DC Market Insights estimate).
| Year | Air-cooled hall (USD million per MW) | Liquid-cooled AI hall (USD million per MW) | Blended new-build content (USD million per MW) | Service and software (USD thousand per operating MW-year) |
|---|---|---|---|---|
| 2020 | 1.14 | 2.00 | 1.16 | 76.1 |
| 2025 | 1.20 | 1.90 | 1.34 | 80.0 |
| 2030 | 1.26 | 1.81 | 1.53 | 84.1 |
| 2035 | 1.33 | 1.72 | 1.56 | 88.4 |
Public anchors support the range: the MinCiencia guide for data center investors in Chile counts more than USD 2.3 billion of data center projects built from 2020 to 2024 and more than USD 4 billion in development (Source: Ministry of Science, Chile), and cooling plant usually takes 12-18% of a hall’s facility budget. Liquid-cooled AI content per MW falls about 1% a year as CDU and cold-plate volumes rise, while air-cooled content rises about 1% a year with stricter efficiency and water rules.
Standards and Regulation: Which Rules Shape Data Center Cooling in Latin America?
Four rules shape data center cooling in Latin America, led by Brazil’s REDATA water limit of 0.05 L/kWh that applies to a market holding 48.00% of regional thermal value.
- Brazil, Law 15,504 of 15 September 2026 (REDATA): WUE of 0.05 L/kWh or lower, 100% clean or renewable electricity, 10% of capacity for the domestic market and 2% of benefited goods invested in research (Source: Chamber of Deputies, Brazil).
- Brazil, Provisional Measure 1,318 of 17 September 2025: first version of REDATA with the same water and energy conditions (Source: Presidency of Brazil).
- Chile, National Data Center Plan (PDATA) of the Ministry of Science: investor guide of June 2025 and committee minutes of September 2025 that flag water use for cooling (Source: Ministry of Science, Chile).
- ASHRAE thermal guidelines for data processing environments, used across the region to set allowable inlet temperatures (Source: ASHRAE).
- Refrigerant phase-down under the Kigali Amendment to the Montreal Protocol, ratified by Mexico and Chile, which moves chiller orders toward lower-GWP refrigerants (Source: United Nations Environment Programme).
Market Segmentation: Which Latin America Data Center Thermal Management Segment Leads?
Cooling equipment and installation leads the Latin America data center thermal management market with 75.50% of 2025 value, while immersion cooling grows fastest at 25.51% a year (DC Market Insights estimate).
By Component
Thermal monitoring software and sensors grow fastest at 20.08% a year because REDATA’s yearly WUE measurement and operator PUE reporting need metered data.
| Component | 2025 (USD) | Share 2025 | 2035 (USD) | CAGR 2025-2035 |
|---|---|---|---|---|
| Cooling Equipment and Installation | 388.90 million | 75.50% | 1.25 billion | 12.34% |
| Airflow Management and Containment | 30.91 million | 6.00% | 84.28 million | 10.55% |
| Thermal Monitoring Software and Sensors | 18.03 million | 3.50% | 112.38 million | 20.08% |
| Thermal Maintenance and Engineering Services | 77.27 million | 15.00% | 430.79 million | 18.75% |
By Heat Removal Method
Perimeter and in-row air cooling keeps the largest share in 2025 at 71.00%, while direct-to-chip liquid cooling reaches 40.00% of value by 2035.
| Heat Removal Method | 2025 (USD) | Share 2025 | 2035 (USD) | CAGR 2025-2035 |
|---|---|---|---|---|
| Perimeter and In-Row Air Cooling | 365.72 million | 71.00% | 786.66 million | 7.96% |
| Rear-Door Heat Exchangers | 46.36 million | 9.00% | 187.30 million | 14.98% |
| Direct-to-Chip Liquid Cooling | 87.57 million | 17.00% | 749.20 million | 23.94% |
| Immersion Cooling | 15.45 million | 3.00% | 149.84 million | 25.51% |
By Facility Type
Hyperscale and AI campuses grow from 46.00% to 58.00% of value as Rio AI City, Scala AI City and the AWS regions fill.
| Facility Type | 2025 (USD) | Share 2025 | 2035 (USD) | CAGR 2025-2035 |
|---|---|---|---|---|
| Hyperscale and AI Campuses | 236.95 million | 46.00% | 1.09 billion | 16.45% |
| Colocation Facilities | 154.53 million | 30.00% | 468.25 million | 11.72% |
| Enterprise and Government | 82.42 million | 16.00% | 168.57 million | 7.42% |
| Edge Sites | 41.21 million | 8.00% | 149.84 million | 13.78% |
By Rack Density
Racks above 80 kW grow fastest at 30.70% a year, from 5.00% of 2025 value, because GPU racks for AI training arrive in Brazil and Mexico.
| Rack Density | 2025 (USD) | Share 2025 | 2035 (USD) | CAGR 2025-2035 |
|---|---|---|---|---|
| Below 10 kW per Rack | 206.04 million | 40.00% | 262.22 million | 2.44% |
| 10 to 30 kW per Rack | 195.74 million | 38.00% | 561.90 million | 11.12% |
| 30 to 80 kW per Rack | 87.57 million | 17.00% | 674.28 million | 22.64% |
| Above 80 kW per Rack | 25.76 million | 5.00% | 374.60 million | 30.70% |
DC Exclusive: The REDATA Water-Limit Cooling Ladder, 5 Hall Designs in São Paulo
Only 3 of 5 common São Paulo hall designs meet REDATA’s 0.05 L/kWh water limit, according to the REDATA Water-Limit Cooling Ladder. The ladder is a DC Market Insights model built on 6 inputs: capex per MW, annual water use, design PUE, São Paulo climate hours, electricity price and the REDATA limit.
| Hall design (São Paulo, 10 MW IT) | Thermal capex (USD million per MW) | Typical WUE (L/kWh) | Design PUE | Meets REDATA 0.05 L/kWh? |
|---|---|---|---|---|
| Open cooling towers + water-cooled chillers | 1.10 | 1.20-1.80 | 1.30 | No |
| Adiabatic dry coolers + air-cooled chillers | 1.25 | 0.10-0.30 | 1.38 | Only with water caps |
| Air-cooled chillers with free cooling, closed loop | 1.30 | 0.00-0.02 | 1.42 | Yes |
| Direct-to-chip loop (70%) + dry coolers + residual air | 1.85 | 0.00-0.03 | 1.22 | Yes |
| Single-phase immersion + dry coolers | 2.05 | 0.00-0.01 | 1.12 | Yes |
The ladder shows the trade buyers face: the cheapest design per MW fails the water test, and the qualifying designs cost USD 0.20 million to USD 0.95 million more per MW, but direct-to-chip and immersion recover part of that through PUE 0.20 lower, worth about USD 0.17 million per MW a year at USD 100 per MWh. DC Market Insights uses this ladder to set the air-cooled content of USD 1.20-1.30 million per MW and the liquid content of USD 1.90 million per MW in the model.
Regional Insights: Which Latin American Country Spends Most on Data Center Thermal Management?
Brazil spends most on data center thermal management in Latin America, 48.00% of 2025 value, and grows fastest at 14.24% a year. REDATA and the ONS load plan bring gigawatt campuses to São Paulo, Rio de Janeiro and Rio Grande do Sul.
| Region | 2025 (USD) | Share 2025 | 2035 (USD) | CAGR 2025-2035 |
|---|---|---|---|---|
| Brazil | 247.25 million | 48.00% | 936.50 million | 14.24% |
| Mexico | 123.62 million | 24.00% | 412.06 million | 12.79% |
| Southern Cone | 77.27 million | 15.00% | 290.31 million | 14.15% |
| Andean Countries | 46.36 million | 9.00% | 159.21 million | 13.13% |
| Central America and Caribbean | 20.60 million | 4.00% | 74.92 million | 13.78% |
Brazil
Brazil’s share rises from 48.00% to 50.00% because ONS expects 1,312 MW of extra average data center load in the Southeast and Center-West by 2030 and Elea’s RJO2 adds about 80 MW in Rio de Janeiro in 2026.
Mexico
Mexico holds 24.00% of 2025 value, centred on Querétaro, where the AWS Mexico (Central) Region opened in January 2025 with an air-cooled design and more than USD 5 billion planned over 15 years.
Southern Cone
The Southern Cone (Chile, Argentina and Uruguay) holds 15.00% of 2025 value and grows 14.15% a year; Uruguay’s Presidency said in April 2026 that Google’s Canelones data center involves about USD 850 million of total investment (Source: Presidency of Uruguay).
Andean Countries
Colombia, Peru and Ecuador hold 9.00% of 2025 value, with Bogotá and Lima colocation halls that still rely mainly on perimeter air cooling at racks below 15 kW.
Central America and Caribbean
Panama, Costa Rica, the Dominican Republic and smaller markets hold 4.00% of 2025 value, where hot and humid climates keep chiller run hours high all year.
Country Analysis: Which Countries Carry the Most Latin America Data Center Thermal Spending?
Brazil and Mexico together carry 72.00% of Latin America data center thermal management value in 2025, and Uruguay is the fastest country at 19.26% a year.
| Rank | Country | Region | 2025 (USD) | 2035 (USD) | CAGR 2025-2035 |
|---|---|---|---|---|---|
| 1 | Brazil | Brazil | 247.25 million | 936.50 million | 14.24% |
| 2 | Mexico | Mexico | 123.62 million | 412.06 million | 12.79% |
| 3 | Chile | Southern Cone | 54.09 million | 187.30 million | 13.22% |
| 4 | Colombia | Andean Countries | 28.33 million | 99.27 million | 13.36% |
| 5 | Argentina | Southern Cone | 12.88 million | 43.08 million | 12.83% |
| 6 | Peru | Andean Countries | 12.88 million | 44.95 million | 13.31% |
| 7 | Uruguay | Southern Cone | 10.30 million | 59.94 million | 19.26% |
| 8 | Panama | Central America and Caribbean | 9.27 million | 33.71 million | 13.78% |
| 9 | Costa Rica | Central America and Caribbean | 6.18 million | 22.48 million | 13.78% |
| 10 | Ecuador | Andean Countries | 5.15 million | 14.98 million | 11.27% |
| 11 | Dominican Republic | Central America and Caribbean | 3.09 million | 11.24 million | 13.78% |
| 12 | Other Latin America | Central America and Caribbean | 2.06 million | 7.49 million | 13.78% |
Among the larger countries, Colombia grows fastest at 13.36% a year as Bogotá colocation halls add higher-density suites, while Chile grows 13.22% a year as the AWS Region and more than 30 projects counted by the Ministry of Science come online.
Forecast Scenarios: How Could Latin America Data Center Thermal Management Look in 2035?
By 2035, Latin America data center thermal management reaches USD 1.87 billion in the base case, within a range of USD 1.55 billion to USD 2.23 billion (DC Market Insights estimate).
| Scenario | 2035 value (USD) | CAGR 2025-2035 | Assumption |
|---|---|---|---|
| Low | 1.55 billion | 11.68% | Grid queues delay 20% of planned MW; AI share of new capacity stays near 45% |
| Base | 1.87 billion | 13.78% | New IT capacity reaches 800 MW a year; AI share 60% of new MW by 2035 |
| High | 2.23 billion | 15.78% | Rio AI City and Scala AI City phases arrive on time; AI share 70% |
Key Players: Who Supplies Data Center Thermal Management in Latin America?
Vertiv leads Latin America data center thermal management with about 17% of 2025 value (DC Market Insights estimate). The top three suppliers, Vertiv, Schneider Electric and Stulz, hold about 36%, based on DC Market Insights estimates of installed cooling units and service contracts.
- Vertiv
- Schneider Electric
- Stulz
- Trane Technologies
- Carrier
- Johnson Controls
- Daikin
- Rittal
- Mitsubishi Electric
- LG Electronics
- Delta Electronics
- nVent
- Modine (Airedale)
- CoolIT Systems
- Munters
Vertiv announced in March 2026 an expansion of its Mexicali, Mexico, plant expected to raise regional manufacturing capacity by about 45%, for power equipment rather than cooling (Source: Vertiv), and in March 2026 it reported a regional recognition for its Latin American AI and high-performance computing infrastructure business (Source: Vertiv). Schneider Electric and Stulz compete on chillers, CRAH and CDUs, while Trane Technologies, Carrier and Johnson Controls supply large central plants to hyperscale campuses.
Recent Developments: What Changed in Latin American Data Center Cooling Since 2025?
Six dated developments since 2025 changed Latin America data center thermal management, led by Brazil’s REDATA law of September 2026.
- In October 2026, the ONS first access season of 2026 allocated 228 MW at the Replan 440 kV substation in São Paulo (Source: ONS).
- In September 2026, Brazil enacted Law 15,504 (REDATA) with a 0.05 L/kWh WUE limit (Source: Chamber of Deputies, Brazil).
- In September 2026, Google reported that it returned more water to Chile’s Maipo basin than its Quilicura data center used in 2025 (Source: Google).
- In April 2026, Uruguay’s Presidency put Google’s Canelones data center at about USD 850 million of total investment (Source: Presidency of Uruguay).
- In November 2025, Vertiv installed liquid cooling training systems at its Barueri academy in São Paulo (Source: Vertiv).
- In May 2025, Elea announced Rio AI City with waterless cooling and about 80 MW at RJO2 in 2026 (Source: Elea Data Centers).
Methodology: How the Model Values the Latin America Data Center Thermal Management Market
DC Market Insights values the Latin America data center thermal management market at USD 515.10 million in 2025 with a bottom-up model of 16 years, 5 regions and 12 countries. In that model, 300 MW of new IT capacity and 1,414 MW of operating load give the 2025 value.
New-build value = new IT MW × (air-cooled share × USD 1.20 million per MW + AI share × USD 1.90 million per MW), with AI share rising from 20% in 2025 to 60% in 2035; operating value = prior-year installed IT MW × USD 80 thousand per MW-year, rising 1% a year; installed capacity retires 1.5% a year. The model reconciles 15 dated facts and 6 ladder inputs; segment, region and country splits add to the total in 2025 and 2035. See the research methodology for the house approach and the Data Center Thermal Management Market for the global view.
- Bound 1 (ceiling): 2025 new-build thermal value of USD 402.00 million is about 15% of an estimated USD 2.7 billion of facility spending on 300 MW at USD 9 million per MW, inside the usual 12-18% cooling share.
- Bound 2 (ceiling): 2030 Brazilian new IT capacity in the model, 50% of 700 MW, is below the roughly 1.6 GW of IT load implied by ONS’s 2,157 MW of extra average data center load in 2030.
- Bound 3 (floor): Chile’s more than USD 4 billion of data center projects in development at a 12% cooling share gives about USD 480 million of future thermal spend, above Chile’s modelled new-build thermal value for 2026-2028.
Table of contents
- 01Key Market Statistics: How Big Is the Latin America Data Center Thermal Management Market in 2026?
- 1.1Market Snapshot, 2025, 2026 and 2035
- 02Key Takeaways: What Should Buyers of Data Center Cooling in Latin America Plan For?
- 2.1Spending Growth in 2026
- 2.2Liquid Cooling Share, 2025 and 2035
- 2.3Services and Software on the Operating Base
- 2.4Water Rules and Cooling Design
- 03Latin America Data Center Thermal Management Market Summary: How Much Did the Region Spend on Data Center Heat Removal in 2025?
- 3.1Market Snapshot Attributes and Size, 2020-2035
- 04What Does the Latin America Data Center Thermal Management Market Include?
- 4.1Included
- 4.2Excluded
- 4.3How the Segments Fit Together
- 05Why Do Latin America Data Center Thermal Management Market Estimates Differ?
- 5.1Scope Comparison: In and Out of This Report
- 06Market Drivers: Why Is Latin America Data Center Cooling Spending Rising?
- 6.1REDATA's 0.05 L/kWh Water Limit Re-Prices Brazilian Cooling Plants
- 6.2ONS Plans for 2,157 MW of Extra Data Center Load in Brazil by 2030
- 6.3AWS Regions in Chile and Mexico Set an Air-First Design Standard
- 07Market Trends: How Is Data Center Cooling in Latin America Changing?
- 7.1Waterless Cooling Becomes a Marketing Claim for AI Campuses
- 7.2Liquid Cooling Skills Arrive Through Vendor Training Centres
- 7.3Gigawatt Campuses Shift Cooling Orders to Long Framework Contracts
- 08Market Challenges: What Holds Back Latin America Data Center Thermal Management Projects?
- 8.1Water Stress in Northern Chile, Querétaro and São Paulo
- 8.2Grid Queues Delay Cooling Orders
- 09Market Opportunities: Where Can Thermal Management Suppliers Win in Latin America?
- 9.1Service Contracts on a 7.8 GW Operating Base
- 9.2Direct-to-Chip Retrofits in Colocation Halls
- 10Pricing: How Much Does Data Center Thermal Management Cost per MW in Latin America?
- 10.1Thermal Content per MW, 2020-2035
- 11Standards and Regulation: Which Rules Shape Data Center Cooling in Latin America?
- 11.1Brazil, Law 15,504 of 15 September 2026 (REDATA)
- 11.2Brazil, Provisional Measure 1,318 of 17 September 2025
- 11.3Chile, National Data Center Plan (PDATA)
- 11.4ASHRAE Thermal Guidelines
- 11.5Kigali Amendment Refrigerant Phase-Down
- 12Market Segmentation: Which Latin America Data Center Thermal Management Segment Leads?
- 12.1By Component
- 12.2Cooling Equipment and Installation
- 12.3Airflow Management and Containment
- 12.4Thermal Monitoring Software and Sensors
- 12.5Thermal Maintenance and Engineering Services
- 12.6By Heat Removal Method
- 12.7Perimeter and In-Row Air Cooling
- 12.8Rear-Door Heat Exchangers
- 12.9Direct-to-Chip Liquid Cooling
- 12.10Immersion Cooling
- 12.11By Facility Type
- 12.12Hyperscale and AI Campuses
- 12.13Colocation Facilities
- 12.14Enterprise and Government
- 12.15Edge Sites
- 12.16By Rack Density
- 12.17Below 10 kW per Rack
- 12.1810 to 30 kW per Rack
- 12.1930 to 80 kW per Rack
- 12.20Above 80 kW per Rack
- 13DC Exclusive: The REDATA Water-Limit Cooling Ladder, 5 Hall Designs in São Paulo
- 13.1Five Hall Designs Against the 0.05 L/kWh Limit
- 14Regional Insights: Which Latin American Country Spends Most on Data Center Thermal Management?
- 14.1Brazil
- 14.2Mexico
- 14.3Southern Cone
- 14.4Andean Countries
- 14.5Central America and Caribbean
- 15Country Analysis: Which Countries Carry the Most Latin America Data Center Thermal Spending?
- 15.1Brazil
- 15.2Mexico
- 15.3Chile
- 15.4Colombia
- 15.5Argentina
- 15.6Peru
- 15.7Uruguay
- 15.8Panama
- 15.9Costa Rica
- 15.10Ecuador
- 15.11Dominican Republic
- 15.12Other Latin America
- 16Forecast Scenarios: How Could Latin America Data Center Thermal Management Look in 2035?
- 16.1Low Case
- 16.2Base Case
- 16.3High Case
- 17Key Players: Who Supplies Data Center Thermal Management in Latin America?
- 17.1Vertiv
- 17.2Schneider Electric
- 17.3Stulz
- 17.4Trane Technologies
- 17.5Carrier
- 17.6Johnson Controls
- 17.7Daikin
- 17.8Rittal
- 18Recent Developments: What Changed in Latin American Data Center Cooling Since 2025?
- 18.1October 2026: ONS Access Season Allocates 228 MW
- 18.2September 2026: Brazil Enacts Law 15,504 (REDATA)
- 18.3September 2026: Google Maipo Basin Water Report
- 18.4April 2026: Google Canelones Investment, Uruguay
- 18.5November 2025: Vertiv Liquid Cooling Training, Barueri
- 18.6May 2025: Elea Rio AI City
- 19Methodology: How the Model Values the Latin America Data Center Thermal Management Market
- 19.1Bound 1 (ceiling)
- 19.2Bound 2 (ceiling)
- 19.3Bound 3 (floor)
- Fig. 1Latin America Data Center Thermal Management Market Size, 2020-2035
- Table 1Market Snapshot Attributes
- Table 2Scope Comparison
- Table 3Thermal Content per MW, 2020-2035
- Table 4Market by Component, 2025 and 2035
- Table 5Market by Heat Removal Method, 2025 and 2035
- Table 6Market by Facility Type, 2025 and 2035
- Table 7Market by Rack Density, 2025 and 2035
- Table 8REDATA Water-Limit Cooling Ladder
- Table 9Market by Region, 2025 and 2035
- Table 10Top 12 Countries, 2025 and 2035
- Table 11Forecast Scenarios, 2035
About this report
Written by Amit Jain and reviewed by Deepti Agrawal, Senior Editor, Research. Figures are built top-down and bottom-up and reconciled before publication, with 2025 as the base year.
Read our methodologyHow we built this
- Historical period2020-2024
- Base year2025
- Forecast period2026-2035
- Sizing approachTop-down + bottom-up
Need more than the report?
Advisory on this market
Due diligence, site selection and market entry work, by the analysts who wrote this report.
See consulting servicesFrequently asked questions
USD 724.48 million in 2026, up 40.65% from USD 515.10 million in 2025, according to DC Market Insights estimates. The market is projected to reach USD 1.87 billion by 2035, a CAGR of 13.78% from 2025.
USD 515.10 million: 300 MW of new IT capacity × USD 1.34 million of thermal content per MW plus 1,414 MW of operating load × USD 80 thousand a year, according to DC Market Insights.
REDATA sets a water usage effectiveness of 0.05 L/kWh or lower for tax relief, which rules out open cooling towers and favours closed-loop chillers, dry coolers and liquid cooling, adding about 8% to thermal cost per MW.
Brazil, with 48.00% of 2025 value, growing 14.24% a year as ONS plans for 2,157 MW of extra data center load by 2030.
Immersion cooling, at 25.51% a year to 2035; direct-to-chip liquid cooling grows from 17.00% to 40.00% of value as racks above 30 kW spread.
About USD 1.20 million per MW for an air-cooled hall and USD 1.90 million per MW for a liquid-cooled AI hall in 2025, plus about USD 80 thousand per operating MW a year (DC Market Insights estimate).
Vertiv leads with about 17% of 2025 value; Vertiv, Schneider Electric and Stulz together hold about 36%, followed by Trane Technologies, Carrier, Johnson Controls and Daikin (DC Market Insights estimate).
Uruguay, at 19.26% a year to 2035, as Google’s Canelones data center with about USD 850 million of investment comes online.
Broader definitions add server fans, heat sinks, cooling electricity and comfort cooling; DC Market Insights counts only facility-side heat removal, USD 724.48 million in 2026, built from MW of IT capacity.
USD 1.87 billion in the base case, between USD 1.55 billion and USD 2.23 billion in the low and high cases, as new IT capacity reaches 800 MW a year (DC Market Insights estimate).
Get this report
How do I get the full report?
Request a quote; we reply by email within one business day.
How and when will I receive the report?
By email, within 24-48 business hours of payment.
How can I pay?
Once you accept the quote, we email you a secure payment link.
Can I see a sample first?
Yes. Request a free sample and we will email it to you.
Can the report be tailored to my needs?
Yes. We can add countries, segments or data cuts. Talk to an analyst about the scope you need.
Can I get an invoice or pay against a purchase order?
Write to sales@dcmarketinsights.com and our team will help.