
Turkey Data Center Infrastructure Market Size, Share & Forecast to 2035
Market at a glance
The Turkey Data Center Infrastructure market was worth USD 419.1 million in 2025 and is forecast to reach USD 1,740.0 million by 2035, growing at a 15.3% CAGR.
 By Amit Jain, Senior Consultant, ICT & Emerging Technologies
 Reviewed by Deepti Agrawal
Last updated 18 Oct 2026
Base year 2025 PDF + Excel
What is inside the report
- 01Introduction
- 02Market Snapshot
- 03Executive Summary
- 04Market Scope
- 05Scope Comparison
- 06Market Drivers
- 07Market Trends
- 08Market Restraints
- 09Market Opportunities
- 10Pricing
- 19chapters
- 2020-2024Historical period
- 2026-2035Forecast period
- —Companies profiled
Segmentation
Full analysis
The Turkey Data Center Infrastructure Market is valued at USD 679.28 million in 2026 and is projected to reach USD 1.74 billion by 2035, up from USD 419.12 million in 2025, a CAGR of 15.30% from 2025 to 2035 (DC Market Insights estimate). Ankara, not Istanbul, now sets the pace: about 222 MW of named projects sit in the capital and its organised industrial zones, and Turkey’s Artificial Intelligence Vision and Action Plan (Invest in Türkiye Office, June 2026) targets at least 1 GW of data center capacity by 2030. According to the Ministry of Industry and Technology, its High-Impact Technology investment programme (HIT-30) data center call of October 2025 only funds halls of 30 MW of IT load or more with a power usage effectiveness (PUE) no higher than 1.4, which pushes buyers towards larger switchgear, medium-voltage substations and chilled-water or liquid-ready cooling. Turkey Data Center Infrastructure covers the physical facility layers inside Turkish data centers: electrical, mechanical and cooling, civil, structural and architectural works, and racks, cabling and physical network. The 2025 receipt is 30 MW of new IT load × USD 8.60 million of facility content per MW = USD 258.00 million, plus USD 136.50 million of upgrades across a 325 MW average installed base and USD 24.62 million of racks and cabling. Mechanical and cooling infrastructure grows fastest at 18.15% a year because AI halls need more heat rejection per MW, and Ankara and Central Anatolia is the fastest region at 19.52% a year as hyperscale and sovereign projects cluster there.
How Large Is Turkey’s Data Center Infrastructure Spend in 2026?
DC Market Insights values Turkey’s data center infrastructure spend at USD 679.28 million in 2026, 62.07% above the USD 419.12 million of 2025, because new IT completions almost double from 30 MW to 55 MW.
- 2025 size: USD 419.12 million (DC Market Insights estimate).
- 2026 size: USD 679.28 million.
- 2030 size: USD 1.34 billion.
- 2035 size: USD 1.74 billion.
- CAGR 2025-2035: 15.30% in the base case; 2035 low case USD 1.28 billion, high case USD 2.12 billion.
- Largest infrastructure type: electrical infrastructure, USD 159.77 million in 2025 (38.1%).
- Fastest infrastructure type: mechanical and cooling infrastructure, 18.15% a year.
- Leading region: Istanbul and Marmara, 52.0% of 2025 spend (USD 217.94 million).
- Fastest region: Ankara and Central Anatolia, 19.52% a year; fastest hub: Ankara Başkent OSB and Temelli, 22.60% a year.
- Largest hub: Istanbul Asian side (Ümraniye, Dudullu), USD 78.46 million in 2025.
- Market leader: Schneider Electric, with an estimated 11% of 2025 equipment value (DC Market Insights estimate).
Key Takeaways: What Should Buyers of Turkish Data Center Infrastructure Know?
Four findings carry the Turkey Data Center Infrastructure Market forecast, each with its figure and the reason behind it.
- Turkey data center infrastructure new-build spend jumps 86.28% in 2026 (DC Market Insights estimate), from USD 274.50 million to USD 511.34 million, because 55 MW of new IT load reaches completion as Turkcell’s Ankara modules and the first 9.6 MW phase of the Ankara Data Hub come online.
- Ankara and Central Anatolia rises from 30.0% to 43.0% of spend by 2035, because the Khazna, Turkcell-Google and Türk Telekom campuses all sit in Başkent OSB or the capital, away from Istanbul’s fault zones.
- Cooling’s share climbs from 20.2% to 25.8% of spend by 2035, because the HIT-30 PUE cap of 1.4 and AI racks force chilled-water plant and liquid-ready loops into every new hall.
- Upgrades of the installed base reach USD 678.00 million by 2035, 39.0% of the market, because 340 MW of older enterprise and bank halls must meet Tier III resilience and the 2018 Turkish Building Earthquake Code.
What Is the Outlook for the Turkey Data Center Infrastructure Market to 2035?
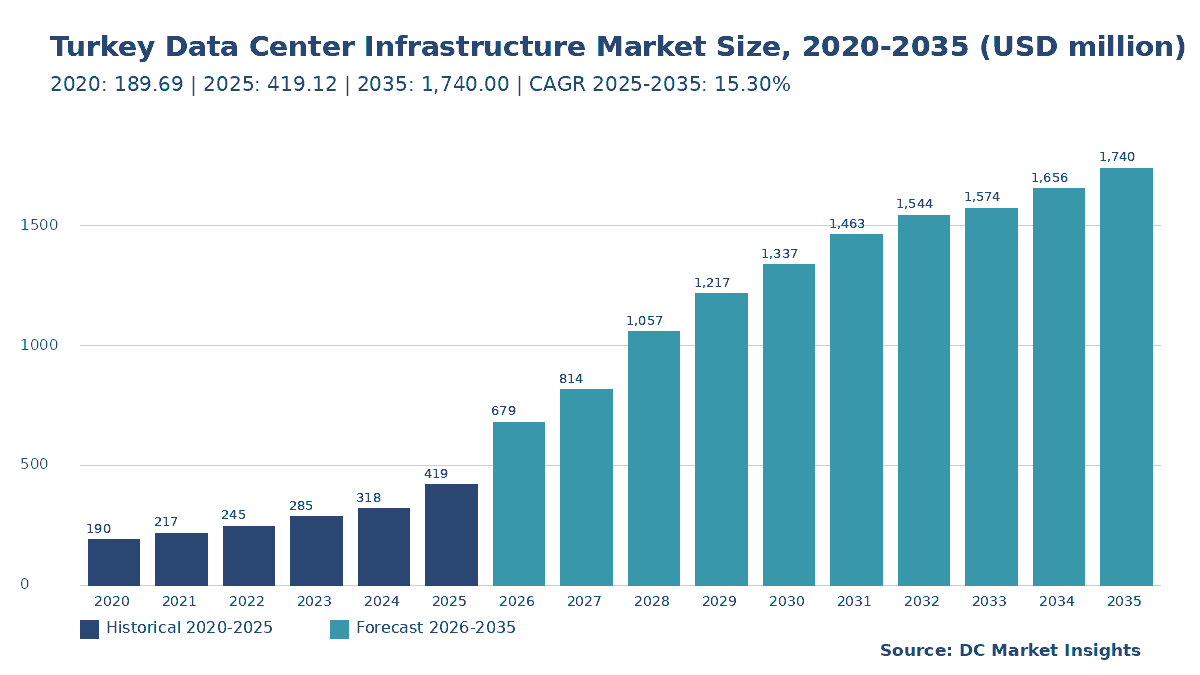
The Turkey Data Center Infrastructure Market size was valued at USD 189.69 million in 2020, reached USD 419.12 million in 2025, and is anticipated to reach USD 1.74 billion by 2035, at a CAGR of 15.30% during the forecast period.
| Attribute | Value |
|---|---|
| Historical period | 2020-2024 |
| Base year | 2025 |
| Forecast period | 2026-2035 |
| Market size 2025 | USD 419.12 million |
| Market size 2026 | USD 679.28 million |
| CAGR 2025-2035 | 15.30% |
| Market size 2035 | USD 1.74 billion |
Growth from 2020 to 2025 ran at 17.18% a year as installed IT load rose from 240 MW to 340 MW. DC Market Insights expects a second, steeper step from 2026 to 2030, when 400 MW of new IT load lifts annual spend to USD 1.34 billion, before growth slows to 5.41% a year after 2030 as completions settle at about 100 MW a year. The electrical, mechanical and civil lines match the power, cooling and construction lines of the Turkey Data Center Market report exactly, so the Turkey Data Center Infrastructure Market is the facility layer of that market: USD 419.12 million is 30.97% of the USD 1.35 billion parent total in 2025 and 38.41% of USD 4.53 billion in 2035.
What Does Turkey Data Center Infrastructure Include, and Where Is the Boundary?
Turkey data center infrastructure covers USD 419.12 million of 2025 spend on the physical plant that houses, powers and cools IT equipment in Turkish data centers.
Included
Electrical infrastructure (utility connection inside the fence, medium-voltage switchgear, transformers, uninterruptible power supply (UPS) systems, batteries, generators, busways and power distribution units); mechanical and cooling infrastructure (chillers, computer room air handlers, in-row and rear-door units, containment, pumps and piping, liquid-cooling distribution); civil, structural and architectural works (foundations, seismic isolation, frames, envelopes, raised floors, fire detection and suppression, physical security); and racks, cabling and physical network (cabinets, containment trays, structured copper and fibre). Both new halls and upgrades of operating halls are counted.
Excluded
Servers, storage and switches (part of the Turkey Data Center Market IT line and the Turkey Data Center Storage Market), land, electricity, transmission grid reinforcement by TEİAŞ (Turkish Electricity Transmission Corporation), colocation and cloud revenue, and facility management. Software that monitors the plant is covered in the Turkey Data Center Infrastructure Management (DCIM) Market, which values that software layer separately at a much smaller size.
How the segments fit together
Every year, infrastructure type, project type, data center type, tier and region each sum to the same total: USD 419.12 million in 2025 and USD 1.74 billion in 2035.
Why Do Turkey Data Center Infrastructure Estimates Differ So Much?
DC Market Insights puts the Turkey Data Center Infrastructure Market at USD 679.28 million in 2026, and broader figures for the same name usually add IT hardware worth more than twice the facility layer.
The earlier DC Market Insights edition counted servers, storage and networking equipment as infrastructure, which more than doubled its total. That IT line alone is worth USD 958.75 million in 2025 in the parent model, so adding it more than triples the figure. Other broad definitions also add land purchase, electricity bills, grid reinforcement and colocation rent, which are operating or real-estate costs rather than infrastructure equipment. DC Market Insights keeps them out so that the figure can be checked against a buyer’s capital budget.
| Element | Included | Why | 2025 value |
|---|---|---|---|
| Electrical, cooling, civil works | Yes | Facility capital spend | USD 394.50 million |
| Racks, cabling, physical network | Yes | Installed with the hall | USD 24.62 million |
| Servers, storage, switches | No | IT equipment, in the parent IT line | USD 958.75 million (parent) |
| DCIM software | No | Separate software market | Separate report |
| Land, electricity, grid works, colocation rent | No | Real estate and operating costs | Not modelled |
The out-of-scope terms are IT hardware, servers, storage, land, electricity, grid reinforcement and colocation rent. In-scope buyers include hyperscale cloud providers, colocation operators, telecom carriers, banks and public agencies, and small and medium-sized enterprises (SMEs) that build or upgrade their own server rooms.
What Drives Data Center Infrastructure Spending in Turkey?
Three Turkey-specific forces drive Turkey data center infrastructure spend from USD 419.12 million in 2025 to USD 1.34 billion in 2030: a 1 GW national target, data residency rules and Ankara’s hyperscale campuses.
The 1 GW by 2030 Target and the HIT-30 Data Center Call
Turkey had about 250 MW of data center infrastructure in November 2025, according to Minister of Industry and Technology Mehmet Fatih Kacır, and the AI Vision and Action Plan 2026-2030 sets a target of at least 1 GW by 2030 (Invest in Türkiye Office, June 2026). According to the Ministry of Industry and Technology, the HIT-30 call of October 2025 backs data centers of at least 30 MW of IT load, at least 50% compatible with AI hardware and with a PUE of 1.4 or lower, from a USD 1.5 billion budget with tax incentives of up to 50%. DC Market Insights assumes 400 MW of new IT load from 2026 to 2030 rather than the 660 MW the target implies, which still adds USD 3.61 billion of new-build facility content over the five years.
Data Residency Rules for Banks and Public Data
According to the Official Gazette of 6 July 2019, Presidential Circular 2019/12 requires critical public data to be stored inside Turkey and bars public data from foreign cloud storage. According to the Official Gazette of 15 March 2020, the banking information systems regulation of the Banking Regulation and Supervision Agency (BDDK) requires banks to keep their primary and secondary systems in Turkey. These rules keep 31.0% of 2025 spend, USD 129.93 million, in enterprise data centers run by banks, insurers and agencies, and they make Tier III and Tier IV backup sites a regulatory need rather than a choice.
Ankara’s Hyperscale and Sovereign Campuses
According to the Invest in Türkiye Office (November 2025), Turkcell and Google Cloud will invest USD 3 billion in Türkiye’s first hyperscale cloud region, and Turkcell lifted its Ankara data center to 54 MW of active capacity with a fifth module, according to Turkcell’s second-quarter 2026 results. Khazna Data Centers plans an AI-ready facility of up to 100 MW in Ankara’s Başkent Organised Industrial Zone (OSB), according to the Khazna Ankara announcement (May 2025). These projects lift hyperscale and cloud data centers from 25.0% to 45.0% of spend by 2035, a growth rate of 22.28% a year.
Which Trends Are Changing How Turkish Data Centers Are Built?
Two trends reshape the Turkey data center infrastructure bill of materials: seismic design in every new hall and higher power density that lifts cooling content per MW by about 47% between 2025 and 2035.
Seismic Isolation After the February 2023 Earthquakes
According to the Official Gazette of 18 March 2018, the Turkish Building Earthquake Code (TBDY 2018) sets design loads for every new building, and the February 2023 Kahramanmaraş earthquakes made seismic risk a board-level question for data center owners. DAMAC Digital (the data center unit of DAMAC Group) and Vodafone Türkiye built their 4 MW Izmir facility on seismic isolators, with a USD 100 million first phase, according to DAMAC Digital (September 2026). DC Market Insights estimates that seismic isolation, bracing and anchoring add about 6% to civil and structural content per MW in Turkey, part of the USD 149.91 million civil line in 2025.
AI-Ready Halls and the Shift to Chilled Water and Liquid Loops
The HIT-30 requirement that at least half of a project’s capacity be compatible with AI hardware is moving Turkish designs from direct-expansion units to chilled-water plant with liquid-cooling distribution, the equipment side of which is sized in the Turkey Data Center Cooling Market. DC Market Insights models mechanical and cooling infrastructure, 20.2% of 2025 Turkey data center infrastructure spend, growing the fastest of any infrastructure type at 18.15% a year.
Edge Sites for Cloud Latency in Istanbul
Amazon Web Services (AWS) announced general availability of an AWS Local Zone in Istanbul in May 2026 (Source: AWS), served from the Frankfurt region, and Equinix runs its Istanbul 2 (IL2) site in Dudullu OSB with N+1 UPS and more than 30 hours of generator runtime at full load, according to the Equinix IL2 facility page. Edge data centers take USD 25.15 million, or 6.0%, of 2025 Turkey data center infrastructure spend (DC Market Insights estimate).
What Holds Back Data Center Infrastructure Projects in Turkey? Restraints and Barriers
Grid connection limits and rising power prices are the two restraints on Turkey data center infrastructure that could cut 2035 spend by up to USD 455.05 million, the gap between the base case and the low case.
Grid Connection Queues at Transmission Level
Large campuses need transmission-level connections, and new transmission capacity has been scarce for months at a time in 2025 and 2026. DC Market Insights’ low case assumes 30% fewer completions from 2027, which leaves 2035 spend at USD 1.28 billion instead of USD 1.74 billion and the installed base at about 1,000 MW instead of 1,250 MW.
Electricity Tariffs and Currency Risk
According to the Energy Market Regulatory Authority (EPDK), the medium-voltage industrial electricity tariff rose by 5.8% from 4 April 2026, after a 10% rise in April 2025. Since most switchgear, UPS systems and chillers are priced in euros or US dollars while operators earn part of their revenue in Turkish lira, currency swings can delay orders; DC Market Insights estimates that about 70% of 2025 equipment value is imported or priced in foreign currency.
Where Are the Biggest Opportunities for Infrastructure Suppliers in Turkey?
The two largest opportunities in Turkey data center infrastructure are Ankara campus fit-outs, worth USD 433.96 million in the Başkent OSB and Temelli hub by 2035, and upgrades of older halls, worth USD 678.00 million by 2035.
Fit-Out of Ankara’s Başkent OSB and Temelli Campuses
The Ankara Başkent OSB and Temelli hub grows from USD 56.58 million in 2025 at 22.60% a year, the fastest of the 12 hubs, as the Khazna, Trendyol-Castle and Türk Telekom campuses move from foundations to fit-out. Medium-voltage substations, chillers and seismic structures are the first packages to tender.
Upgrades of Bank and Public-Sector Halls
Upgrade and retrofit spend grows 16.71% a year, faster than new builds at 14.49%, because older enterprise rooms must reach Tier III resilience, lower PUE and current earthquake design. Suppliers with local service teams and UPS production, such as Legrand’s Inform UPS factory in Turkey (opened in January 2020, Source: Legrand), are best placed for these projects.
How Much Does Data Center Infrastructure Cost per MW in Turkey?
For Turkey data center infrastructure, DC Market Insights puts facility content at USD 8.60 million per MW of IT load in 2025, rising to USD 9.87 million per MW in 2035, plus USD 0.55 million per MW for racks and cabling.
| Cost item | 2020 | 2025 | 2030 | 2035 |
|---|---|---|---|---|
| Facility content per new MW (USD million) | 7.80 | 8.60 | 9.24 | 9.87 |
| Racks and cabling per new MW (USD million) | 0.50 | 0.55 | 0.65 | 0.75 |
| Upgrade spend per installed MW-year (USD million) | 0.36 | 0.42 | 0.48 | 0.54 |
| Racks and cabling refresh per installed MW-year (USD thousand) | 25 | 25 | 25 | 25 |
Public anchors back these values. Trendyol and Castle Investments put the total development cost of the 48 MW Ankara Data Hub at about USD 500 million, about USD 10.42 million per MW including land and shell, according to the Ankara Data Hub announcement (Invest in Türkiye Office, June 2025). According to DAMAC Digital, the Izmir site it built with Vodafone Türkiye cost USD 100 million for its first 4 MW, with a shell built for 20 MW and USD 300 million planned in total, or about USD 15 million per MW at full build. Smaller and earthquake-hardened halls cost more per MW than large Ankara campuses.
Which Rules and Standards Shape Turkish Data Center Infrastructure?
Five rules shape about USD 419.12 million of 2025 Turkey data center infrastructure spend, from data residency to earthquake design and energy efficiency.
- Presidential Circular 2019/12 on information and communication security (Official Gazette No. 30823, 6 July 2019): critical data stored in Turkey.
- BDDK regulation on banks’ information systems and electronic banking (Official Gazette No. 31069, 15 March 2020): primary and secondary bank systems in Turkey.
- Law No. 7499 amending the Personal Data Protection Law (KVKK) cross-border transfer rules (Official Gazette No. 32487, 12 March 2024; in force 1 June 2024).
- Turkish Building Earthquake Code TBDY 2018 (Official Gazette No. 30364, 18 March 2018): seismic design loads for new halls.
- HIT-30 data center call (Ministry of Industry and Technology, October 2025): minimum 30 MW of IT load, PUE of 1.4 or lower, up to 50% tax incentive.
EN 50600 and TIA-942 certifications, and Uptime tier ratings, are common in colocation contracts; Equinix IL2, for example, is certified under EN 50600 by TSI. DC Market Insights estimates that Tier III facilities take 64.0% of 2025 spend, USD 268.24 million.
Which Infrastructure Type, Project Type and Data Center Type Carry the Value in Turkey?
Electrical infrastructure leads the Turkey Data Center Infrastructure Market with USD 159.77 million in 2025 (38.1%), while mechanical and cooling infrastructure grows fastest at 18.15% a year.
By Infrastructure Type
| Infrastructure Type | 2025 (USD million) | Share 2025 | 2035 (USD million) | CAGR 2025-2035 |
|---|---|---|---|---|
| Electrical Infrastructure | 159.77 | 38.1% | 678.52 | 15.56% |
| Mechanical and Cooling Infrastructure | 84.82 | 20.2% | 449.63 | 18.15% |
| Civil, Structural and Architectural | 149.91 | 35.8% | 506.85 | 12.95% |
| Racks, Cabling and Physical Network | 24.62 | 5.9% | 105.00 | 15.61% |
| Total | 419.12 | 100.0% | 1,740.00 | 15.30% |
Electrical infrastructure stays the largest line because every Turkish campus above 30 MW needs its own medium-voltage substation, generators and UPS systems. Racks, cabling and physical network grow 15.61% a year as AI racks raise the content per MW from USD 0.55 million to USD 0.75 million.
By Project Type
| Project Type | 2025 (USD million) | Share 2025 | 2035 (USD million) | CAGR 2025-2035 |
|---|---|---|---|---|
| New Build | 274.50 | 65.5% | 1,062.00 | 14.49% |
| Upgrade and Retrofit | 144.62 | 34.5% | 678.00 | 16.71% |
| Total | 419.12 | 100.0% | 1,740.00 | 15.30% |
New builds take 65.5% of 2025 spend, and upgrades grow faster at 16.71% a year as the installed base nearly quadruples to 1,250 MW by 2035.
By Data Center Type
| Data Center Type | 2025 (USD million) | Share 2025 | 2035 (USD million) | CAGR 2025-2035 |
|---|---|---|---|---|
| Hyperscale and Cloud Data Centers | 104.78 | 25.0% | 783.00 | 22.28% |
| Colocation Data Centers | 159.27 | 38.0% | 556.80 | 13.33% |
| Enterprise Data Centers | 129.93 | 31.0% | 295.80 | 8.57% |
| Edge Data Centers | 25.15 | 6.0% | 104.40 | 15.30% |
| Total | 419.12 | 100.0% | 1,740.00 | 15.30% |
Hyperscale and cloud data centers grow fastest at 22.28% a year and become the largest type by 2035 with USD 783.00 million, overtaking colocation.
By Tier
| Tier | 2025 (USD million) | Share 2025 | 2035 (USD million) | CAGR 2025-2035 |
|---|---|---|---|---|
| Tier III | 268.24 | 64.0% | 1,078.80 | 14.93% |
| Tier IV | 67.06 | 16.0% | 487.20 | 21.93% |
| Tier I and II | 83.82 | 20.0% | 174.00 | 7.58% |
| Total | 419.12 | 100.0% | 1,740.00 | 15.30% |
Tier IV spend grows 21.93% a year as banks and sovereign AI sites demand fault-tolerant power and cooling paths.
DC Exclusive: The Ankara-Led Project Pipeline Tracker, 9 Projects and About 242 MW Named
DC Market Insights built this Turkey data center infrastructure tracker from 20 inputs and modelled estimates: nine named projects carry about 242 MW of disclosed IT load, worth about USD 2.11 billion of facility content at the 2026 cost of USD 8.73 million per MW.
| Project | Location | Size or budget | Date | Source |
|---|---|---|---|---|
| Turkcell Ankara data center | Ankara city | 54 MW active after 5th module | Aug 2026 | Turkcell Q2 2026 results |
| Turkcell and Google Cloud hyperscale region | Ankara (3 sites) | USD 3 billion joint; service from 2028 | Nov 2025 | Invest in Türkiye Office |
| Khazna Data Centers AI-ready facility | Başkent OSB, Ankara | Up to 100 MW | May 2025 | Invest in Türkiye Office |
| Trendyol and Castle Investments Ankara Data Hub | Temelli, Ankara | 48 MW IT; USD 500 million; 9.6 MW phase 1 in Q3 2026 | Jun 2025 | Invest in Türkiye Office |
| Türk Telekom third large data center | Başkent OSB, Ankara | Foundation laid | Sep 2026 | Türk Telekom |
| Türksat Gölbaşı data center | Gölbaşı, Ankara | 33 MVA installed power (about 20 MW IT, DC Market Insights estimate) | Jul 2026 | Türksat |
| DAMAC Digital and Vodafone Türkiye Izmir | Izmir | 4 MW IT, USD 100 million; 20 MW and USD 300 million planned | Sep 2026 | DAMAC Digital |
| AWS Local Zone Istanbul | Istanbul | General availability | May 2026 | AWS |
| Equinix IL2 | Dudullu OSB, Istanbul | N+1 UPS, 30+ hours generator runtime | Live | Equinix |
Six of the nine projects are in Ankara, which is why Ankara and Central Anatolia carries 43.0% of 2035 spend in this model. The named MW (54 + 100 + 48 + 20 + 20) covers 60.5% of the 400 MW of new IT load modelled for 2026-2030; the rest comes from colocation expansions in Istanbul and enterprise upgrades not yet announced.
Region × Infrastructure Type Matrix, 2025 (USD million)
| Region | Electrical Infrastructure | Mechanical and Cooling Infrastructure | Civil, Structural and Architectural | Racks, Cabling and Physical Network | Total |
|---|---|---|---|---|---|
| Istanbul and Marmara | 83.08 | 44.11 | 77.95 | 12.80 | 217.94 |
| Ankara and Central Anatolia | 47.93 | 25.45 | 44.97 | 7.39 | 125.74 |
| Izmir and Aegean | 15.98 | 8.48 | 14.99 | 2.46 | 41.91 |
| Rest of Turkey | 12.78 | 6.79 | 11.99 | 1.97 | 33.53 |
Which Turkish Region Leads Data Center Infrastructure Spending, and Which Grows Fastest?
Istanbul and Marmara leads Turkey data center infrastructure with 52.0% of 2025 spend (USD 217.94 million), while Ankara and Central Anatolia grows fastest at 19.52% a year to USD 748.20 million in 2035.
| Region | 2025 (USD million) | Share 2025 | 2035 (USD million) | CAGR 2025-2035 |
|---|---|---|---|---|
| Istanbul and Marmara | 217.94 | 52.0% | 696.00 | 12.31% |
| Ankara and Central Anatolia | 125.74 | 30.0% | 748.20 | 19.52% |
| Izmir and Aegean | 41.91 | 10.0% | 191.40 | 16.40% |
| Rest of Turkey | 33.53 | 8.0% | 104.40 | 12.03% |
| Total | 419.12 | 100.0% | 1,740.00 | 15.30% |
Istanbul and Marmara
Istanbul’s Asian side, around Ümraniye and Dudullu OSB where Equinix IL2 sits, is the largest hub with USD 78.46 million in 2025; Kocaeli and Gebze grow 14.59% a year as operators look for land outside the city.
Ankara and Central Anatolia
Ankara’s share rises from 30.0% to 43.0% by 2035, led by Başkent OSB and Temelli at 22.60% a year, where Khazna plans up to 100 MW and the Ankara Data Hub 48 MW.
Izmir and Aegean
Izmir and Aegean grows 16.40% a year to USD 191.40 million by 2035, helped by the DAMAC Digital and Vodafone Türkiye site and subsea cable landings on the Aegean coast.
Rest of Turkey
The rest of Turkey, including Antalya and other provinces, holds 8.0% of 2025 spend and grows 12.03% a year, mainly from regional bank and public-sector backup sites.
Which Turkish Hubs Carry the Most Infrastructure Spend?
The Istanbul Asian side leads the 12 Turkey data center infrastructure hubs with USD 78.46 million in 2025, and Ankara Başkent OSB and Temelli grows fastest at 22.60% a year to USD 433.96 million in 2035.
| Rank | Hub | Region | 2025 (USD million) | 2035 (USD million) | CAGR 2025-2035 |
|---|---|---|---|---|---|
| 1 | Istanbul Asian side (Ümraniye, Dudullu) | Istanbul and Marmara | 78.46 | 229.68 | 11.34% |
| 2 | Istanbul European side | Istanbul and Marmara | 65.38 | 187.92 | 11.14% |
| 3 | Ankara city and Gölbaşı | Ankara and Central Anatolia | 60.35 | 269.35 | 16.13% |
| 4 | Ankara Başkent OSB and Temelli | Ankara and Central Anatolia | 56.58 | 433.96 | 22.60% |
| 5 | Kocaeli and Gebze | Istanbul and Marmara | 39.23 | 153.12 | 14.59% |
| 6 | Izmir | Izmir and Aegean | 35.63 | 168.43 | 16.81% |
| 7 | Other provinces | Rest of Turkey | 20.12 | 62.64 | 12.03% |
| 8 | Tekirdağ and Çorlu | Istanbul and Marmara | 19.61 | 69.60 | 13.50% |
| 9 | Bursa | Istanbul and Marmara | 15.26 | 55.68 | 13.82% |
| 10 | Antalya | Rest of Turkey | 13.41 | 41.76 | 12.03% |
| 11 | Konya | Ankara and Central Anatolia | 8.80 | 44.89 | 17.70% |
| 12 | Manisa and Denizli | Izmir and Aegean | 6.29 | 22.97 | 13.83% |
By 2035, Ankara Başkent OSB and Temelli becomes the largest hub, ahead of the Istanbul Asian side at USD 229.68 million.
How Could the 2035 Forecast for Turkish Data Center Infrastructure Change?
The 2035 Turkey Data Center Infrastructure Market ranges from USD 1.28 billion to USD 2.12 billion, around a base case of USD 1.74 billion.
| Scenario | Assumption | 2035 size | CAGR 2025-2035 |
|---|---|---|---|
| Low | New IT completions 30% below base from 2027 (grid delays) | USD 1.28 billion | 11.85% |
| Base | 400 MW new IT 2026-2030; 1,250 MW installed by 2035 | USD 1.74 billion | 15.30% |
| High | Completions 25% above base from 2027 (1 GW target met by 2031) | USD 2.12 billion | 17.59% |
Who Are the Leading Data Center Infrastructure Companies in Turkey?
In Turkey data center infrastructure, the top five equipment suppliers hold an estimated 38% of 2025 equipment value, led by Schneider Electric with about 11% (DC Market Insights estimate, based on installed UPS and switchgear references in Turkish colocation sites).
- Schneider Electric
- Vertiv
- ABB
- Siemens
- Eaton
- Legrand (Inform UPS)
- Daikin
- Johnson Controls
- Carrier
- Rittal
- Turkcell
- Türk Telekom
- Equinix
- Khazna Data Centers
- Castle Investments
- DAMAC Digital (Edgnex)
- Türksat
Equipment suppliers compete for packages, while operators such as Turkcell, Türk Telekom and Equinix are the main buyers. Turkcell reported 54 MW of active capacity in Ankara in its second-quarter 2026 results, and Legrand produces UPS systems locally through Inform. Local engineering, procurement and construction (EPC) contractors take most civil and structural packages, which keeps that USD 149.91 million line less concentrated than electrical equipment.
What Happened in Turkish Data Center Infrastructure in 2025 and 2026?
Six dated Turkey data center infrastructure events from May 2025 to September 2026 added about 202 MW of named projects to Turkey’s pipeline.
- In May 2025, Khazna Data Centers announced an AI-ready facility of up to 100 MW in Ankara’s Başkent OSB (Source: Invest in Türkiye Office).
- In June 2025, Trendyol and Castle Investments announced the 48 MW, USD 500 million Ankara Data Hub (Source: Invest in Türkiye Office).
- In November 2025, Turkcell and Google Cloud announced a USD 3 billion hyperscale cloud region (Source: Invest in Türkiye Office).
- In May 2026, AWS made its Istanbul Local Zone generally available (Source: AWS).
- In August 2026, Turkcell reported 54 MW of active capacity in Ankara after a fifth module (Source: Turkcell second-quarter 2026 results).
- In September 2026, Türk Telekom laid the foundation of its third large data center in Başkent OSB (Source: Türk Telekom).
Methodology: How We Built the Turkey Data Center Infrastructure Model
DC Market Insights built the model from 16 inputs: 30 MW of new IT load in 2025 × USD 8.60 million per MW, plus 325 MW of average installed load × USD 0.42 million of upgrades, plus USD 24.62 million of racks and cabling, gives USD 419.12 million.
New IT load follows the installed base of the parent model (240 MW in 2020, 340 MW in 2025, 740 MW in 2030, 1,250 MW in 2035). Facility content per MW rises from USD 7.80 million in 2020 to USD 9.87 million in 2035; upgrade spend rises from USD 0.36 million to USD 0.54 million per installed MW-year. Splits by infrastructure type, project type, data center type, tier, 4 regions and 12 hubs are DC Market Insights estimates and sum to the total every year.
Three bound checks hold. Ceiling 1: 400 MW of new IT load in 2026-2030 is below the 660 MW implied by the 1 GW target. Ceiling 2: the market is 30.97% of the USD 1.35 billion parent market in 2025, in line with the parent’s power, cooling and construction lines. Floor: the named Trendyol-Castle and DAMAC-Vodafone budgets of USD 800 million are below the USD 5.10 billion of modelled spend in 2026-2030. Full details are in our research methodology.
Table of contents
- 01Introduction
- 1.1Market Definition
- 1.2Opening Receipt: MW × Cost per MW
- 02Market Snapshot
- 2.1Market Snapshot, 2025, 2026 and 2035
- 2.2Key Market Statistics
- 2.3Key Takeaways
- 03Executive Summary
- 3.1Market Size 2020-2035
- 3.2Market Attributes
- 04Market Scope
- 4.1Included
- 4.2Excluded
- 4.3How the Segments Fit Together
- 05Scope Comparison
- 5.1Why Estimates Differ
- 5.2Scope Table
- 06Market Drivers
- 6.1The 1 GW by 2030 Target and the HIT-30 Data Center Call
- 6.2Data Residency Rules for Banks and Public Data
- 6.3Ankara's Hyperscale and Sovereign Campuses
- 07Market Trends
- 7.1Seismic Isolation After the February 2023 Earthquakes
- 7.2AI-Ready Halls and the Shift to Chilled Water and Liquid Loops
- 7.3Edge Sites for Cloud Latency in Istanbul
- 08Market Restraints
- 8.1Grid Connection Queues at Transmission Level
- 8.2Electricity Tariffs and Currency Risk
- 09Market Opportunities
- 9.1Fit-Out of Ankara's Başkent OSB and Temelli Campuses
- 9.2Upgrades of Bank and Public-Sector Halls
- 10Pricing
- 10.1Cost per MW, 2020-2035
- 10.2Public Price Anchors
- 11Standards and Regulation
- 11.1Presidential Circular 2019/12
- 11.2BDDK Banking Systems Regulation
- 11.3Law No. 7499 (KVKK)
- 11.4Turkish Building Earthquake Code TBDY 2018
- 11.5HIT-30 Data Center Call
- 12Market Segmentation
- 12.1By Infrastructure Type: Electrical Infrastructure
- 12.2By Infrastructure Type: Mechanical and Cooling Infrastructure
- 12.3By Infrastructure Type: Civil, Structural and Architectural
- 12.4By Infrastructure Type: Racks, Cabling and Physical Network
- 12.5By Project Type: New Build
- 12.6By Project Type: Upgrade and Retrofit
- 12.7By Data Center Type: Hyperscale and Cloud
- 12.8By Data Center Type: Colocation
- 12.9By Data Center Type: Enterprise
- 12.10By Data Center Type: Edge
- 12.11By Tier: Tier III
- 12.12By Tier: Tier IV
- 12.13By Tier: Tier I and II
- 13DC Exclusive: Ankara-Led Project Pipeline Tracker
- 13.1Nine Named Projects
- 13.2Region × Infrastructure Type Matrix, 2025
- 14Regional Insights
- 14.1Istanbul and Marmara
- 14.2Ankara and Central Anatolia
- 14.3Izmir and Aegean
- 14.4Rest of Turkey
- 15Hub Analysis
- 15.1Istanbul Asian side (Ümraniye, Dudullu)
- 15.2Istanbul European side
- 15.3Ankara city and Gölbaşı
- 15.4Ankara Başkent OSB and Temelli
- 15.5Kocaeli and Gebze
- 15.6Izmir
- 15.7Other provinces
- 15.8Tekirdağ and Çorlu
- 15.9Bursa
- 15.10Antalya
- 15.11Konya
- 15.12Manisa and Denizli
- 16Forecast Scenarios
- 16.1Low Case
- 16.2Base Case
- 16.3High Case
- 17Competitive Insights
- 17.1Schneider Electric
- 17.2Vertiv
- 17.3ABB
- 17.4Siemens
- 17.5Eaton
- 17.6Legrand (Inform UPS)
- 17.7Daikin
- 17.8Johnson Controls
- 17.9Carrier
- 17.10Rittal
- 17.11Turkcell
- 17.12Türk Telekom
- 17.13Equinix
- 17.14Khazna Data Centers
- 17.15Castle Investments
- 17.16DAMAC Digital (Edgnex)
- 17.17Türksat
- 18Recent Developments
- 18.1Dated Events, May 2025 to September 2026
- 19Methodology
- 19.1Model in Numbers
- 19.2Bound Checks
- Fig. 1Turkey Data Center Infrastructure Market Size, 2020-2035 (USD million)
- Table 1Market Attributes
- Table 2Scope Comparison
- Table 3Cost per MW, 2020-2035
- Table 4Market by Infrastructure Type
- Table 5Market by Project Type
- Table 6Market by Data Center Type
- Table 7Market by Tier
- Table 8Ankara-Led Project Pipeline Tracker
- Table 9Region × Infrastructure Type Matrix, 2025
- Table 10Market by Region
- Table 11Top 12 Hubs
- Table 12Forecast Scenarios, 2035
About this report
Written by Amit Jain and reviewed by Deepti Agrawal, Senior Editor, Research. Figures are built top-down and bottom-up and reconciled before publication, with 2025 as the base year.
Read our methodologyHow we built this
- Historical period2020-2024
- Base year2025
- Forecast period2026-2035
- Sizing approachTop-down + bottom-up
Need more than the report?
Advisory on this market
Due diligence, site selection and market entry work, by the analysts who wrote this report.
See consulting servicesFrequently asked questions
USD 679.28 million in 2026, 62.07% above USD 419.12 million in 2025, according to DC Market Insights estimates. The market is projected to reach USD 1.74 billion by 2035, a CAGR of 15.30% from 2025, as new IT completions rise from 30 MW to 55 MW a year.
15.30% a year from 2025 to 2035, after 17.18% a year from 2020 to 2025. Growth peaks from 2026 to 2030, when 400 MW of new IT load is modelled against Turkey’s target of at least 1 GW of capacity by 2030.
USD 419.12 million of 2025 spend on electrical, mechanical and cooling, civil and structural works, and racks and cabling inside Turkish data centers. Servers, storage, switches, land, electricity and monitoring software are excluded.
Electrical infrastructure, with USD 159.77 million in 2025 or 38.1% of spend, because every campus above 30 MW needs its own medium-voltage substation, generators and UPS systems. Mechanical and cooling infrastructure grows fastest at 18.15% a year.
About USD 8.60 million of facility content per MW of IT load in 2025, rising to USD 9.87 million by 2035, plus USD 0.55 million per MW for racks and cabling (DC Market Insights estimate). The 48 MW Ankara Data Hub costs about USD 10.42 million per MW including land.
Ankara and Central Anatolia, at 19.52% a year to USD 748.20 million by 2035, because the Khazna, Turkcell-Google and Türk Telekom campuses sit in the capital. Istanbul and Marmara still leads 2025 spend with 52.0%.
Schneider Electric leads with an estimated 11% of 2025 equipment value, and the top five suppliers hold about 38% (DC Market Insights estimate). Vertiv, ABB, Siemens, Eaton, Legrand (Inform UPS), Daikin and Johnson Controls also compete.
About 250 MW of data center infrastructure in November 2025, according to the Minister of Industry and Technology; DC Market Insights models 340 MW of installed IT load at end-2025 including enterprise halls, rising to 1,250 MW by 2035.
Five rules matter most: Presidential Circular 2019/12 on data residency, the 2020 BDDK banking systems regulation, the 2024 KVKK amendment (Law No. 7499), the 2018 Turkish Building Earthquake Code and the HIT-30 call, which requires 30 MW of IT load and a PUE of 1.4 or lower.
USD 679.28 million in 2026 is the facility layer only; estimates that add servers, storage and networking equipment, worth USD 958.75 million in 2025 in the parent model, or land and electricity, come out two to three times higher.
USD 1.35 billion in 2025 for the parent Turkey Data Center Market, rising to USD 4.53 billion in 2035. The infrastructure layer, USD 419.12 million in 2025, is 30.97% of that total in 2025 and 38.41% in 2035, covering the physical facility only.
At least 1 GW by 2030, under the AI Vision and Action Plan 2026-2030 (Invest in Türkiye Office, June 2026). Turkey had about 250 MW of data center infrastructure in November 2025, according to the Minister of Industry and Technology.
Get this report
How do I get the full report?
Request a quote; we reply by email within one business day.
How and when will I receive the report?
By email, within 24–48 business hours of payment.
How can I pay?
Once you accept the quote, we email you a secure payment link.
Can I see a sample first?
Yes. Request a free sample and we will email it to you.
Can the report be tailored to my needs?
Yes. We can add countries, segments or data cuts. Talk to an analyst about the scope you need.
Can I get an invoice or pay against a purchase order?
Write to sales@dcmarketinsights.com and our team will help.