

Key takeaways
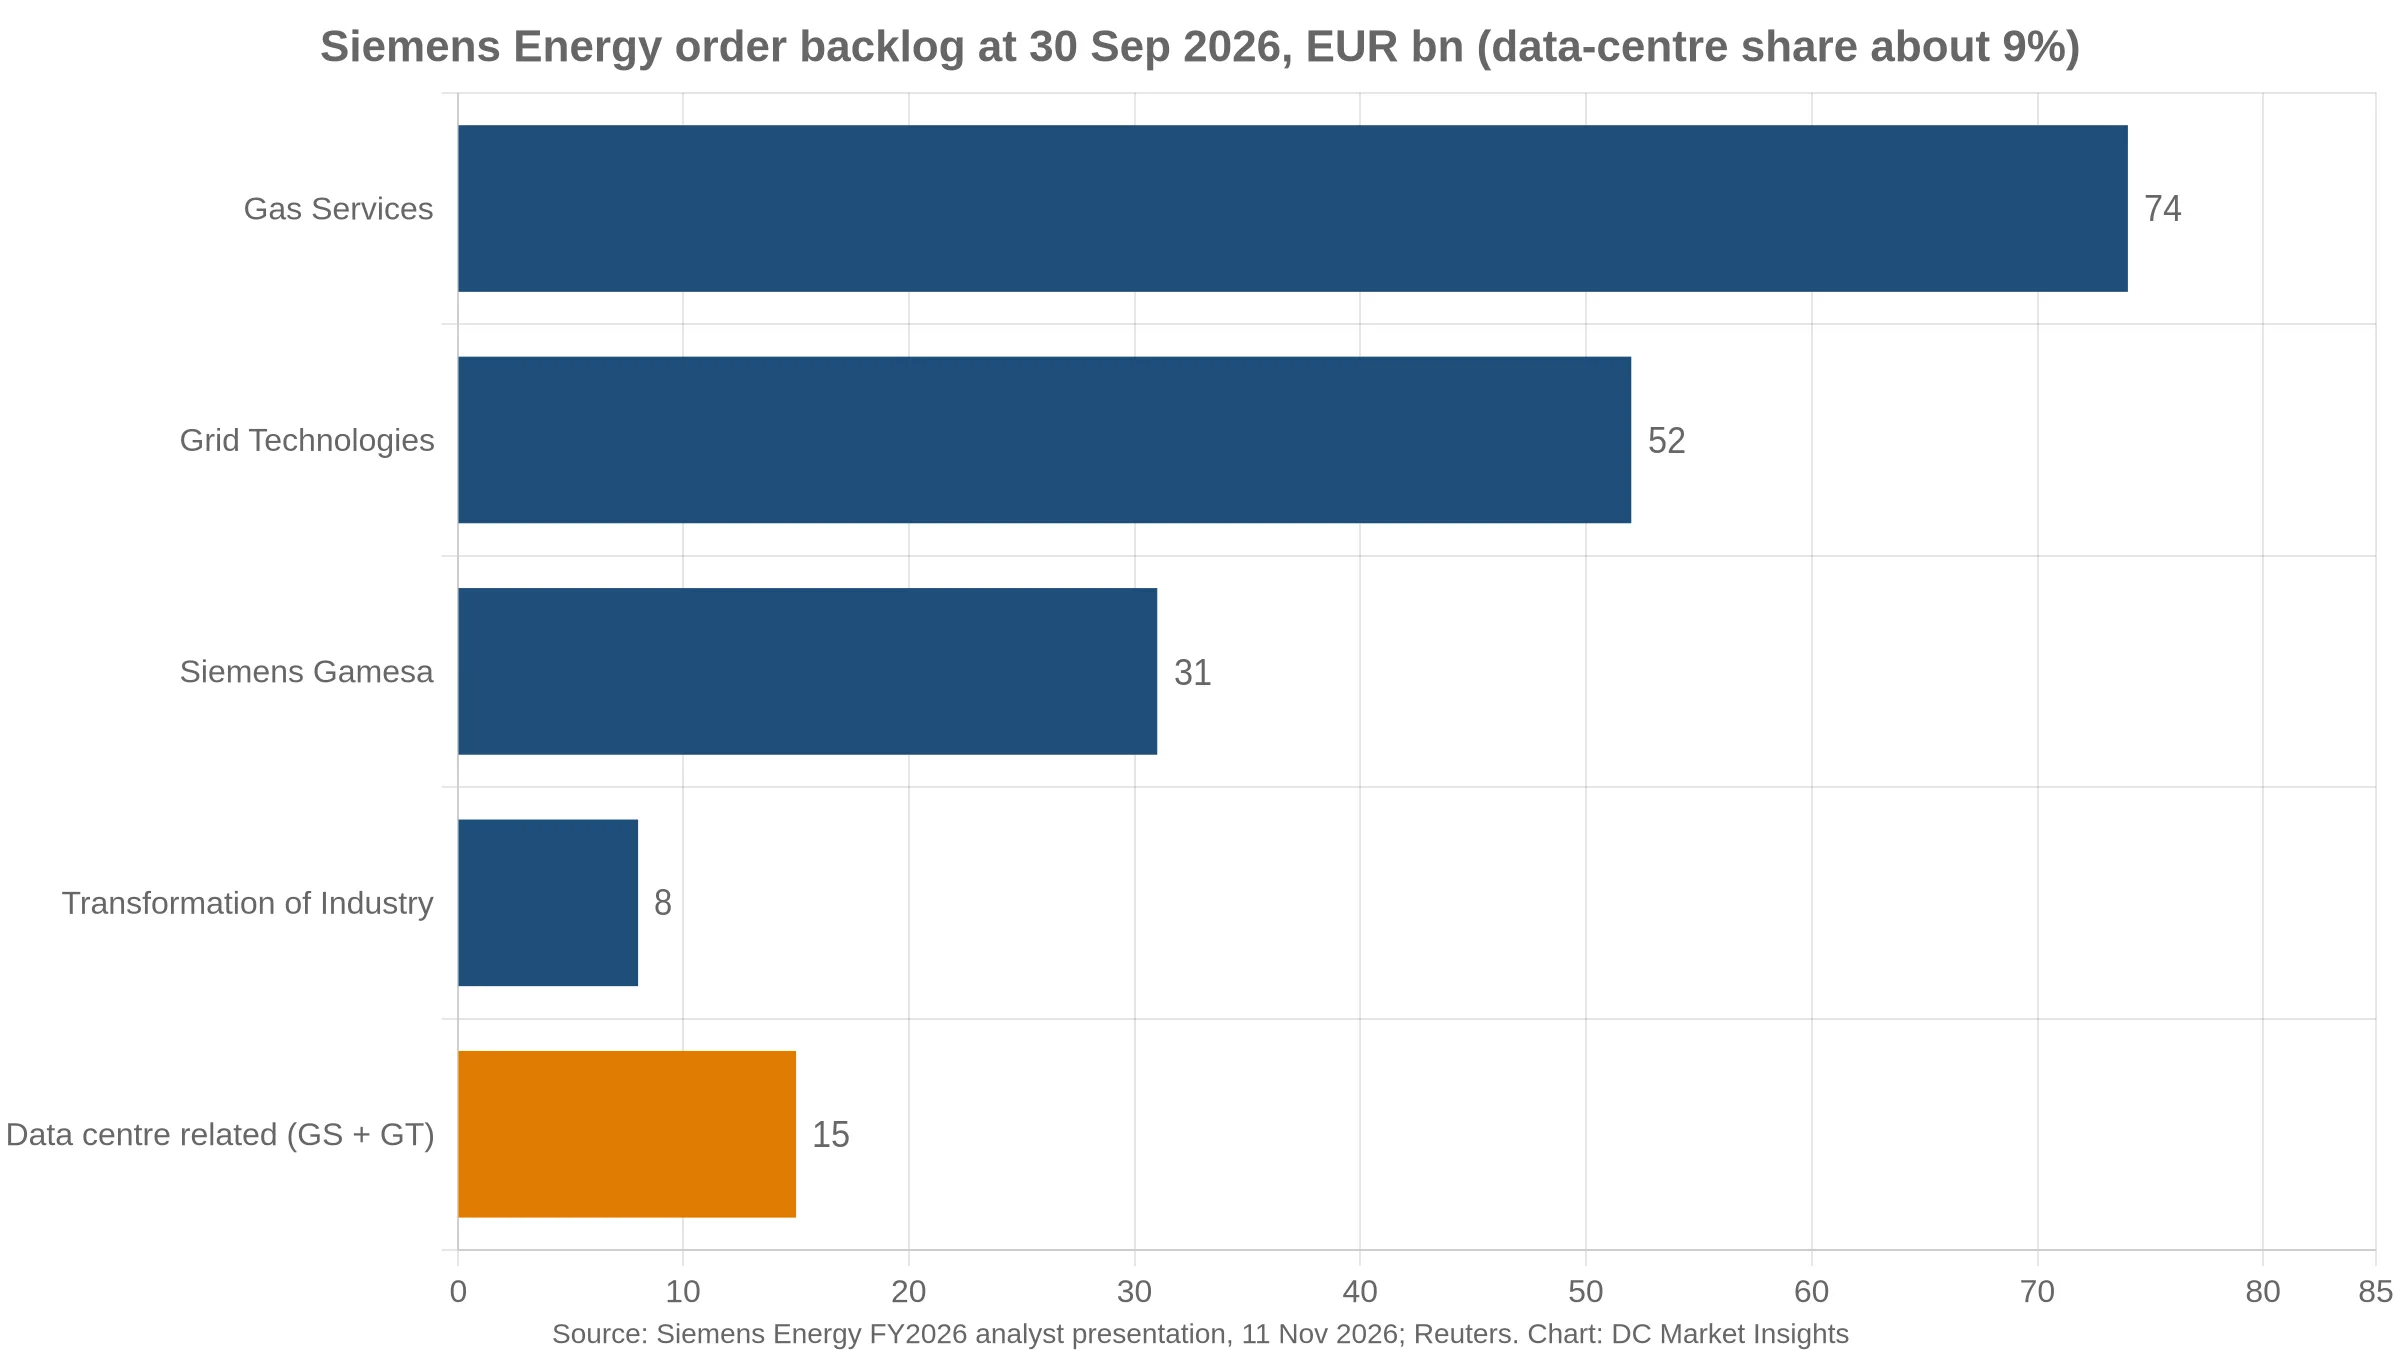
- About €15bn (US$16.8bn) of Siemens Energy’s record €164bn order backlog is tied to data centres, 9.1%, the company said on 11 November (Siemens Energy, Reuters).
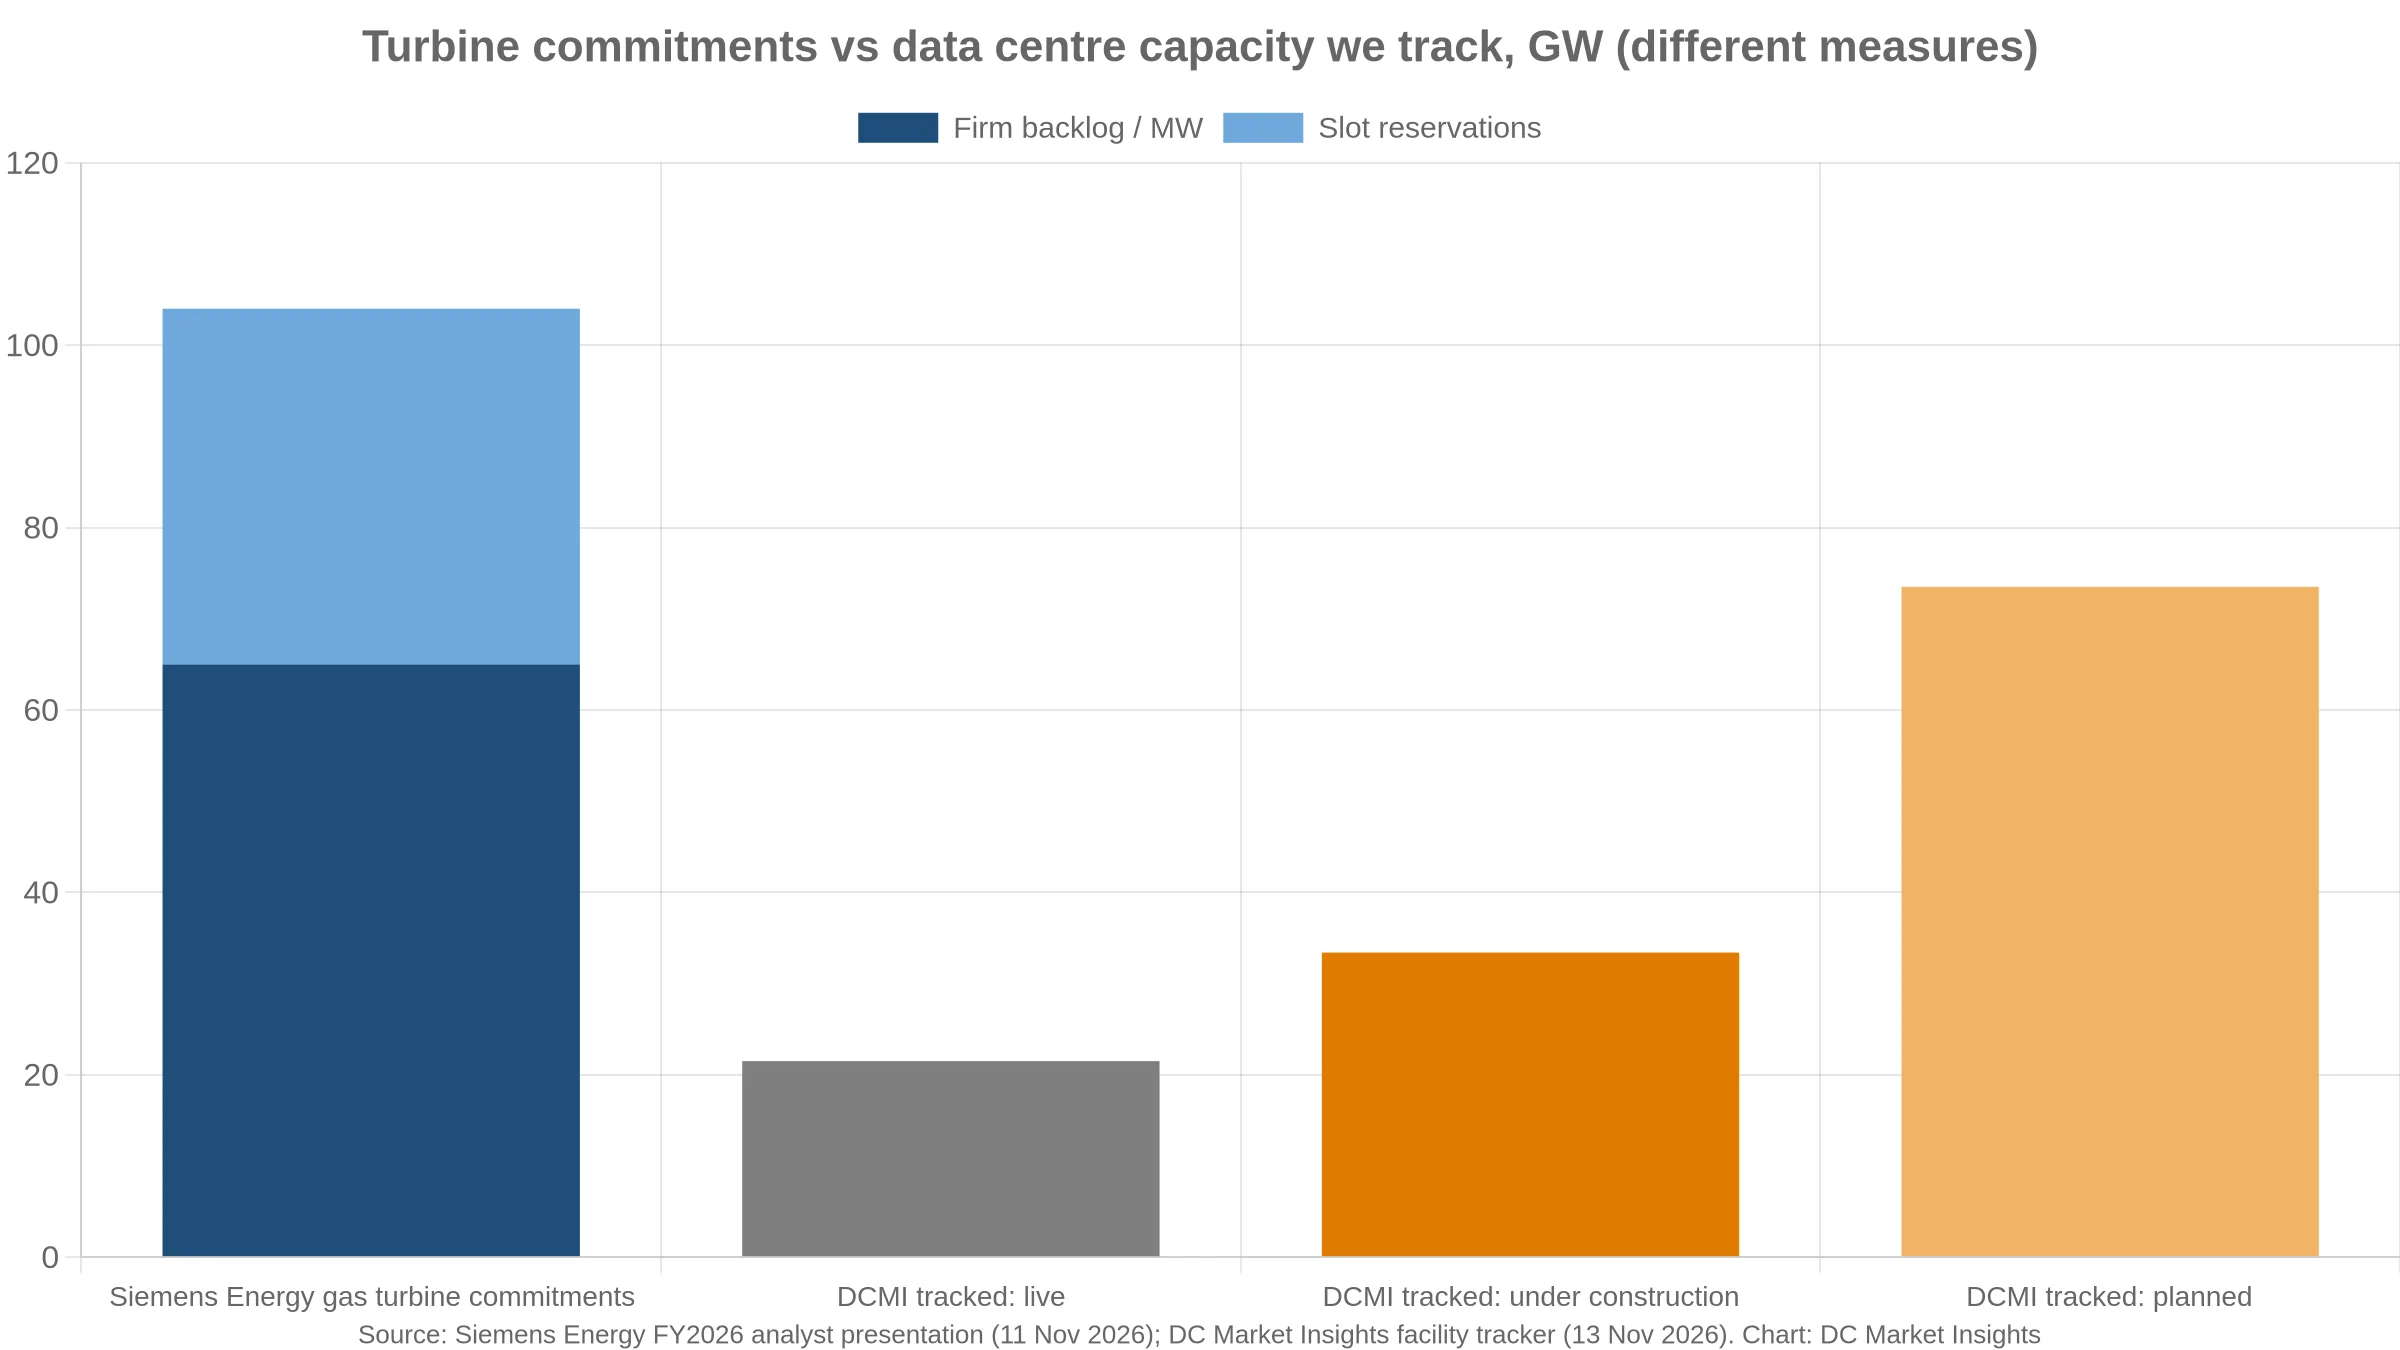
- Siemens Energy’s gas turbine commitments reached 104 GW at 30 September: 65 GW of firm backlog and 39 GW of slot reservations. In the fourth quarter it signed 14 GW of new reservations but converted none into orders (Siemens Energy analyst presentation).
- Siemens AG booked record orders of €108.2bn in fiscal 2026, with fourth-quarter orders up 58% to €34.8bn, and guides Smart Infrastructure to 11-13% growth in fiscal 2027 (Siemens, 12 November).
- DC Market Insights data: 3,248 tracked facilities in 66 countries hold 21.5 GW live, 33.4 GW under construction and 73.5 GW planned. The pipeline is 5.0 times live capacity, our calculation.
- Next: Nvidia reports third-quarter results on 17 November; Denmark’s grid operator answers 16 GW of data centre requests in late November; the EU’s data centre consultation closes on 14 December.
The clearest data centre signal in Europe this week came not from an operator but from the companies that build the power behind them. Siemens Energy put a number on its data centre exposure for the first time at full-year results: about €15bn of orders, 9% of a record backlog.
Why now: the two Munich groups reported on 11 and 12 November, a week before Nvidia’s results on 17 November, which markets use as the read-out for AI capital spending. The power-equipment numbers say demand is still firm. The reservation numbers say buyers are holding places in the queue more than they are signing orders. For operators, investors and vendors in Europe, the Middle East and Africa, both facts shape what equipment costs and when it arrives in 2027 and 2028.
What Siemens Energy reported on 11 November
Siemens Energy closed fiscal 2026 (to 30 September) with orders of €68.1bn, up 18.8% on a comparable basis, revenue of €44.2bn, up 15.5%, and a profit margin before special items of 12.4%, the company said. Its order backlog rose to a record €164bn from €138bn a year earlier. It proposed a dividend of €2.30 per share, up from €0.70, and a further share buyback of up to €9bn through fiscal 2030.
The data centre figure sits in the analyst presentation: “~€15bn of total order backlog is data center related”, across Gas Services and Grid Technologies. Reuters put that at about US$16.8bn, or 9.1% of the backlog, and reported that the shares rose 8.4% on the day, in a story carried by Euronext. The company said in its outlook that the build-out of data centres for artificial intelligence is likely to drive further generation and grid investment, especially in North America.
Demand for electricity for data centres is intact, also going forward.
Bruch also added a note of caution. “Some of the growth rates for data centres were unrealistic,” he said at the same press conference, according to Reuters. In our reading, that is a supplier telling the market that it prices and schedules on signed contracts, not on announced campuses.
| Segment (fiscal 2026) | Backlog, €bn | Revenue, €bn | Margin |
|---|---|---|---|
| Gas Services | 74 | 14.5 | 16.4% |
| Grid Technologies | 52 | 14.1 | 18.9% |
| Siemens Gamesa | 31 | 10.6 | 0.1% |
| Transformation of Industry | 8 | 5.8 | 12.1% |
| Group | 164 | 44.2 | 12.4% |
| of which data centre related (Gas Services + Grid Technologies) | ~15 | – | – |
Source: Siemens Energy Q4 FY2026 analyst presentation, 11 Nov 2026. Segment backlogs are dated 30 September 2026 and sum to €165bn against the group’s €164bn because of rounding and consolidation. Margins are profit before special items.
The signal inside the turbine numbers: reservations, not orders
The more telling figure is in gas turbines. Siemens Energy’s total commitments reached 104 GW at the end of fiscal 2026: 65 GW of firm unit backlog and 39 GW under slot reservation agreements, the analyst presentation shows. Customers ordered 42 GW of new units during the year.
The fourth quarter looked different. New unit orders were about 2 GW, no reservations were converted into orders, and customers signed 14 GW of new reservations. Our calculation: in the quarter, buyers reserved about seven times as much capacity as they ordered, and reservations now make up 37.5% of all commitments.
A slot reservation is a paid place in the factory queue, not a firm order. It protects a delivery date while the buyer waits for a grid connection, a permit or a tenant. That is consistent with what operators tell us: the turbine is no longer the only bottleneck; the site around it is. It also means part of the 104 GW could be released if projects stall. Siemens Energy’s guidance (fiscal 2027 comparable revenue growth of 14-16% and a margin of 14-16%) assumes most of it converts.
Siemens AG: a record order quarter and a faster Smart Infrastructure
A day later Siemens AG, which sells switchgear, building systems and electrification to data centres through Smart Infrastructure, reported record fiscal 2026 orders of €108.2bn and revenue of €83.4bn, a book-to-bill ratio of 1.30, the company said. Fourth-quarter orders rose 58% to €34.8bn, a quarterly record, with a book-to-bill of 1.47. Smart Infrastructure made the largest contribution to fourth-quarter revenue growth.
For fiscal 2027 Siemens guides Smart Infrastructure to comparable revenue growth of 11-13% at a margin of 19.5-20.5%, ahead of the group’s 9-11%. Its outlook says economic growth is “driven mainly by ongoing investment in AI and digital infrastructure”. Siemens did not give a separate data centre order figure in its release.
Industrial AI is an exceptional growth opportunity, and Siemens is built to win in this space.
Together with the third-quarter results we covered on 5 November, when ABB orders rose 40% and Schneider Electric sales 17%, the European power-equipment season is now complete. Every major supplier reported growth from data centres; none reported a slowdown in orders.
What our data shows this week
DC Market Insights tracks four levels: facilities, status, deals and rules. On 13 November our facility tracker held 3,248 data centres in 66 countries run by 548 operators, with 21,462 MW live, 33,369 MW under construction and 73,546 MW planned, for the 1,329 sites with a stated capacity. The newest facility entry is dated 12 November.
| DCMI tracker level | Reading on 13 Nov 2026 | What it says |
|---|---|---|
| Facilities, live | 2,226 sites, 21,462 MW | The installed base with a stated MW |
| Facilities, under construction | 315 sites, 33,369 MW | 1.55 times live capacity (our calculation) |
| Facilities, planned | 707 sites, 73,546 MW | Pipeline (construction + plan) 106.9 GW, 5.0 times live (our calculation) |
| Deals | 79 in October; 19 in November to 9 November | Deal flow steady; 521 deals all time |
| Rules | Policies tracked in 48 countries | Germany alone has 17 tracked actions, 13 in force |
Source: DC Market Insights facility, deal and policy trackers, read 13 Nov 2026 04:52 UTC. MW totals cover only sites with a stated capacity. Facility counts by status include sites without MW.
The ratio matters more than the totals. Under construction capacity is 1.55 times what is already live, and planned capacity is another 3.4 times. If even half of the planned capacity is built, the installed base more than triples, our calculation. That is the demand that Siemens Energy’s 39 GW of reservations is waiting on.
Germany, the suppliers’ home market. Our tracker holds 181 German facilities with 923 MW live, 1,448 MW under construction and 2,937 MW planned. The pipeline of 4,385 MW is 4.75 times live capacity, our calculation, against the federal goal in the national data centre strategy to at least double capacity by 2030. The constraint is grid access: the Netzanschlusspaket, the draft law that reorders grid connections, is still listed as proposed in our Germany power and policy page.
The wider pattern: equipment demand up, public pressure up
The order books and the protests point in opposite directions. On 7 November, activists in Dublin, Helsinki and other European cities protested against new AI data centres, Bloomberg reported, in actions coordinated across 15 countries that call for a freeze on new builds. In Amsterdam, protesters entered a Microsoft data centre construction site, Tom’s Hardware reported, the first of 85 planned actions.
Grid operators, meanwhile, are rationing. Denmark put data centres last in its connection queue, with 16 GW of requests due an answer in late November, as we reported on 2 November. Italy’s grid has received requests for about 100 GW, 1.7 times peak demand. This is the context for Bruch’s warning on unrealistic growth rates: suppliers are full, but many of the sites they are reserving capacity for still lack a grid date.
What it means for operators, investors and vendors
Our view:
- Operators: lock equipment with the grid date, not before it. With 39 GW of turbine reservations ahead of you, a slot without a connection date is cash at risk. Match each reservation to a site with a signed grid offer.
- Investors: read the 9% as a floor. €15bn of Siemens Energy’s backlog is labelled data centre, but utility orders for grid and generation that serve data centre load are not all counted. The exposure is larger than the label.
- Investors: watch conversion, not reservations. In the fourth quarter Siemens Energy converted 0 GW of reservations. Two quarters of low conversion would be the first hard sign that the 107 GW pipeline we track is slipping.
- Vendors: Smart Infrastructure-type products are the fastest lane. Siemens guides 11-13% growth there against 9-11% for the group; switchgear, building systems and power distribution are where data centre demand turns into revenue first.
- Everyone: budget for public scrutiny. 85 planned protest actions and the EU consultation closing on 14 December mean water and energy disclosure will be asked for in permits, not just in reports.
For market sizing, see our Data Center Gas Turbine Market report (US$5.84bn in 2026), the Data Center Onsite Power Generation Market report (US$18.67bn in 2026) and the AI Data Center Market report (US$390.19bn in 2025, 9.04 GW of AI IT load). On that basis, Siemens Energy’s US$16.8bn of data centre backlog equals about 2.9 years of the 2026 data centre gas turbine market, or about 90% of one year of onsite power generation spending, our calculation. Country rules are in our Germany power and policy tracker.
What to watch next
- 17 November 2026: Nvidia reports third-quarter fiscal 2027 results (call at 2 p.m. PT), the next read on AI capital spending.
- Late November 2026: Energinet’s answers to 16 GW of Danish data centre grid requests.
- 14 December 2026: the EU consultation on data centre minimum performance standards closes.
- 8 January 2027: the UK consultation on the national policy statement for data centres closes.
- 11 February 2027: Siemens Energy’s first-quarter fiscal 2027 results, the first test of whether the 14 GW of new reservations converts into orders; its AGM follows on 25 February.
Frequently asked questions
How much of Siemens Energy’s backlog comes from data centres?
About €15bn (US$16.8bn), or 9.1% of its record €164bn order backlog at the end of fiscal 2026, across Gas Services and Grid Technologies, according to Siemens Energy’s 11 November 2026 analyst presentation and Reuters.
How many gas turbines has Siemens Energy committed?
104 GW at 30 September 2026: 65 GW of firm backlog and 39 GW of slot reservations. In the fourth quarter it signed 14 GW of new reservations, about 2 GW of new orders and converted none.
How much data centre capacity is being built worldwide?
DC Market Insights tracks 33.4 GW under construction and 73.5 GW planned against 21.5 GW live across 3,248 facilities in 66 countries (13 November 2026). The pipeline is 5.0 times live capacity.
When does Nvidia report its next results?
On 17 November 2026, with a conference call at 2 p.m. Pacific time, for the third quarter of fiscal 2027, which ended on 25 October 2026.
Sources
- Siemens Energy, “Earnings Release Q4 FY 2026: Siemens Energy reports a record year and targets a margin of 20 to 22 percent by 2030”, 11 Nov 2026. Link
- Siemens Energy, Q4 FY2026 analyst presentation, 11 Nov 2026. Link
- Reuters (via Euronext), “Siemens Energy sees higher margins as data centres boost power equipment demand”, 11 Nov 2026. Link
- Siemens AG, “Earnings Release and Financial Results Q4 FY 2026”, 12 Nov 2026. Link
- NVIDIA, “NVIDIA Sets Conference Call for Third-Quarter Financial Results”, 28 Oct 2026. Link
- Bloomberg, “Dublin, Helsinki Protests Target AI Data Centers Over Environmental Concerns”, 7 Nov 2026. Link
- Tom’s Hardware, “Protesters storm Microsoft AI data center construction site”, Nov 2026. Link
- Federal Ministry for Digital and State Modernisation (BMDS), “Zwischenmonitoring Rechenzentrumsstrategie”. Link
- DC Market Insights, “Denmark put data centres last in its grid queue”, 2 Nov 2026. Link
- DC Market Insights, “AI data centres lifted ABB orders 40% and Schneider sales 17%”, 5 Nov 2026. Link
- DC Market Insights, Germany power and policy tracker and facility tracker, read 13 Nov 2026. Link
- DC Market Insights, Data Center Gas Turbine, Onsite Power Generation and AI Data Center Market reports. Link