
Data Center Onsite Power Generation Market Size, Share & Forecast to 2035
Market at a glance
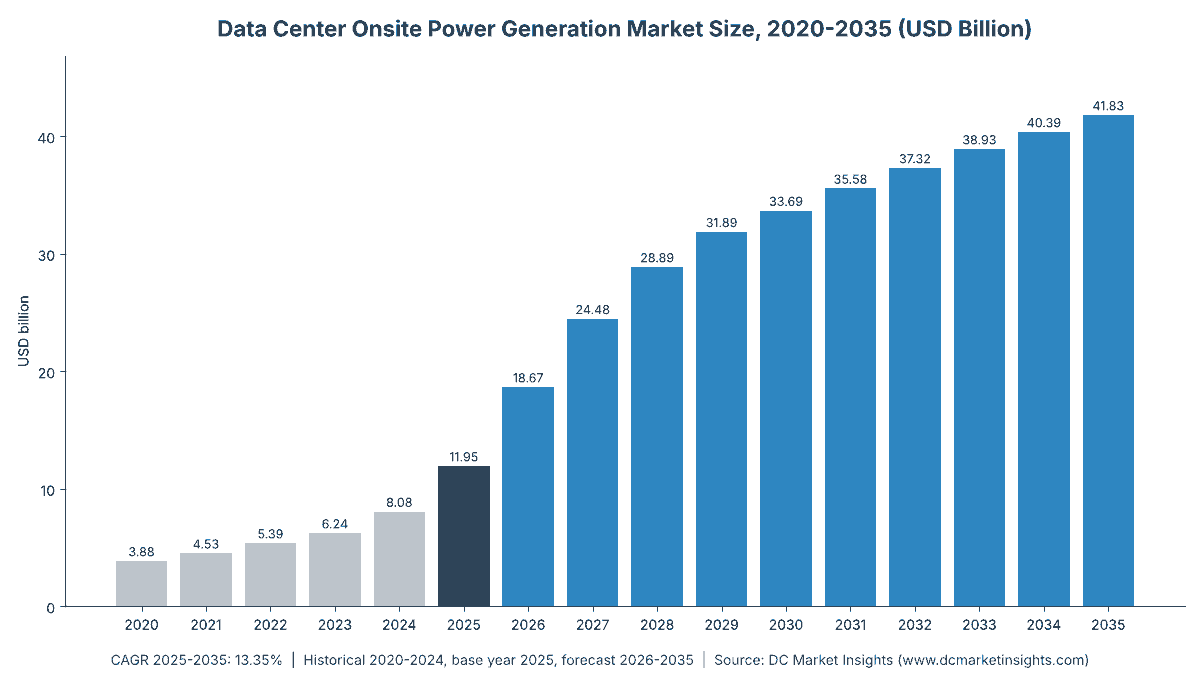
The Data Center Onsite Power Generation market was worth USD 11.95 billion in 2025 and is forecast to reach USD 41.83 billion by 2035, growing at a 13.35% CAGR.
 By Amit Jain, Senior Consultant, ICT & Emerging Technologies
 Reviewed by Deepti Agrawal
Last updated 19 Oct 2026
Base year 2025 PDF + Excel
Key findings
Air Permits Cap Running Hours for Diesel Fleets
What is inside the report
- 01Introduction
- 02Research Methodology
- 03Executive Summary
- 04What Does Onsite Power Generation at a Data Center Include?
- 05Why Do Data Center Onsite Power Generation Market Estimates Differ?
- 06Market Drivers
- 07Market Trends
- 08Market Restraints
- 09Market Opportunities
- 10Pricing Analysis: Onsite Power Generation Cost per kW
- 21chapters
- 2020-2024Historical period
- 2026-2035Forecast period
- —Companies profiled
Segmentation
Recent developments
American Intelligence and Power ordered 2 GW of Caterpillar natural gas generator sets for its Monarch campus (Source: Caterpillar).
Oracle stated its intention to procure up to 2.8 GW of Bloom Energy fuel cells, 1.2 GW contracted (Source: Bloom Energy).
the IEA said 15 to 27 GW of onsite natural gas may power data centres by 2030 (Source: IEA).
Mitsubishi Power announced two M501JAC turbines of about 1,150 MW for onsite power at a Wyoming data center (Source: Mitsubishi Power).
GE Vernova reported data center orders above USD 5 billion in the first half (Source: GE Vernova).
the EPA issued permitting guidance for islanded power generation facilities (Source: EPA).
Caterpillar reported Power and Energy sales up 17% with data center demand for engines and turbines (Source: Caterpillar).
AEP announced a 702 MW fuel cell project in Wyoming for Google, and Mainspring Energy announced an AEP agreement for up to 1.6 GW of linear generators (Source: AEP; Mainspring Energy).
Full analysis
The Data Center Onsite Power Generation Market is valued at USD 18.67 billion in 2026 and is projected to reach USD 41.83 billion by 2035, up from USD 11.95 billion in 2025, a compound annual growth rate (CAGR) of 13.35% from 2025 to 2035 (DC Market Insights estimate). Onsite generation used to mean a row of diesel standby sets that ran a few hours a year; the money is now moving to plants that run every day, because an artificial intelligence (AI) campus that waits for a grid connection earns nothing. The International Energy Agency (IEA) said in April 2026 that around 15 to 27 gigawatts (GW) of onsite natural gas may power data centres by 2030, and Oracle said the same month that it intends to buy up to 2.8 GW of Bloom Energy fuel cells, 1.2 GW of it already contracted. DC Market Insights therefore expects prime and co-located power to rise from 21.8% of spending in 2025 to 43.9% in 2035, while emergency standby falls from 62.9% to 40.1%. Fuel cells are the fastest-growing technology at 26.08% a year, and Middle East and Africa is the fastest-growing region at 22.01% a year.
Key Market Statistics: How Big Is the Data Center Onsite Power Generation Market in 2026?
DC Market Insights values the Data Center Onsite Power Generation Market at USD 18.67 billion in 2026, 56.2% above 2025, as gas turbines and fuel cells ordered for off-grid AI campuses reach commissioning on top of a steady standby generator business.
- Market size 2025: USD 11.95 billion
- Market size 2026: USD 18.67 billion
- Market size 2030: USD 33.69 billion
- Market size 2035: USD 41.83 billion
- CAGR 2025-2035: 13.35% in the base case, 10.81% in the low case and 15.40% in the high case
- Largest technology: reciprocating engine generator sets, 69.6% of 2025 value (USD 8.31 billion)
- Fastest-growing technology: fuel cells, 26.08% a year
- Largest application: emergency standby and backup power, 62.9% of 2025 value (USD 7.52 billion)
- Leading region: North America, 55.9% of 2025 value (USD 6.68 billion)
- Fastest-growing region: Middle East and Africa, 22.01% a year
- Largest country: the United States, USD 6.16 billion in 2025 (51.5% of global value)
- Market leader: Caterpillar, about 19% of 2025 value across generator sets and Solar Turbines (DC Market Insights assessment)
Executive Summary
The Global Data Center Onsite Power Generation Market size was valued at USD 3.88 billion in 2020, reached USD 11.95 billion in 2025, and is anticipated to reach USD 41.83 billion by 2035, at a CAGR of 13.35% during the forecast period.
| Report attribute | Details |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Data Center Onsite Power Generation Market Size 2025 | USD 11.95 Billion |
| Data Center Onsite Power Generation Market Size 2026 | USD 18.67 Billion |
| Data Center Onsite Power Generation Market, CAGR | 13.35% |
| Data Center Onsite Power Generation Market Size 2035 | USD 41.83 Billion |
Onsite power generation spending at data centers grew 25.26% a year from 2020 to 2025. Most of that came from standby generator sets for new halls, which rose from USD 3.60 billion to USD 8.31 billion, but gas turbines went from USD 60.50 million to USD 2.51 billion in the same five years as AI campuses began to energise on their own plants. Growth of 13.35% a year to 2035 rests on a change in what the plant is for: generator sets still grow 9.13% a year with new capacity, while gas turbines (16.39% a year) and fuel cells (26.08% a year) take the role of the main supply. By 2035 the three largest technologies hold 47.6%, 27.4% and 21.2% of a USD 41.83 billion market, against 69.6%, 21.0% and 7.3% in 2025.
Key Takeaways
Five numbers explain where onsite power generation spending at data centers goes between 2025 and 2035.
- The market reaches USD 41.83 billion by 2035, because operators now buy generation to run the campus, not only to back it up.
- Prime and co-located power grows 21.57% a year, because grid connections for loads above 100 MW take years in the busiest markets.
- Natural gas rises from 36.2% to 58.8% of spending, because turbines, gas engines and fuel cells all burn pipeline gas when diesel cannot run every day.
- Fuel cells grow tenfold to USD 8.88 billion, because contracts such as the Oracle order for up to 2.8 GW make them a utility-scale option.
- Standby generator sets still add USD 11.60 billion of annual spending by 2035, because every new hall needs backup whatever its main supply.
What Does Onsite Power Generation at a Data Center Include?
Onsite power generation is any plant inside or next to a data center campus that produces electricity for that campus, and DC Market Insights values the equipment, installation and service at USD 11.95 billion in 2025.
Included. Reciprocating engine generator sets (diesel, hydrotreated vegetable oil (HVO), natural gas and bi-fuel) for emergency standby, prime, bridge and peak shaving duty, with their enclosures, fuel systems, controls and emissions aftertreatment; gas turbines for prime power, bridge power and dedicated co-located plants, with engineering, procurement and construction (EPC) and long-term service; stationary fuel cells (solid oxide, proton exchange membrane, molten carbonate and phosphoric acid) with installation and service; and onsite solar photovoltaic (PV) arrays, linear generators and other small onsite generators.
Excluded. Batteries and uninterruptible power supply (UPS) systems, which store rather than generate electricity; the microgrid controls and switchgear layer, covered in a separate DC Market Insights report on data center microgrids; utility power plants that serve the wider grid; fuel, pipelines and electricity sold under power purchase agreements; and small modular reactors, none of which will run inside a data center fence before 2030. Power distribution inside the data hall is covered in the Data Center Power Market.
How the segments fit together. The four technology lines equal the matching DC Market Insights reports exactly: the Data Center Generator Market (USD 8.31 billion in 2025), the Data Center Gas Turbine Market (USD 2.51 billion) and the Data Center Fuel Cell Market (USD 874.50 million), plus USD 250.00 million of onsite solar, linear generators and other units. Every segment table splits the same USD 11.95 billion of 2025 value, and each split sums to the total in every year from 2020 to 2035.
Why Do Data Center Onsite Power Generation Market Estimates Differ?
Public estimates for onsite data center power differ because some add batteries, microgrids, fuel and utility plants, while DC Market Insights counts USD 18.67 billion of 2026 spending on generating equipment only.
Broader definitions add four things. First, energy storage and UPS systems, which sit next to the generators in most campus power designs but do not produce electricity. Second, microgrid controls and switchgear that tie onsite plants together. Third, utility combined-cycle plants that a power company builds because of data center load but sells into the grid, such as the three Entergy Louisiana plants approved for the Meta campus in August 2025. Fourth, fuel and electricity revenue over the life of the plant. Each of these is a real cost for the operator, but adding them would double count equipment that other reports already size and would blur what a buyer spends on generators, turbines and fuel cells.
| Element | In this market? | Why |
|---|---|---|
| Standby and prime generator sets | Yes (USD 8.31 billion in 2025) | Generate electricity for one campus |
| Gas turbines and fuel cells | Yes (USD 3.39 billion in 2025) | Generate electricity for one campus |
| Onsite solar and linear generators | Yes (USD 250.00 million in 2025) | Generate electricity onsite |
| Batteries and UPS | No | Store electricity |
| Utility plants for general load | No | Serve the wider grid |
| Fuel and power purchase agreements | No | Operating cost, not equipment |
Buyers inside the scope include hyperscale cloud operators, AI cloud developers, colocation providers, enterprise and edge data center owners, and independent power producers that sell electricity only to one campus. Small and medium enterprise (SME) server rooms with portable generators below 100 kilowatts (kW) are counted inside enterprise and edge data centers. Batteries, UPS, microgrid controls, utility plants for general load, fuel supply and power purchase agreements stay outside the scope in every table.
Why Are Data Centers Generating Their Own Power?
Data centers generate their own power because grid capacity arrives years after the buildings, and DC Market Insights expects prime and co-located power to grow from USD 2.60 billion in 2025 to USD 18.36 billion in 2035 as a result.
Large-Load Rules in Texas, PJM and Ireland Make Onsite Supply a Condition
Grid operators now ask large loads to bring their own capacity. Texas Senate Bill 6 set a 75 megawatt (MW) threshold for large loads and lets the Electric Reliability Council of Texas (ERCOT) direct them to run onsite backup generation in emergencies, according to the official Senate bill analysis of August 2025. The Federal Energy Regulatory Commission (FERC) found the co-location tariff of PJM Interconnection unjust and unreasonable in December 2025 and proposed two new transmission services for co-located loads. In Ireland, the Commission for Regulation of Utilities (CRU) decided on 12 December 2025 that new data centres must provide dispatchable onsite or proximate generation or storage matching 100% of their maximum import capacity on a de-rated basis. DC Market Insights links USD 4.08 billion of 2025 prime, co-located and bridge spending to these rules.
Engine and Turbine Makers Report Data Center Demand in Their Results
Caterpillar said its Power and Energy sales rose 17% to USD 8.24 billion in the second quarter of 2026, with large reciprocating engines and turbines growing primarily in data center applications, according to its earnings release of 4 August 2026. Cummins reported Power Systems sales of USD 2.3 billion in the same quarter, up 19%, driven by data center markets in the United States (US), China and Asia Pacific. GE Vernova reported data center orders above USD 5 billion in the first half of 2026, more than double its 2025 total, according to its earnings release of 22 July 2026. These disclosures support the 56.2% jump DC Market Insights models from 2025 to 2026.
The IEA Writes Onsite Gas into Its Data Centre Outlook
The IEA said in its April 2026 update on energy and AI that around 15 to 27 GW of onsite natural gas may power data centres by 2030, mostly in the US. That makes onsite plants part of the official supply picture rather than a stopgap. DC Market Insights places natural gas at 36.2% of 2025 onsite generation spending, USD 4.32 billion, rising to 58.8%, USD 24.57 billion, in 2035.
How Is the Onsite Power Mix at Data Centers Changing?
The onsite mix is moving from diesel standby to gas-fired prime power, and diesel and HVO fall from 58.3% of 2025 spending to 30.3% in 2035 in the DC Market Insights model.
Gigawatt Fleets of Gas Engines Replace Single Standby Sets
Generator orders now arrive in gigawatt blocks. Caterpillar said in January 2026 that American Intelligence and Power had ordered 2 GW of fast-response natural gas generator sets for the first phase of its Monarch campus, and the Joule campus in Utah plans up to 4 GW powered by Caterpillar G3520K gas generator sets with 1.1 gigawatt-hours (GWh) of batteries, according to trade reports from August 2025. Natural gas reciprocating sets grow from USD 1.01 billion in 2025 to USD 6.02 billion in 2035, 19.58% a year, inside the generator line.
Fuel Cells Move from Pilot Racks to Utility-Scale Contracts
Oracle and Bloom Energy said in July 2025 that fuel cells could deliver onsite power for an entire data center within 90 days, and in April 2026 Oracle stated its intention to procure up to 2.8 GW, according to Bloom Energy’s investor release. American Electric Power (AEP) announced a 702 MW fuel cell project near Cheyenne, Wyoming, worth about USD 4 billion, with a 20-year power purchase agreement for Google in October 2026. Fuel cells rise from 7.3% to 21.2% of onsite generation spending between 2025 and 2035.
Linear Generators and Onsite Solar Enter the Utility Order Book
Mainspring Energy said on 13 October 2026 that AEP had bought an initial 190 MW of its linear generators under an agreement for up to 1.6 GW through 2034, which it called the largest procurement of linear generators to date. Units come in 250 kW blocks and run on natural gas, biogas or hydrogen without combustion flames. DC Market Insights groups linear generators with onsite solar PV in a line worth USD 250.00 million in 2025 and USD 1.58 billion in 2035, 20.21% a year.
Market Restraints: What Holds Back Onsite Generation at Data Centers?
Emissions permits and the cost of building spare capacity restrain the market, and the DC Market Insights low case of USD 33.35 billion in 2035 shows the effect of slower turbine and fuel cell adoption.
Air Permits Cap Running Hours for Diesel Fleets
Northern Virginia already hosts more than 4,000 diesel generators with over 11 GW of capacity, according to a January 2026 report by the Virginia Mercury, and local opposition to running them more often is a 2026 legislative issue. The US Environmental Protection Agency (EPA) clarified in May 2025 that certain emergency engines may run up to 50 hours a year in non-emergency conditions, and its subpart KKKKa rule for new combustion turbines took effect on 15 January 2026. These limits keep diesel and HVO growth to 6.18% a year, the slowest fuel group in the model.
Reliable Islanded Supply Needs 30% to 70% Spare Capacity
The IEA said in April 2026 that reliable islanded supply requires overbuilding onsite generation by 30% to 70% relative to demand. At the 2025 model price of USD 1,900 per kW for a gas turbine plant, that means USD 2.47 million to USD 3.23 million of plant per MW of IT load, against USD 0.55 million to USD 0.62 million of standby generator sets per MW. Campuses that cannot finance this overbuild wait for the grid instead, which is why bridge power grows only 12.89% a year.
Where Are the Openings for Onsite Generation Suppliers?
The largest openings are prime power for AI campuses outside North America and the conversion of bridge plants into permanent ones, worth USD 4.13 billion and USD 18.36 billion of 2035 value in the DC Market Insights model.
Gulf and Asian AI Campuses Paired with Local Gas
Middle East and Africa grows from USD 565.64 million in 2025 to USD 4.13 billion in 2035, and Saudi Arabia from USD 185.81 million to USD 1.60 billion, 23.99% a year. Cheap associated gas and new AI campuses make the Gulf the natural market for turbines and gas engines sold as a package with the data center.
Bridge Plants That Stay On as Prime and Backup Supply
Turbines and gas engines bought to wait for the grid rarely leave once the line arrives; they become prime, peak shaving or backup plants. Prime and co-located power reaches USD 18.36 billion in 2035, and peak shaving and grid support grows 17.32% a year to USD 1.73 billion, as operators sell flexibility back to grid operators under rules such as the Texas emergency direction power.
How Much Does Onsite Power Generation Cost per kW?
Onsite generation costs from about USD 550 per kW of IT load for diesel standby sets to USD 3,600 per kW for fuel cells in 2025, according to DC Market Insights unit values.
| Year | Gas turbine plant (USD per kW) | Fuel cell system (USD per kW) | Solar, linear and other (USD per kW) | Solar, linear and other added (MW) |
|---|---|---|---|---|
| 2020 | 1,250 | 4,200 | 1,400 | 60 |
| 2025 | 1,900 | 3,600 | 1,250 | 200 |
| 2030 | 2,150 | 3,000 | 1,150 | 900 |
| 2035 | 2,000 | 2,600 | 1,050 | 1,500 |
Public anchors support the range. The US Energy Information Administration (EIA) put an aeroderivative combustion turbine at USD 2,275 per kW and an industrial frame unit at USD 1,158 per kW in 2025 dollars. The US Department of Energy (DOE) lists today’s natural gas fuel cell equipment at USD 1,200 to USD 4,500 per kW against a target of USD 1,000 per kW. Standby generator sets cost USD 0.62 million per MW of IT load in a conventional hall and USD 0.55 million in an AI hall in 2025, because AI halls use larger 3 MW-class sets.
Which Rules and Standards Govern Data Center Onsite Generation?
Seven rules and standards shape USD 11.95 billion of 2025 onsite generation spending, from US air permits to Irish grid connection policy.
- EPA National Emission Standards for Hazardous Air Pollutants (NESHAP) for engines: May 2025 clarification that certain emergency engines may run up to 50 hours a year in non-emergency conditions.
- EPA New Source Performance Standards (NSPS), 40 CFR 60 subpart KKKKa: effective 15 January 2026 for new stationary combustion turbines (Federal Register).
- EPA islanded generation guidance: 27 July 2026, expands the path for islanded power generation facilities that sell no power to the grid.
- Executive Order 14318: July 2025, faster federal permits for data center projects above 100 MW, naming natural gas turbines as covered components.
- Texas Senate Bill 6: 2025, 75 MW large-load threshold and ERCOT power to direct onsite backup generation.
- Ireland CRU Large Energy Users Connection Policy: December 2025 decision requiring onsite or proximate generation or storage for new data centres.
- NFPA 110-2025 and ISO 8528-1:2018: the National Fire Protection Association standard for emergency and standby power systems, and the International Organization for Standardization ratings for generator sets in continuous, peak-load and standby duty.
Which Technology and Application Lead Onsite Generation Spending?
Reciprocating engine generator sets lead with 69.6% of 2025 value, and emergency standby and backup power leads applications with 62.9%, according to DC Market Insights.
By Technology: Reciprocating Engine Generator Sets Lead with 69.6%
| Technology | 2025 (USD million) | Share 2025 | 2035 (USD million) | CAGR 2025-2035 |
|---|---|---|---|---|
| Reciprocating Engine Generator Sets | 8,313.99 | 69.6% | 19,918.28 | 9.13% |
| Gas Turbines | 2,511.85 | 21.0% | 11,455.56 | 16.39% |
| Fuel Cells | 874.50 | 7.3% | 8,879.20 | 26.08% |
| Onsite Solar and Linear Generators | 250.00 | 2.1% | 1,575.00 | 20.21% |
| Total | 11,950.34 | 100.0% | 41,828.04 | 13.35% |
By Application: Emergency Standby and Backup Power Leads with 62.9%
| Application | 2025 (USD million) | Share 2025 | 2035 (USD million) | CAGR 2025-2035 |
|---|---|---|---|---|
| Emergency Standby and Backup Power | 7,516.13 | 62.9% | 16,758.65 | 8.35% |
| Prime and Co-Located Power | 2,603.17 | 21.8% | 18,362.49 | 21.57% |
| Bridge Power Until Grid Connection | 1,481.62 | 12.4% | 4,981.39 | 12.89% |
| Peak Shaving and Grid Support | 349.42 | 2.9% | 1,725.51 | 17.32% |
| Total | 11,950.34 | 100.0% | 41,828.04 | 13.35% |
By Fuel or Energy Source: Diesel and HVO Lead with 58.3%
| Fuel or energy source | 2025 (USD million) | Share 2025 | 2035 (USD million) | CAGR 2025-2035 |
|---|---|---|---|---|
| Diesel and HVO | 6,967.13 | 58.3% | 12,687.94 | 6.18% |
| Natural Gas | 4,322.38 | 36.2% | 24,574.24 | 18.98% |
| Hydrogen and Biogas Blends | 410.83 | 3.4% | 2,990.86 | 21.96% |
| Solar and Other | 250.00 | 2.1% | 1,575.00 | 20.21% |
| Total | 11,950.34 | 100.0% | 41,828.04 | 13.35% |
By Data Center Type: Hyperscale and AI Data Centers Lead with 54.7%
| Data center type | 2025 (USD million) | Share 2025 | 2035 (USD million) | CAGR 2025-2035 |
|---|---|---|---|---|
| Hyperscale and AI Data Centers | 6,531.35 | 54.7% | 27,431.99 | 15.43% |
| Colocation Data Centers | 2,968.49 | 24.8% | 9,464.82 | 12.29% |
| Enterprise and Edge Data Centers | 2,450.50 | 20.5% | 4,931.23 | 7.24% |
| Total | 11,950.34 | 100.0% | 41,828.04 | 13.35% |
DC Exclusive: Onsite Power Technology Cost Ladder — Six Options from USD 550 to USD 3,600 per kW
DC Market Insights built this cost ladder from 10 inputs taken from government cost assumptions, company releases and its own unit values; it is a modelled estimate that shows what each option costs per kW and what role it plays on a campus.
| Option | Installed cost, 2025 | Typical role | Speed or start fact | Source of cost |
|---|---|---|---|---|
| Diesel standby generator set, AI hall | USD 550 per kW of IT load | Emergency standby | 10-second start for 3 MW-class sets | DC Market Insights unit value |
| Diesel standby generator set, conventional hall | USD 620 per kW of IT load | Emergency standby | 10-second start | DC Market Insights unit value |
| Heavy-duty frame gas turbine | USD 1,158 per kW | Prime power above 1 GW | 1,150 MW Wyoming campus order, May 2026 | EIA, 2025 dollars |
| Aeroderivative gas turbine plant | USD 1,900 to 2,275 per kW | Bridge and prime power | About five minutes to full load | DC Market Insights and EIA |
| Linear generator | Not disclosed | Prime and peak power | 250 kW blocks, 1.6 GW utility agreement | Mainspring Energy |
| Solid oxide fuel cell system | USD 3,600 per kW | Prime power | Power for a data center within 90 days | DC Market Insights; DOE range USD 1,200 to 4,500 |
The ladder shows why the mix changes. A standby set is the cheapest way to cover an outage but cannot run every day under most air permits. A turbine or fuel cell plant costs three to six times more per kW, and an islanded campus must overbuild it by 30% to 70%, yet it lets the campus earn revenue years before the grid arrives. At a rental value of AI capacity measured in millions of US dollars per MW a year, that trade favours the expensive option, which is why prime and co-located power grows 21.57% a year while standby grows 8.35%.
Which Region Spends the Most on Data Center Onsite Power Generation?
North America leads with 55.9% of 2025 value, or USD 6.68 billion, and Middle East and Africa is the fastest-growing region at 22.01% a year.
North America Leads with 55.9% Share
North American onsite generation spending rises from USD 6.68 billion in 2025 to USD 20.86 billion in 2035, a CAGR of 12.06%. Gas turbines and fuel cells hold 43.3% of the region’s 2025 value, far more than anywhere else, because Texas, Wyoming and Ohio campuses build plants to avoid grid queues.
Asia Pacific Holds 21.6% Share
Asia Pacific grows from USD 2.58 billion to USD 9.61 billion, 14.07% a year. China buys USD 947.48 million of mostly diesel standby sets in 2025, while South Korea and Japan lead fuel cell use under hydrogen power policies.
Europe Holds 14.1% Share
Europe grows from USD 1.68 billion to USD 5.21 billion, 11.97% a year. Ireland’s December 2025 connection policy and the switch from diesel to HVO in Nordic standby fleets, such as the 32 MTU sets at EcoDataCenter’s Falun site, shape the region.
Middle East and Africa Is the Fastest-Growing Region at 22.01%
Middle East and Africa grows from USD 565.64 million to USD 4.13 billion, as Saudi Arabia and the United Arab Emirates (UAE) pair AI campuses with gas turbines and engines.
Latin America Holds 3.7% Share
Latin America grows from USD 442.93 million to USD 2.01 billion, 16.35% a year, led by Brazil and Mexico, where transmission to new campus sites lags.
Which Countries Spend the Most on Onsite Data Center Power?
The United States spends USD 6.16 billion on onsite data center generation in 2025, 51.5% of the global total, and Saudi Arabia is the fastest-growing large country at 23.99% a year.
| Rank | Country | 2025 (USD million) | 2035 (USD million) | CAGR 2025-2035 | Region |
|---|---|---|---|---|---|
| 1 | United States | 6,155.62 | 18,922.02 | 11.88% | North America |
| 2 | China | 947.48 | 2,360.54 | 9.56% | Asia Pacific |
| 3 | Canada | 470.66 | 1,772.80 | 14.18% | North America |
| 4 | United Kingdom | 354.13 | 1,079.30 | 11.79% | Europe |
| 5 | Japan | 352.67 | 1,447.99 | 15.17% | Asia Pacific |
| 6 | Germany | 306.96 | 952.77 | 11.99% | Europe |
| 7 | India | 260.50 | 1,588.63 | 19.82% | Asia Pacific |
| 8 | Australia | 205.44 | 752.84 | 13.87% | Asia Pacific |
| 9 | Brazil | 195.64 | 842.45 | 15.72% | Latin America |
| 10 | Saudi Arabia | 185.81 | 1,595.20 | 23.99% | Middle East and Africa |
| 11 | France | 168.56 | 388.17 | 8.70% | Europe |
| 12 | Netherlands | 145.36 | 277.74 | 6.69% | Europe |
The United States stays the largest buyer through 2035, though its share eases from 51.5% to 45.2% as Gulf and Asian campuses add plants. Saudi Arabia, at 23.99% a year, and India, at 19.82% a year, grow fastest among large countries because both add AI campus capacity faster than transmission (DC Market Insights allocation).
How Could the 2035 Onsite Power Generation Forecast Change?
The 2035 market ranges from USD 33.35 billion to USD 50.06 billion around the USD 41.83 billion base case, depending on how fast turbines, fuel cells and new generator capacity are adopted.
| Scenario | 2035 (USD million) | CAGR 2025-2035 | Assumption |
|---|---|---|---|
| Low | 33,350.66 | 10.81% | Low cases of the generator, turbine and fuel cell models; solar and other 20% lower |
| Base | 41,828.04 | 13.35% | Model as described |
| High | 50,058.63 | 15.40% | High cases of the three models; solar and other 20% higher |
The low case follows faster grid connections under the FERC and Texas rules, which shrink bridge and prime demand; the high case follows wider use of islanded plants under the July 2026 EPA guidance and more utility fuel cell contracts like the AEP project in Wyoming.
Who Are the Leading Data Center Onsite Power Generation Companies?
Caterpillar leads with about 19% of 2025 value, and the top five suppliers hold about 55% (DC Market Insights assessment based on supplier results and named data center deals).
- Caterpillar (including Solar Turbines)
- Cummins
- Rolls-Royce Power Systems
- GE Vernova
- Bloom Energy
- Generac
- Rehlko
- Mitsubishi Heavy Industries
- Siemens Energy
- Baker Hughes
- Wärtsilä
- FuelCell Energy
- Doosan Fuel Cell
- Mainspring Energy
- Kirloskar Oil Engines
The concentration estimate of about 55% combines Caterpillar (about 19%), Cummins (about 14%), Rolls-Royce Power Systems (about 8%), GE Vernova (about 8%) and Bloom Energy (about 6%). Bloom Energy reported 2025 revenue of USD 2.02 billion, up 37.3%, according to its February 2026 results. Rolls-Royce said in June 2025 that its sales of power generation products for data centers grew almost 50% and that production at its Mankato, Minnesota plant would rise by more than 120% by 2026. Generac expects commercial and industrial product sales to rise in the 30% range in 2026, mainly from data center customers. Siemens Energy reported record Gas Services orders in its third fiscal quarter of 2026 that included large orders related to data centers.
Recent Developments
Eight dated events from 2026 show orders, rules and new technologies moving into onsite generation.
- In January 2026, American Intelligence and Power ordered 2 GW of Caterpillar natural gas generator sets for its Monarch campus (Source: Caterpillar).
- In April 2026, Oracle stated its intention to procure up to 2.8 GW of Bloom Energy fuel cells, 1.2 GW contracted (Source: Bloom Energy).
- In April 2026, the IEA said 15 to 27 GW of onsite natural gas may power data centres by 2030 (Source: IEA).
- In May 2026, Mitsubishi Power announced two M501JAC turbines of about 1,150 MW for onsite power at a Wyoming data center (Source: Mitsubishi Power).
- In July 2026, GE Vernova reported data center orders above USD 5 billion in the first half (Source: GE Vernova).
- In July 2026, the EPA issued permitting guidance for islanded power generation facilities (Source: EPA).
- In August 2026, Caterpillar reported Power and Energy sales up 17% with data center demand for engines and turbines (Source: Caterpillar).
- In October 2026, AEP announced a 702 MW fuel cell project in Wyoming for Google, and Mainspring Energy announced an AEP agreement for up to 1.6 GW of linear generators (Source: AEP; Mainspring Energy).
Methodology: How DC Market Insights Sizes the Data Center Onsite Power Generation Market
DC Market Insights sizes the market as the sum of four bottom-up technology models, which gives USD 11.95 billion in 2025 and USD 41.83 billion in 2035.
The model in numbers: generator sets from new IT capacity of 12.0 GW in 2025 and 27.0 GW in 2035 at USD 0.62 million per MW in conventional halls and USD 0.55 million in AI halls, plus replacement on the installed base and USD 618.40 million of prime and bridge sets (USD 8.31 billion in 2025); gas turbines from 1,300 MW commissioned in 2025 and 4,700 MW in 2035 at USD 1,900 and USD 2,000 per kW plus service (USD 2.51 billion); fuel cells from 220 MW installed in 2025 and 2,600 MW in 2035 at USD 3,600 and USD 2,600 per kW plus service (USD 874.50 million); and onsite solar, linear generators and other units from 200 MW in 2025 and 1,500 MW in 2035 at a blended USD 1,250 and USD 1,050 per kW (USD 250.00 million). Application, fuel, data center type, regional and country splits add up the matching splits of the four models, so every table sums to the total in every year.
Three bound checks test the result. Ceiling one: the onsite prime and bridge turbine fleet (about 14 GW) and the fuel cell fleet (about 7 GW) reach about 21 GW by 2030 in the model, inside the IEA range of 15 to 27 GW of onsite gas. Ceiling two: the 2025 generator line of USD 8.31 billion equals about one quarter of Caterpillar’s annualised Power and Energy sales, and Caterpillar is only one of several large engine suppliers serving many markets. Floor: GE Vernova’s data center orders above USD 5 billion in six months equal 26.8% of the modelled 2026 market from a single supplier. The full approach is described on the DC Market Insights research methodology page.
Table of contents
- 01Introduction
- 1.1Market Definition
- 1.2Historical Period, Base Year and Forecast Period
- 1.3Report Attributes
- 02Research Methodology
- 2.1The Four-Technology Model in Numbers
- 2.2Bound Checks: IEA Onsite Gas Ceiling, Caterpillar Sales Ceiling and GE Vernova Order Floor
- 03Executive Summary
- 3.1Market Snapshot, 2025, 2026 and 2035
- 3.2Key Market Statistics
- 3.3Key Takeaways
- 04What Does Onsite Power Generation at a Data Center Include?
- 4.1Included: Generator Sets, Gas Turbines, Fuel Cells, Onsite Solar and Linear Generators
- 4.2Excluded: Batteries, UPS, Microgrid Controls, Utility Plants and Fuel
- 4.3How the Segments Fit Together
- 05Why Do Data Center Onsite Power Generation Market Estimates Differ?
- 5.1Storage, Microgrids, Utility Plants and Fuel in Broader Definitions
- 5.2Scope Comparison: What Is In and Out
- 5.3Buyers Inside the Scope
- 06Market Drivers
- 6.1Large-Load Rules in Texas, PJM and Ireland Make Onsite Supply a Condition
- 6.2Engine and Turbine Makers Report Data Center Demand in Their Results
- 6.3The IEA Writes Onsite Gas into Its Data Centre Outlook
- 07Market Trends
- 7.1Gigawatt Fleets of Gas Engines Replace Single Standby Sets
- 7.2Fuel Cells Move from Pilot Racks to Utility-Scale Contracts
- 7.3Linear Generators and Onsite Solar Enter the Utility Order Book
- 08Market Restraints
- 8.1Air Permits Cap Running Hours for Diesel Fleets
- 8.2Reliable Islanded Supply Needs 30% to 70% Spare Capacity
- 09Market Opportunities
- 9.1Gulf and Asian AI Campuses Paired with Local Gas
- 9.2Bridge Plants That Stay On as Prime and Backup Supply
- 10Pricing Analysis: Onsite Power Generation Cost per kW
- 10.1Gas Turbine, Fuel Cell and Other Prices, 2020-2035
- 10.2Public Anchors: EIA Turbine Costs and DOE Fuel Cell Costs
- 11Standards and Regulation
- 11.1EPA NESHAP Clarification for Emergency Engines
- 11.2EPA NSPS 40 CFR 60 Subpart KKKKa
- 11.3EPA Islanded Generation Guidance
- 11.4Executive Order 14318
- 11.5Texas Senate Bill 6
- 11.6Ireland CRU Large Energy Users Connection Policy
- 11.7NFPA 110-2025 and ISO 8528-1:2018
- 12Data Center Onsite Power Generation Market, By Technology
- 12.1Reciprocating Engine Generator Sets
- 12.2Gas Turbines
- 12.3Fuel Cells
- 12.4Onsite Solar and Linear Generators
- 13Data Center Onsite Power Generation Market, By Application
- 13.1Emergency Standby and Backup Power
- 13.2Prime and Co-Located Power
- 13.3Bridge Power Until Grid Connection
- 13.4Peak Shaving and Grid Support
- 14Data Center Onsite Power Generation Market, By Fuel or Energy Source
- 14.1Diesel and HVO
- 14.2Natural Gas
- 14.3Hydrogen and Biogas Blends
- 14.4Solar and Other
- 15Data Center Onsite Power Generation Market, By Data Center Type
- 15.1Hyperscale and AI Data Centers
- 15.2Colocation Data Centers
- 15.3Enterprise and Edge Data Centers
- 16DC Exclusive: Onsite Power Technology Cost Ladder
- 16.1Six Options from USD 550 to USD 3,600 per kW
- 16.2Why Prime Power Grows Faster than Standby
- 17Regional Insights
- 17.1North America
- 17.2Asia Pacific
- 17.3Europe
- 17.4Middle East and Africa
- 17.5Latin America
- 18Country Analysis
- 18.1United States
- 18.2China
- 18.3Canada
- 18.4United Kingdom
- 18.5Japan
- 18.6Germany
- 18.7India
- 18.8Australia
- 18.9Brazil
- 18.10Saudi Arabia
- 18.11France
- 18.12Netherlands
- 19Forecast Scenarios, 2035
- 19.1Low Case
- 19.2Base Case
- 19.3High Case
- 20Competitive Insights
- 20.1Caterpillar (including Solar Turbines)
- 20.2Cummins
- 20.3Rolls-Royce Power Systems
- 20.4GE Vernova
- 20.5Bloom Energy
- 20.6Generac
- 20.7Rehlko
- 20.8Mitsubishi Heavy Industries
- 20.9Siemens Energy
- 20.10Baker Hughes
- 20.11Wärtsilä
- 20.12FuelCell Energy
- 20.13Doosan Fuel Cell
- 20.14Mainspring Energy
- 20.15Kirloskar Oil Engines
- 21Recent Developments
- 21.1Dated Events, January to October 2026
- Fig. 1Data Center Onsite Power Generation Market Size, 2020-2035 (USD Million)
- Table 1Report Attributes
- Table 2Scope Comparison
- Table 3Gas Turbine, Fuel Cell and Other Prices, 2020-2035
- Table 4Market by Technology, 2025 and 2035
- Table 5Market by Application, 2025 and 2035
- Table 6Market by Fuel or Energy Source, 2025 and 2035
- Table 7Market by Data Center Type, 2025 and 2035
- Table 8Onsite Power Technology Cost Ladder
- Table 9Top 12 Countries, 2025 and 2035
- Table 10Forecast Scenarios, 2035
About this report
Written by Amit Jain and reviewed by Deepti Agrawal, Senior Editor, Research. Figures are built top-down and bottom-up and reconciled before publication, with 2025 as the base year.
Read our methodologyHow we built this
- Historical period2020-2024
- Base year2025
- Forecast period2026-2035
- Sizing approachTop-down + bottom-up
Need more than the report?
Advisory on this market
Due diligence, site selection and market entry work, by the analysts who wrote this report.
See consulting servicesFrequently asked questions
USD 18.67 billion in 2026, up 56.2% from USD 11.95 billion in 2025, according to DC Market Insights estimates. The market is projected to reach USD 41.83 billion by 2035, a CAGR of 13.35% from 2025.
13.35% a year from 2025 to 2035, after 25.26% a year from 2020 to 2025, because AI campuses add gas turbines and fuel cells for daily prime power on top of standby generator sets.
USD 4.08 billion of 2025 spending went to prime, co-located and bridge power, because grid connections for loads above 100 MW take years. Onsite plants let a campus run before the utility line arrives.
69.6% of 2025 value, or USD 8.31 billion, goes to reciprocating engine generator sets, mostly diesel standby. Fuel cells grow fastest at 26.08% a year, to USD 8.88 billion in 2035.
From about USD 550 per kW of IT load for diesel standby sets to USD 1,900 per kW for a gas turbine plant and USD 3,600 per kW for fuel cells in 2025 (DC Market Insights unit values).
15 to 27 GW of onsite natural gas may power data centres by 2030, mostly in the United States, according to the IEA. Natural gas rises to 58.8% of onsite generation spending by 2035 in the DC Market Insights model.
55.9% of 2025 value, or USD 6.68 billion, is spent in North America. Middle East and Africa grows fastest at 22.01% a year, and Saudi Arabia is the fastest-growing large country at 23.99%.
About 19% of 2025 value is held by Caterpillar across generator sets and Solar Turbines (DC Market Insights assessment). Cummins, Rolls-Royce Power Systems, GE Vernova and Bloom Energy follow; the top five hold about 55%.
No: emergency standby still grows to USD 16.76 billion by 2035, 8.35% a year, because every hall needs backup. Its share falls from 62.9% to 40.1% as prime power grows faster.
USD 18.67 billion in 2026 is the DC Market Insights figure for generating equipment only. Estimates that add batteries, UPS, microgrid controls, utility plants or fuel and electricity sales are larger.
Licences, delivery and payment
Which licence should I choose?
Single User is a view-only PDF for one person. Multi User adds a printable PDF and the Excel data for unlimited users at one location. Enterprise covers your whole company and includes 100 free analyst hours.
How and when will I receive the report?
By email, within 24–48 business hours of payment, in the formats of your licence.
How can I pay?
Securely through PayPal: with a PayPal account, a debit or credit card, or PayPal Pay Later where available. Prices are in US dollars.
Can I see a sample first?
Yes. Request a free sample and we will email it to you.
Can the report be tailored to my needs?
Yes. We can add countries, segments or data cuts. Talk to an analyst about the scope you need.
Can I get an invoice or pay against a purchase order?
Write to sales@dcmarketinsights.com and our team will help.