
White Box Server Market Size, Share & Forecast to 2035
Market at a glance
The White Box Server market was worth USD 187.45 billion in 2025 and is forecast to reach USD 745.82 billion by 2035, growing at a 14.81% CAGR. North America accounts for 60.1% of the market.
 By Amit Jain, Senior Consultant, ICT & Emerging Technologies
 Reviewed by Deepti Agrawal
Last updated 7 Oct 2026
Base year 2025 PDF + Excel
Source: DC Market Insights analysis
Key findings
Hyperscalers Buy 83.3% of White Box Servers as Operator Capex Nears USD 750 Billion
Rack-Scale Systems Reach 61.9% of White Box Value by 2035
Samsung DDR5 Module Prices Rose 60% in Two Months
GPU and Neocloud Providers Buy USD 80.20 Billion of White Box Servers by 2035
What is inside the report
- 01Introduction
- 02Research Methodology
- 03Executive Summary
- 04Market Dynamics
- 05Pricing Analysis
- 06Standards and Regulation
- 07Supply Chain and Manufacturing Footprint
- 08Market Size and Forecast
- 09White Box Server Market, by Server Type
- 10White Box Server Market, by Integration Level
- 21chapters
- 2020-2024Historical period
- 2026-2035Forecast period
- 12Companies profiled
Regional insights
- North America60.1%
- Asia Pacific27.9%
- Europe8.1%
- Middle East and Africa2.4%
- Latin America1.5%
Segmentation
Companies profiled
- Foxconn (Hon Hai Precision Industry)
- Quanta Computer
- Wiwynn
- Wistron
- Inventec
- Celestica
- MiTAC Computing Technology
- Pegatron
- Sanmina
- Jabil
- Gigabyte Technology
- ASRock Rack
Recent developments
NVIDIA said it would build AI supercomputers in the United States with Foxconn in Houston and Wistron in Dallas, with mass production expected to ramp within 12 to 15 months (Source: NVIDIA blog post).
Meta introduced the Open Rack Wide specification for double-wide AI racks at the OCP Global Summit, and AMD showed its Helios rack built to the standard (Source: IEEE ComSoc Technology Blog report).
OpenAI and Foxconn agreed to co-design multiple generations of AI data center racks, with Foxconn to manufacture data center equipment in the United States and no purchase commitment in the initial agreement (Source: OpenAI announcement).
Celestica reported 2025 revenue of USD 12.39 billion, up 28%, and raised its 2026 revenue outlook to USD 17.0 billion (Source: Celestica earnings release).
Foxconn reported second-quarter revenue of NT$2.53 trillion, up 41%, and said its AI rack shipments are expected to more than double in 2026 (Source: I-Connect007 news report).
Wiwynn said its Socorro, Texas plant, which started mass production in the first quarter of 2026, has a second building due to begin production in the second quarter of 2027 (Source: Taipei Times news report).
Full analysis
The White Box Server Market covers servers that original design manufacturers (ODMs) build to a buyer’s own design or to an open specification and sell directly to the data center operator without an original equipment manufacturer (OEM) brand: general-purpose and storage-dense servers, AI and accelerated servers, rack-scale systems and the motherboards and sub-assemblies that large buyers integrate themselves. DC Market Insights values the global White Box Server Market at USD 187.45 billion in 2025 and forecasts USD 745.82 billion by 2035, a CAGR of 14.81%. The 2025 value is built from units and prices: about 5.85 million general-purpose and storage-dense white box servers at an average selling price of roughly USD 8,290 give USD 48.50 billion, and about 0.79 million AI and accelerated white box servers at roughly USD 175,890 each give USD 138.95 billion. Custom ASIC servers are the fastest-growing segment at 24.76% a year because hyperscalers have their own accelerators built by ODMs, and the Middle East and Africa is the fastest-growing region at 18.81% a year as, in the DC Market Insights view, sovereign AI campuses in Saudi Arabia and the United Arab Emirates buy more rack-scale systems direct from ODMs.
Executive Summary
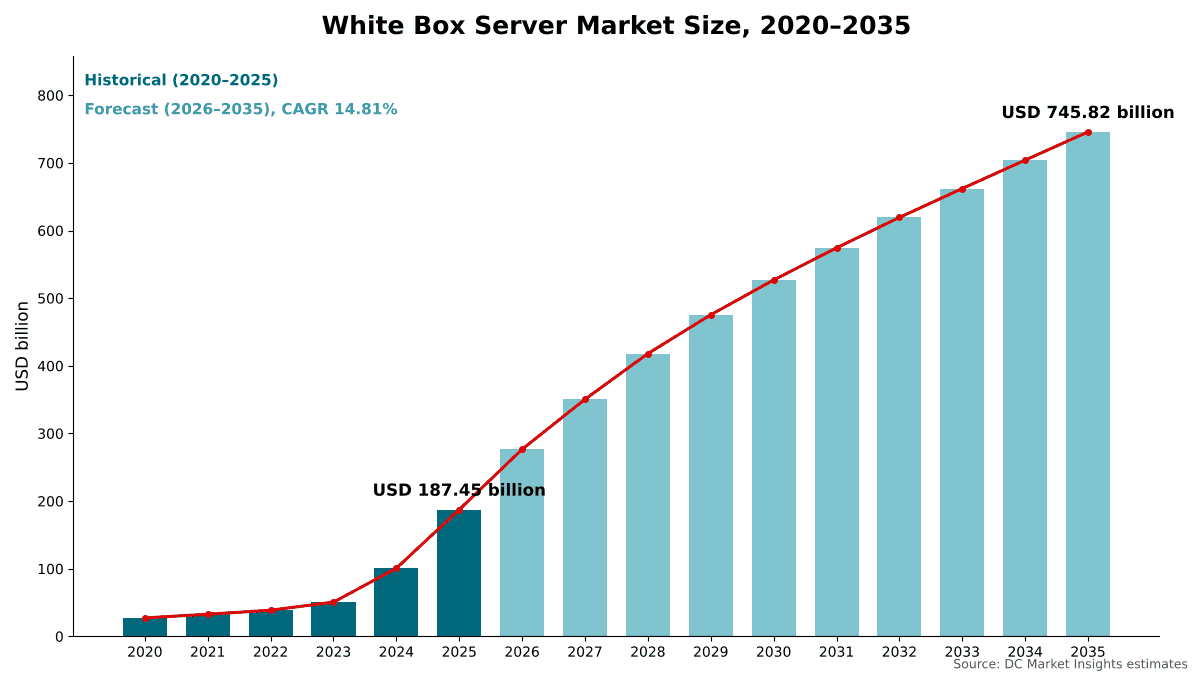
The Global White Box Server Market size was valued at USD 27.33 billion in 2020, reached USD 187.45 billion in 2025, and is anticipated to reach USD 745.82 billion by 2035, at a CAGR of 14.81% during the forecast period.
| Report attribute | Details |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| White Box Server Market Size 2025 | USD 187.45 Billion |
| White Box Server Market, CAGR | 14.81% |
| White Box Server Market Size 2035 | USD 745.82 Billion |
White box spending grew at 46.98% a year between 2020 and 2025, far faster than the server market as a whole, and 2025 alone added 86.0% over 2024 as hyperscalers took delivery of rack-scale GPU systems and large fleets of custom accelerator servers. White box servers made up 51.3% of the USD 365.40 billion Data Center Server Market in 2025, up from 31.2% in 2020, and DC Market Insights forecasts 56.8% by 2035.
DC Market Insights expects a further 47.6% rise in 2026, to USD 276.63 billion, before growth settles below 10% a year after 2030 as accelerator prices per unit of compute fall and the largest buyers finish their first rack-scale build cycle. The ODM order books support the near-term path: Wiwynn reported first-half 2026 revenue of NT$554.66 billion, up 41.7%, and Foxconn expects its AI rack shipments to more than double in 2026.
Market Scope: What Does the White Box Server Market Cover?
The White Box Server Market covers unbranded servers built by ODMs and sold directly to the operator that runs them, valued at first sale in current US dollars, with 2025 as the base year and forecasts to 2035. DC Market Insights sizes it at USD 187.45 billion in 2025, the ODM-direct part of the server market.
Included. General-purpose rack and multi-node servers, storage-dense servers, AI and accelerated servers carrying graphics processing units (GPUs), custom application-specific integrated circuits (ASICs), field-programmable gate arrays (FPGAs) or other accelerators, rack-scale systems integrated and tested at the ODM factory (L11), complete server systems (L10), and motherboards and sub-assemblies (L6) sold to buyers that finish the integration in their own facilities. Servers built to Open Compute Project (OCP) designs, to a hyperscaler’s in-house design and to an ODM’s own reference design all count when they are sold without an OEM brand.
Excluded. Servers that ODMs build for branded OEMs and that are resold under the OEM’s name (these sit in the branded part of the server market), GPU baseboards and compute modules that ODMs sell to chip suppliers, network switches, storage arrays, edge and embedded servers outside data center buildings, software and support contracts, and installation labor.
How the segments fit together. The server-type, integration-level, processor-architecture, end-user and region splits each re-cut the same USD 187.45 billion. The accelerator-type split covers only AI and accelerated white box servers, worth USD 138.95 billion in 2025.
Market Drivers: What Drives the White Box Server Market?
Three drivers explain most of the growth in the White Box Server Market: data center operator capital spending that BloombergNEF sees close to USD 750 billion in 2026, custom ASIC servers that only ODMs build, and new US factory capacity for rack-scale systems.
Hyperscalers Buy 83.3% of White Box Servers as Operator Capex Nears USD 750 Billion
The largest cloud operators design their own servers and buy them from ODMs at volume, so white box demand follows their capital budgets. BloombergNEF expects the capital expenditure of the 14 largest publicly owned data center operators to come close to USD 750 billion in 2026, against a little less than USD 450 billion in 2025. DC Market Insights estimates that hyperscale cloud providers bought USD 156.20 billion of white box servers in 2025, 83.3% of the market, and forecasts USD 585.00 billion by 2035. The ODMs that serve them grew with that budget: Wiwynn’s 2025 revenue rose 163.7% to NT$950.66 billion, and Quanta reported record 2025 sales of NT$2.124 trillion, up 50.5%, with AI servers above 70% of its server revenue in the fourth quarter.
Custom ASIC Servers Grow from USD 39.95 Billion to USD 365.00 Billion
Hyperscalers that design their own accelerators to cut the cost of inference need a manufacturer that builds the server around a chip no OEM sells, which makes custom ASIC servers almost entirely a white box product. DC Market Insights values custom ASIC white box servers at USD 39.95 billion in 2025, 28.8% of accelerated white box value, and forecasts USD 365.00 billion by 2035, a CAGR of 24.76%. Inventec expects about 50% of its AI server shipments in 2026 to be ASIC-based, up from 40% in 2025, after its AI server business grew 40% in 2025. The chips inside these systems are covered in our Data Center Chip Market report.
US Rack-Scale Capacity Moves Closer to the Buyer
ODMs are building final assembly near the largest US campuses. In April 2025, NVIDIA said it had commissioned more than a million square feet of manufacturing space to build and test Blackwell chips in Arizona and AI supercomputers in Texas, with Foxconn in Houston and Wistron in Dallas, and that it plans to produce up to half a trillion dollars of AI infrastructure in the United States within four years. Wistron’s two complexes near Fort Worth, in the same Dallas–Fort Worth area, cover 1.09 million square feet, an investment of USD 761 million. Wiwynn has invested USD 1.6 billion in its El Paso County site in Socorro, Texas, which started mass production in the first quarter of 2026 and mainly focuses on rack-scale general-purpose and ASIC servers.
Market Trends: How Is the White Box Server Changing?
The White Box Server Market is shifting from single servers to complete racks, from x86 toward Arm host processors, and from proprietary designs toward open rack and module standards.
Rack-Scale Systems Reach 61.9% of White Box Value by 2035
Large AI buyers now order complete racks with compute trays, switch trays, power shelves and liquid cooling, integrated and tested at the ODM. DC Market Insights values rack-scale white box systems (L11) at USD 78.35 billion in 2025, 41.8% of the market, and forecasts USD 462.00 billion by 2035, a CAGR of 19.42%. Foxconn said in August 2026 that its AI rack shipments are expected to more than double for the full year.
Arm Host Processors Reach Half of White Box Value
Arm said in April 2025 that close to 50% of the compute shipped to top hyperscalers in 2025 would be Arm-based, through chips such as AWS Graviton, Google Cloud Axion and Microsoft Cobalt, and those processors ship in servers built by ODMs. DC Market Insights estimates that white box servers with Arm host processors were worth USD 62.80 billion (33.5%) in 2025 and grow at 20.49% a year to USD 405.00 billion by 2035, when they overtake x86 at 54.3% of the market.
Open Specifications Widen the Supplier Base
Open designs let a buyer source the same server from more than one ODM. The OCP Data Center Modular Hardware System (DC-MHS) workstream standardizes Host Processor Module form factors so that modules and platforms from different suppliers can work together, and in October 2025 Meta introduced the Open Rack Wide (ORW) specification for double-wide racks at the OCP Global Summit, with AMD showing its Helios rack-scale platform built to the new standard. Rack mechanics and power are covered in our OCP Rack Market report.
Market Challenges: What Holds the White Box Server Market Back?
Memory costs, thin ODM margins and customer concentration are the constraints that DC Market Insights expects to shape the White Box Server Market in 2026 and 2027.
Samsung DDR5 Module Prices Rose 60% in Two Months
Memory is a large share of a white box server’s bill of materials, and in the DC Market Insights view most hyperscale contracts pass component costs through to the buyer. Reuters reported in November 2025 that Samsung’s contract price for 32GB DDR5 memory modules had risen to USD 239 from USD 149 in September, an increase of about 60%. DC Market Insights attributes part of the 2026 rise in general-purpose white box value to higher memory prices and expects the effect to fade after 2027.
A Few Buyers Set Volumes and Prices
Hyperscale cloud providers account for 83.3% of white box value in 2025, so a pause by one or two buyers moves the whole market. In the DC Market Insights view, ODM revenue also carries pass-through components such as GPUs and memory, which raises sales faster than profit, and ODMs answer the concentration risk with US plants and long-term design partnerships rather than spot orders.
Market Opportunities: Where Are the New Revenue Pools?
The two largest new revenue pools in the White Box Server Market are GPU and neocloud providers, growing at 19.03% a year, and government and sovereign AI buyers, growing at 18.42% a year.
GPU and Neocloud Providers Buy USD 80.20 Billion of White Box Servers by 2035
Specialist GPU cloud operators spent USD 14.05 billion on white box servers in 2025, 97.5% of it on accelerated systems, and DC Market Insights forecasts USD 80.20 billion in 2035, more than five times the 2025 level. AI labs are also moving upstream into rack design: in November 2025, OpenAI and Foxconn agreed to co-design multiple generations of AI data center racks, with Foxconn to manufacture cabling, networking, cooling and power systems in the United States and OpenAI holding an option to buy the systems.
Sovereign AI Buyers Grow White Box Spend to USD 38.50 Billion
Governments, national AI companies and state-backed research centers spent USD 7.10 billion on white box servers in 2025, and DC Market Insights forecasts USD 38.50 billion in 2035.
Pricing: How Much Does a White Box Server Cost?
A general-purpose white box server sold for about USD 8,290 on average in 2025, and an AI or accelerated white box server for about USD 175,890. These are DC Market Insights estimates of the average selling price at first sale, including memory, drives and network cards shipped inside the server.
| Average selling price (USD thousand) | 2020 | 2025 | 2030 | 2035 |
|---|---|---|---|---|
| General-purpose and storage-dense white box server | 6.31 | 8.29 | 11.23 | 12.31 |
| AI and accelerated white box server | 80.00 | 175.89 | 269.65 | 284.44 |
| AI share of white box server units | 0.9% | 11.9% | 18.4% | 20.7% |
White box prices sit below branded equivalents because the ODM carries no channel or brand costs. General-purpose prices rise about 4.0% a year to 2035 as core counts and memory per server grow. AI server prices rise fastest to 2030 as rack-scale trays carry more accelerators and larger memory stacks, then flatten as custom ASIC servers, which sell for less per unit than flagship GPU systems, take a larger share.
Standards and Regulation: Which Rules Shape White Box Servers?
Three sets of rules shape white box server design: OCP hardware specifications, the European Union ecodesign regulation for servers, and the rack standards that hyperscalers publish through OCP.
OCP DC-MHS. The OCP Data Center Modular Hardware System project standardizes Host Processor Module form factors, including M-FLW (full width), M-DNO (partial width, density optimized) and M-SDNO, plus M-CRPS common redundant power supplies, so that a buyer can mix modules and platforms from different suppliers.
EU Regulation 2019/424. The Commission Regulation (EU) 2019/424 on ecodesign requirements for servers and data storage products has applied since 1 March 2020. It sets idle state power base limits of 25 W for single-socket and 38 W for two-socket servers and minimum active state efficiency of 9.0 and 9.5, and it excludes, among others, servers with more than four processor sockets, large servers and fully fault tolerant servers. White box servers deployed in the EU must meet the same limits as branded ones.
Open Rack Wide. Meta’s ORW specification, introduced at the OCP Global Summit in October 2025, defines double-wide racks for the power, cooling and serviceability needs of AI systems, which lets ODMs build to one published rack rather than one design per customer.
Market Segmentation: Which Segment Leads the White Box Server Market?
AI and accelerated servers lead the White Box Server Market with 74.1% of 2025 value, hyperscale cloud providers lead buyers with 83.3%, and server systems (L10) lead integration levels with 51.3%. Custom ASIC servers are the fastest-growing segment at 24.76% a year, ahead of Arm servers at 20.49% and rack-scale systems at 19.42%, because hyperscalers are moving inference onto their own chips and only ODMs build the servers around them.
By Server Type: AI and Accelerated Servers Lead with 74.1%
| Server type | 2025 (USD billion) | Share 2025 | 2035 (USD billion) | CAGR 2025-2035 |
|---|---|---|---|---|
| AI and Accelerated Servers | 138.95 | 74.1% | 640.00 | 16.50% |
| General-Purpose Servers | 40.10 | 21.4% | 85.34 | 7.85% |
| Storage-Dense Servers | 8.40 | 4.5% | 20.48 | 9.32% |
AI and accelerated servers reach 85.8% of white box value by 2035.
By Integration Level: Server Systems (L10) Lead with 51.3%
| Integration level | 2025 (USD billion) | Share 2025 | 2035 (USD billion) | CAGR 2025-2035 |
|---|---|---|---|---|
| Server Systems (L10) | 96.20 | 51.3% | 255.00 | 10.24% |
| Rack-Scale Systems (L11) | 78.35 | 41.8% | 462.00 | 19.42% |
| Motherboards and Sub-Assemblies (L6) | 12.90 | 6.9% | 28.82 | 8.37% |
Rack-scale systems overtake single server systems around 2028 in the DC Market Insights forecast.
By Processor Architecture: x86 Leads with 64.1%
| Host processor | 2025 (USD billion) | Share 2025 | 2035 (USD billion) | CAGR 2025-2035 |
|---|---|---|---|---|
| x86 | 120.15 | 64.1% | 330.00 | 10.63% |
| Arm | 62.80 | 33.5% | 405.00 | 20.49% |
| Other Architectures | 4.50 | 2.4% | 10.82 | 9.17% |
By Accelerator Type: GPUs Lead with 66.6%
Within AI and accelerated white box servers, worth USD 138.95 billion in 2025, GPU servers account for USD 92.60 billion (66.6%) and grow at 10.53% a year to USD 252.00 billion by 2035. Custom ASIC servers account for USD 39.95 billion (28.8%) and grow at 24.76% a year to USD 365.00 billion, overtaking GPU servers around 2032. Servers with FPGAs and other accelerators account for USD 6.40 billion (4.6%) and reach USD 23.00 billion by 2035.
By End-user: Hyperscale Cloud Providers Lead with 83.3%
| End-user | 2025 (USD billion) | Share 2025 | 2035 (USD billion) | CAGR 2025-2035 |
|---|---|---|---|---|
| Hyperscale Cloud Providers | 156.20 | 83.3% | 585.00 | 14.12% |
| GPU and Neocloud Providers | 14.05 | 7.5% | 80.20 | 19.03% |
| Government and Sovereign AI | 7.10 | 3.8% | 38.50 | 18.42% |
| Telecom and Other Service Providers | 6.35 | 3.4% | 24.50 | 14.46% |
| Enterprises | 3.75 | 2.0% | 17.62 | 16.73% |
GPU and neocloud providers grow fastest; enterprises remain the smallest group.
DC Exclusive: The ODM-Direct Units × Price Model and Server Type × Buyer Matrix
At USD 112.30 billion in 2025, hyperscale AI and accelerated servers are the single largest cell of the matrix and 59.9% of all white box server spending. The matrix below cross-tabulates what is bought and who buys it.
| 2025, USD billion | AI and Accelerated | General-Purpose | Storage-Dense | Total |
|---|---|---|---|---|
| Hyperscale Cloud Providers | 112.30 | 36.10 | 7.80 | 156.20 |
| GPU and Neocloud Providers | 13.70 | 0.30 | 0.05 | 14.05 |
| Government and Sovereign AI | 6.25 | 0.70 | 0.15 | 7.10 |
| Telecom and Other Service Providers | 3.80 | 2.30 | 0.25 | 6.35 |
| Enterprises | 2.90 | 0.70 | 0.15 | 3.75 |
| Total | 138.95 | 40.10 | 8.40 | 187.45 |
Hyperscalers spend 71.9% of their white box budget on accelerated systems and still buy 90.0% of all general-purpose white box servers, so a supplier that wins a hyperscaler’s general-purpose design wins most of that segment. Telecom and other service providers spend 36.2% on general-purpose servers for network functions and hosting, the highest share of any buyer group. GPU and neocloud providers are almost entirely accelerated, at 97.5%.
The figures are a DC Market Insights model, not a shipment count. The model is built from 38 inputs: 16 annual ODM-direct shares applied to the server market cohorts, 8 unit and price anchors (2020, 2025, 2030 and 2035 for two server families), 3 server-type splits, 5 buyer splits, 5 regional splits and 1 currency conversion used for the supplier cross-checks. It was checked against the disclosed results of 5 listed ODMs. The model and its assumptions are explained on our research methodology page.
Regional Insights: Which Region Leads the White Box Server Market?
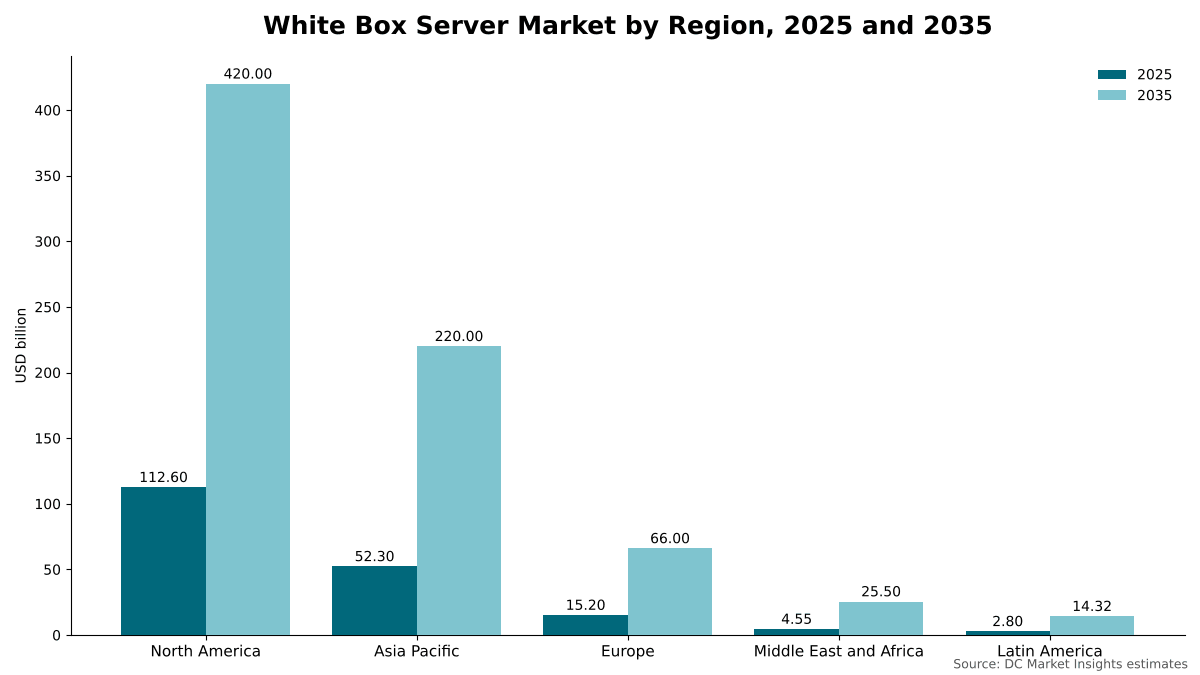
North America leads the White Box Server Market with 60.1% of 2025 value, and the Middle East and Africa is the fastest-growing region at 18.81% a year, because, in the DC Market Insights view, sovereign AI programs in Saudi Arabia and the United Arab Emirates are buying rack-scale systems from a small base.
North America Leads with 60.1% Share
North American buyers spent USD 112.60 billion on white box servers in 2025, and the region is forecast to reach USD 420.00 billion by 2035, a CAGR of 14.07%. Most of the largest cloud operators and AI labs are headquartered there, and BloombergNEF counted 15.9 GW of the more than 23 GW of data center capacity under construction worldwide at the end of September 2025 in the United States. Taiwan, home of Foxconn, Quanta and Wiwynn, exported USD 198.27 billion of goods to the United States in 2025, 30.9% of its total exports, according to Ministry of Finance data, and its exports of information, communication and audio-video products rose 89.5% to USD 251.15 billion. North America’s share falls to 56.3% by 2035 as other regions build their own AI capacity.
Asia Pacific Holds 27.9% Share
Asia Pacific is worth USD 52.30 billion in 2025 and USD 220.00 billion by 2035, a CAGR of 15.45%. China is the largest market in the region, where domestic cloud operators buy from local ODMs and joint-design partners, and Japan, South Korea, India and Australia follow. Asia Pacific gains 1.6 points of share by 2035.
Europe Holds 8.1% Share
Europe is worth USD 15.20 billion in 2025 and USD 66.00 billion by 2035, a CAGR of 15.82%. Hyperscale regions in the United Kingdom, Germany and the Netherlands account for most white box demand, since more European enterprise and colocation capacity runs branded servers.
Middle East and Africa Holds 2.4% Share
The Middle East and Africa is worth USD 4.55 billion in 2025 and USD 25.50 billion by 2035, the fastest growth of any region at 18.81% a year. Saudi Arabia and the United Arab Emirates account for 73.6% of regional value in 2025.
Latin America Holds 1.5% Share
Latin America is worth USD 2.80 billion in 2025 and USD 14.32 billion by 2035, a CAGR of 17.73%, led by hyperscale cloud regions in Brazil, Mexico and Chile.
Country Analysis: Which Countries Buy the Most White Box Servers?
The United States is the largest country market for white box servers at USD 104.10 billion in 2025, 55.5% of global value, followed by China at USD 24.80 billion (13.2%) and Canada at USD 8.50 billion (4.5%). The 12 largest countries account for 88.0% of 2025 spending.
| Rank | Country | Region | 2025 (USD billion) | Share 2025 | 2035 (USD billion) | CAGR 2025-2035 |
|---|---|---|---|---|---|---|
| 1 | United States | North America | 104.10 | 55.5% | 386.00 | 14.00% |
| 2 | China | Asia Pacific | 24.80 | 13.2% | 96.00 | 14.49% |
| 3 | Canada | North America | 8.50 | 4.5% | 34.00 | 14.87% |
| 4 | Japan | Asia Pacific | 6.10 | 3.3% | 22.50 | 13.94% |
| 5 | South Korea | Asia Pacific | 3.55 | 1.9% | 13.80 | 14.54% |
| 6 | United Kingdom | Europe | 3.40 | 1.8% | 14.20 | 15.37% |
| 7 | India | Asia Pacific | 3.20 | 1.7% | 21.00 | 20.70% |
| 8 | Australia | Asia Pacific | 2.95 | 1.6% | 11.60 | 14.67% |
| 9 | Germany | Europe | 2.90 | 1.5% | 12.45 | 15.69% |
| 10 | Netherlands | Europe | 2.10 | 1.1% | 8.10 | 14.45% |
| 11 | United Arab Emirates | Middle East and Africa | 1.70 | 0.9% | 9.40 | 18.65% |
| 12 | Saudi Arabia | Middle East and Africa | 1.65 | 0.9% | 10.20 | 19.98% |
India is the fastest-growing large country market at 20.70% a year, ahead of Saudi Arabia at 19.98%, and moves from seventh place to fifth by 2035 as hyperscale cloud regions there expand. The country figures are a DC Market Insights allocation of the regional totals, weighted by each country’s estimated share of hyperscale capacity and of accelerated server deliveries.
Forecast Scenarios: How Could the 2035 Forecast Change?
The White Box Server Market reaches USD 745.82 billion by 2035 in the base case, with a range of USD 568.40 billion to USD 912.60 billion across the low and high scenarios.
| Scenario | Assumption from 2026 | 2035 (USD billion) | CAGR 2025-2035 |
|---|---|---|---|
| Low | AI white box units 25% below base by 2030; ODM-direct share flat at 2026 level | 568.40 | 11.73% |
| Base | AI white box units reach 2.25 million in 2035; ODM-direct share reaches 56.8% | 745.82 | 14.81% |
| High | AI white box units 15% above base; sovereign and neocloud buyers move faster to ODM-direct | 912.60 | 17.15% |
The low case is what a two-year pause in hyperscale AI spending looks like: backlogs are worked down, accelerator prices fall and branded OEMs hold their share with enterprise and sovereign buyers.
Competitive Insights: Who Leads the White Box Server Market?
- Foxconn (Hon Hai Precision Industry)
- Quanta Computer
- Wiwynn
- Wistron
- Inventec
- Celestica
- MiTAC Computing Technology
- Pegatron
- Sanmina
- Jabil
- Gigabyte Technology
- ASRock Rack
Foxconn, Quanta and Wiwynn together supply about 58% of the White Box Server Market in 2025 (DC Market Insights estimate, based on their disclosed revenue after removing components, GPU modules and servers built for branded OEMs). Wiwynn’s 2025 revenue alone, about USD 29.7 billion at the NT$32 per US dollar rate DC Market Insights uses for conversion, equals 15.8% of the market, and its revenue rose 163.7% in 2025. Foxconn’s 2025 revenue reached NT$8.1 trillion, and its cloud and networking products overtook smart consumer electronics for the first time; in the second quarter of 2025, cloud and networking made up 41% of revenue and AI server sales grew 60%. Quanta’s 2025 sales rose 50.5% to NT$2.124 trillion. Wistron reported USD 70.2 billion of revenue in 2025, with servers at 70% of sales, and assembles NVIDIA AI supercomputers in Texas. Celestica’s Hardware Platform Solutions revenue grew 72% to about USD 1.4 billion in the fourth quarter of 2025, and the company raised its 2026 revenue outlook to USD 17.0 billion (Source: Celestica filing with the US Securities and Exchange Commission). The revenue of the five listed ODMs is larger than the white box market because it also includes GPU baseboards, compute modules and servers that ODMs build for branded OEMs.
Recent Developments
- In April 2025, NVIDIA said it would build AI supercomputers in the United States with Foxconn in Houston and Wistron in Dallas, with mass production expected to ramp within 12 to 15 months (Source: NVIDIA blog post).
- In October 2025, Meta introduced the Open Rack Wide specification for double-wide AI racks at the OCP Global Summit, and AMD showed its Helios rack built to the standard (Source: IEEE ComSoc Technology Blog report).
- In November 2025, OpenAI and Foxconn agreed to co-design multiple generations of AI data center racks, with Foxconn to manufacture data center equipment in the United States and no purchase commitment in the initial agreement (Source: OpenAI announcement).
- In January 2026, Celestica reported 2025 revenue of USD 12.39 billion, up 28%, and raised its 2026 revenue outlook to USD 17.0 billion (Source: Celestica earnings release).
- In August 2026, Foxconn reported second-quarter revenue of NT$2.53 trillion, up 41%, and said its AI rack shipments are expected to more than double in 2026 (Source: I-Connect007 news report).
- In September 2026, Wiwynn said its Socorro, Texas plant, which started mass production in the first quarter of 2026, has a second building due to begin production in the second quarter of 2027 (Source: Taipei Times news report).
We follow these deals, launches and capacity announcements as they happen in our data center industry updates.
Methodology: How We Built the White Box Server Market Model
DC Market Insights built this market bottom-up from 16 annual unit cohorts (2020 to 2035) for two server families, general-purpose (including storage-dense) servers and AI and accelerated servers, each priced with a white box average selling price at first sale: about USD 8,290 and USD 175,890 in 2025, on about 5.85 million and 0.79 million units. The result was reconciled with the ODM-direct share of the DC Market Insights server model, which rises from 31.2% in 2020 to 51.3% in 2025 and 56.8% in 2035. The total was split by 3 server types, 3 integration levels, 3 processor architectures, 3 accelerator types, 5 end-users and 5 regions, and every split sums to its parent total. The result was checked top-down against the disclosed results of 5 listed ODMs (Foxconn, Quanta, Wiwynn, Wistron and Celestica), Inventec’s AI server growth, data center operator capital spending counts from BloombergNEF and Taiwan’s export statistics. Country values allocate each regional total by country weights for hyperscale capacity and accelerated server deliveries. The analyst named on this page built the model, and the reviewer checked the arithmetic, the sources and the dates before publication.
Table of contents
- 01Introduction
- 1.1Market Definition and Scope
- 1.2Inclusions and Exclusions
- 1.3Currency, Pricing and Base Year
- 1.4Key Stakeholders
- 02Research Methodology
- 2.1Units × Price Model
- 2.2ODM-Direct Share Reconciliation
- 2.3Top-Down Validation Against ODM Disclosures
- 2.4Data Sources and Assumptions
- 03Executive Summary
- 3.1Market Snapshot, 2025 and 2035
- 3.2Key Findings
- 3.3Analyst Viewpoint
- 04Market Dynamics
- 4.1Drivers
- 4.2Trends
- 4.3Challenges
- 4.4Opportunities
- 05Pricing Analysis
- 5.1Average Selling Price by Server Family, 2020-2035
- 5.2AI Share of White Box Units
- 5.3White Box Versus Branded Server Pricing
- 06Standards and Regulation
- 6.1OCP Data Center Modular Hardware System (DC-MHS)
- 6.2Open Rack Wide (ORW)
- 6.3EU Regulation 2019/424 Ecodesign Requirements
- 07Supply Chain and Manufacturing Footprint
- 7.1L6, L10 and L11 Integration Levels
- 7.2ODM Manufacturing Locations
- 7.3US Rack-Scale Assembly Capacity
- 08Market Size and Forecast
- 8.1Historical Market Size, 2020-2024
- 8.2Market Size and Forecast, 2025-2035
- 8.3ODM-Direct Share of the Server Market
- 09White Box Server Market, by Server Type
- 9.1AI and Accelerated Servers
- 9.2General-Purpose Servers
- 9.3Storage-Dense Servers
- 10White Box Server Market, by Integration Level
- 10.1Server Systems (L10)
- 10.2Rack-Scale Systems (L11)
- 10.3Motherboards and Sub-Assemblies (L6)
- 11White Box Server Market, by Processor Architecture
- 11.1x86
- 11.2Arm
- 11.3Other Architectures
- 12White Box Server Market, by Accelerator Type
- 12.1GPU
- 12.2Custom ASIC
- 12.3Other Accelerators (FPGA and Others)
- 13White Box Server Market, by End-user
- 13.1Hyperscale Cloud Providers
- 13.2GPU and Neocloud Providers
- 13.3Government and Sovereign AI
- 13.4Telecom and Other Service Providers
- 13.5Enterprises
- 14DC Exclusive: Server Type × Buyer Matrix
- 14.1Matrix Construction and Inputs
- 14.2Key Cross-Section Findings
- 15White Box Server Market, by Region
- 15.1North America (United States, Canada)
- 15.2Asia Pacific (China, Japan, South Korea, India, Australia, Rest of Asia Pacific)
- 15.3Europe (United Kingdom, Germany, Netherlands, Rest of Europe)
- 15.4Middle East and Africa (United Arab Emirates, Saudi Arabia, Rest of Middle East and Africa)
- 15.5Latin America (Brazil, Mexico, Chile, Rest of Latin America)
- 16Country Analysis
- 16.1Top 12 Countries, 2025 and 2035
- 16.2Fastest-Growing Country Markets
- 17Regional Cross-Sections
- 17.1Regional Share Shifts, 2025 and 2035
- 17.2Regional Growth Rates, 2025-2035
- 18Forecast Scenarios
- 18.1Low Scenario
- 18.2Base Scenario
- 18.3High Scenario
- 19Competitive Landscape
- 19.1Market Concentration
- 19.2ODM Positioning by Buyer
- 19.3Recent Developments
- 20Company Profiles
- 20.1Foxconn (Hon Hai Precision Industry)
- 20.2Quanta Computer
- 20.3Wiwynn
- 20.4Wistron
- 20.5Inventec
- 20.6Celestica
- 20.7MiTAC Computing Technology
- 20.8Pegatron
- 20.9Sanmina
- 20.10Jabil
- 20.11Gigabyte Technology
- 20.12ASRock Rack
- 21Analyst Recommendations
- 21.1For ODMs
- 21.2For Hyperscale and Neocloud Buyers
- 21.3For Investors
- Fig. 1White Box Server Market Size, 2020–2035
- Fig. 2White Box Server Market Share by Server Type, 2025 and 2035
- Fig. 3White Box Server Market Share by Integration Level, 2025 and 2035
- Fig. 4White Box Server Market by Processor Architecture, 2025 and 2035
- Fig. 5White Box Server Market by End-user, 2025 and 2035
- Fig. 6White Box Server Market by Region, 2025 and 2035
- Fig. 7Top 12 Countries, 2025
- Fig. 8Forecast Scenarios, 2035
- Table 1Report Attributes
- Table 2Average Selling Price by Server Family, 2020, 2025, 2030 and 2035
- Table 3White Box Server Market by Server Type, 2025 and 2035
- Table 4White Box Server Market by Integration Level, 2025 and 2035
- Table 5White Box Server Market by Processor Architecture, 2025 and 2035
- Table 6AI and Accelerated White Box Servers by Accelerator Type, 2025 and 2035
- Table 7White Box Server Market by End-user, 2025 and 2035
- Table 8Server Type × Buyer Matrix, 2025
- Table 9White Box Server Market by Region, 2025 and 2035
- Table 10Top 12 Countries, 2025 and 2035
- Table 11Forecast Scenarios, 2035
About this report
Written by Amit Jain and reviewed by Deepti Agrawal, Senior Editor, Research. Figures are built top-down and bottom-up and reconciled before publication, with 2025 as the base year.
Read our methodologyHow we built this
- Historical period2020-2024
- Base year2025
- Forecast period2026-2035
- Sizing approachTop-down + bottom-up
Need more than the report?
Advisory on this market
Due diligence, site selection and market entry work, by the analysts who wrote this report.
See consulting servicesFrequently asked questions
USD 187.45 billion in 2025, rising to USD 745.82 billion by 2035. DC Market Insights estimates the market at USD 27.33 billion in 2020.
14.81% a year from 2025 to 2035. Growth was faster, at 46.98% a year, between 2020 and 2025 as hyperscalers took delivery of rack-scale GPU systems and custom accelerator servers.
A server that an original design manufacturer builds to the buyer’s own design or an open specification and sells directly without an OEM brand. White box servers made up 51.3% of data center server value in 2025, according to DC Market Insights estimates.
AI and accelerated servers, with USD 138.95 billion or 74.1% of the market in 2025. Custom ASIC servers are the fastest-growing segment at 24.76% a year.
About USD 8,290 for a general-purpose white box server and about USD 175,890 for an AI or accelerated white box server in 2025, according to DC Market Insights estimates of the average selling price at first sale.
North America, with USD 112.60 billion or 60.1% of 2025 value. The Middle East and Africa grows fastest at 18.81% a year.
Foxconn, Quanta and Wiwynn together supply about 58% of the market in 2025 (DC Market Insights estimate). Wistron, Inventec, Celestica, MiTAC Computing Technology, Pegatron, Sanmina, Jabil, Gigabyte Technology and ASRock Rack also compete.
Hyperscale cloud providers, with USD 156.20 billion or 83.3% of 2025 demand. GPU and neocloud providers grow fastest at 19.03% a year.
Licences, delivery and payment
Which licence should I choose?
Single User is a view-only PDF for one person. Multi User adds a printable PDF and the Excel data for unlimited users at one location. Enterprise covers your whole company and includes 100 free analyst hours.
How and when will I receive the report?
By email, within 24–48 business hours of payment, in the formats of your licence.
How can I pay?
Securely through PayPal: with a PayPal account, a debit or credit card, or PayPal Pay Later where available. Prices are in US dollars.
Can I see a sample first?
Yes. Request a free sample and we will email it to you.
Can the report be tailored to my needs?
Yes. We can add countries, segments or data cuts. Talk to an analyst about the scope you need.
Can I get an invoice or pay against a purchase order?
Write to sales@dcmarketinsights.com and our team will help.