
Multi-Tenant Data Center Market Size, Share & Forecast to 2035
Market at a glance
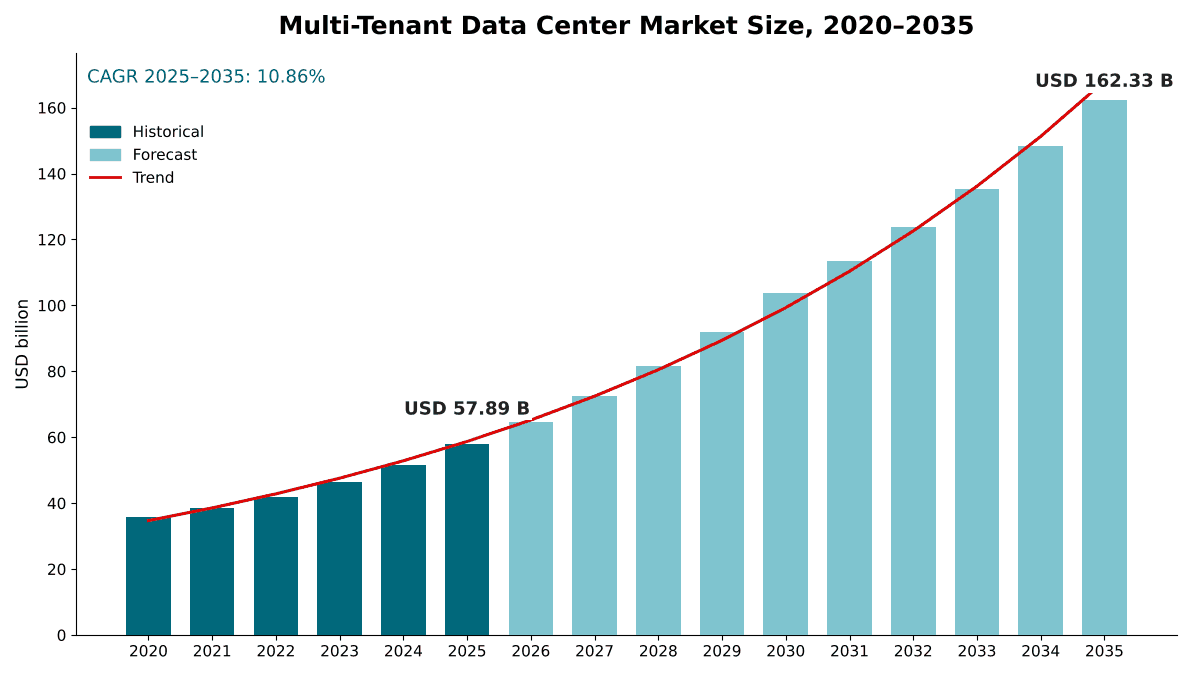
The Multi-Tenant Data Center market was worth USD 57.89 billion in 2025 and is forecast to reach USD 162.33 billion by 2035, growing at a 10.86% CAGR. North America accounts for 47.8% of the market.
 By Priyanka Mor, Senior Consultant
 Reviewed by Deepti Agrawal
Last updated 10 Oct 2026
Base year 2025 PDF + Excel
Source: DC Market Insights analysis
Key findings
Hyperscale Leasing Grows at 16.71% a Year as Tenants Pre-Lease Whole Campuses
Campuses of 1 GW and More Become the Unit of Supply
Grid Queues Run to Tens of Gigawatts
AI and GPU Cloud Providers Grow Revenue Almost Sevenfold by 2035
What is inside the report
- 01Introduction
- 02Research Methodology
- 03Executive Summary
- 04Market Dynamics
- 05Pricing and Rent Analysis
- 06Standards and Regulation
- 07Supply Chain and Value Chain Analysis
- 08Global Multi-Tenant Data Center Market Size and Forecast
- 09Market by Service Type
- 10Market by Tenant Type
- 20chapters
- 2020-2024Historical period
- 2026-2035Forecast period
- 17Companies profiled
Regional insights
- North America47.8%
- Asia Pacific24.1%
- Europe21.2%
- Latin America4.1%
- Middle East and Africa2.8%
Segmentation
Companies profiled
- Equinix
- Digital Realty
- NTT DATA Global Data Centers
- CoreSite (American Tower)
- Iron Mountain Data Centers
- Aligned Data Centers
- Vantage Data Centers
- QTS Data Centers
- CyrusOne
- STACK Infrastructure
- AirTrunk
- Switch
- Cologix
- DataBank
- GDS Holdings
- Princeton Digital Group
- Yondr Group
Recent developments
NTT DATA's NTT DC REIT listed in Singapore in a USD 773 million initial public offering, with six assets of about 90.7 MW of design IT load in Northern Virginia, Northern California, Vienna and Singapore (Source: W.Media news report).
Vantage Data Centers launched Frontier, a USD 25 billion, 1.4 GW hyperscale campus in Shackelford County, Texas (Source: DigitalBridge press release).
a consortium of AIP, MGX and GIP agreed to acquire Aligned Data Centers in a transaction valued at USD 40 billion (Source: W.Media news report).
Equinix reported 2025 revenue of USD 9.22 billion and guided to USD 10.12 billion to USD 10.22 billion for 2026 (Source: Equinix earnings release).
Digital Realty announced the final close of its first US hyperscale data center fund with USD 3.25 billion of equity commitments (Source: Digital Realty press release).
the AIP, MGX and GIP consortium closed its acquisition of Aligned Data Centers, which operates 51 campuses with more than 6.4 GW of operational and planned capacity (Source: Capacity Media news report).
Full analysis
The Multi-Tenant Data Center Market covers the revenue that multi-tenant data center (MTDC) operators, also called colocation providers, earn from leasing space, power and cooling to more than one customer in a shared building or campus: retail colocation, wholesale colocation, single-tenant hyperscale leasing in operator-owned facilities, and the interconnection services sold inside those buildings. DC Market Insights values the global Multi-Tenant Data Center Market at USD 57.89 billion in 2025 and forecasts USD 162.33 billion by 2035, a CAGR of 10.86%. The 2025 value is built from leased capacity times price: about 10.5 GW of hyperscale leases at an average USD 128 per kW per month gives USD 16.13 billion, 6.4 GW of wholesale colocation at USD 158 per kW per month gives USD 12.13 billion, 5.6 GW of retail colocation at USD 385 per kW per month gives USD 25.87 billion, and interconnection adds USD 3.75 billion. AI and GPU cloud providers are the fastest-growing segment at 20.82% a year because they lease whole halls rather than build their own, and the Middle East and Africa is the fastest-growing region at 15.52% a year because DC Market Insights expects Gulf sovereign AI programs to add leased capacity from a small base.
Executive Summary
The Global Multi-Tenant Data Center Market size was valued at USD 35.74 billion in 2020, reached USD 57.89 billion in 2025, and is anticipated to reach USD 162.33 billion by 2035, at a CAGR of 10.86% during the forecast period.
| Report attribute | Details |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Multi-Tenant Data Center Market Size 2025 | USD 57.89 Billion |
| Multi-Tenant Data Center Market, CAGR | 10.86% |
| Multi-Tenant Data Center Market Size 2035 | USD 162.33 Billion |
The market grew at 10.13% a year between 2020 and 2025, and 2025 alone added 12.2% over 2024 as hyperscale cloud providers and AI developers pre-leased capacity instead of waiting for their own campuses. Growth accelerates to 10.86% a year from 2025 to 2035 because leased capacity rises from about 22.5 GW to about 64.5 GW, while average rents keep rising in markets where vacancy sits near zero.
Market Scope: What Does the Multi-Tenant Data Center Market Cover?
The Multi-Tenant Data Center Market covers recurring revenue earned by third-party operators that lease data center capacity to outside customers, valued in current US dollars at the operator level, with 2025 as the base year and forecasts to 2035. DC Market Insights sizes it at USD 57.89 billion in 2025.
Included. Retail colocation (cabinets, cages and suites below 1 MW, usually sold with power, cooling, cross-connects and remote hands), wholesale colocation (dedicated halls of 1 MW to about 10 MW in shared buildings), hyperscale leasing (single-tenant halls, buildings and build-to-suit campuses that an operator owns and leases to a cloud, AI or internet company), and interconnection services sold inside multi-tenant buildings, such as cross-connects, exchange ports and cloud on-ramps.
Excluded. Data centers that hyperscalers or enterprises build and operate for their own use, public cloud and GPU-as-a-service compute revenue, managed hosting and IT outsourcing contracts, construction spending, and land or powered-shell sales without a lease.
How the segments fit together. The service-type split is the build of the model: three capacity pools, each multiplied by its own rent per kW, plus interconnection. The tenant, facility-size, tier and vertical splits re-cut the same USD 57.89 billion by who leases and what they lease. Outsourced operations and managed services are covered in the Data Center Outsourcing Market report.
Market Drivers: What Drives the Multi-Tenant Data Center Market?
Three drivers explain most of the growth in the Multi-Tenant Data Center Market: hyperscale and AI tenants that lease capacity years before it is built, vacancy near zero that lets operators raise rents, and data center power demand that the International Energy Agency (IEA) expects to more than double by 2030.
Hyperscale Leasing Grows at 16.71% a Year as Tenants Pre-Lease Whole Campuses
Most new multi-tenant capacity is committed before it is finished. In CBRE’s North America Data Center Trends H1 2026, commitments covered 80.4% of all capacity under construction in the primary markets, and under-construction capacity rose 24.8% in the half-year to a record 7,481.1 MW. DC Market Insights estimates hyperscale leasing revenue at USD 16.13 billion in 2025 and USD 75.60 billion in 2035, a CAGR of 16.71%, the fastest of the four service types. Digital Realty reported fourth-quarter 2025 bookings of USD 400 million of annualized rental revenue, totaling 159.1 MW at 100% share including joint venture partners. Demand on this scale follows the cloud build-out covered in the Hyperscale Computing Market report.
North American Primary-Market Vacancy at a Record Low of 1.4% Lifts Rents
Primary-market vacancy in North America fell to a record low of 1.4% in the first half of 2026, from 1.6% a year earlier, and average rental rates for 3-to-10-MW deployments rose 8.3% in the half-year, according to CBRE. DC Market Insights models the average rent for wholesale colocation rising from USD 158 per kW per month in 2025 to USD 185 in 2035, and for hyperscale leasing from USD 128 to USD 150.
Data Center Power Demand Doubles by 2030
The IEA estimates that data centers used around 415 terawatt-hours (TWh) of electricity in 2024, about 1.5% of world consumption, and expects consumption to more than double to around 945 TWh by 2030. DC Market Insights models global leased multi-tenant capacity rising from about 22.5 GW in 2025 to about 41.4 GW in 2030 and about 64.5 GW in 2035.
Market Trends: How Is the Multi-Tenant Data Center Business Changing?
The Multi-Tenant Data Center Market is moving toward gigawatt campuses, private capital and AI-ready halls, with deals now measured in tens of billions of dollars.
Campuses of 1 GW and More Become the Unit of Supply
Facilities above 100 MW are worth USD 8.62 billion (14.9%) in 2025 and grow at 19.66% a year, the fastest size class. In August 2025, Vantage Data Centers launched Frontier, a USD 25 billion, 1.4 GW hyperscale campus of 10 data centers and 3.7 million square feet in Shackelford County, Texas.
Private Capital Buys Entire Platforms
Infrastructure investors now buy entire operators. A consortium of the AI Infrastructure Partnership (AIP), MGX and BlackRock’s Global Infrastructure Partners (GIP) agreed in October 2025 to buy Aligned Data Centers in a transaction valued at USD 40 billion and closed the purchase of 100% of the equity in July 2026, when Aligned operated 51 campuses with more than 6.4 GW of operational and planned capacity.
Interconnection Keeps Retail Colocation Profitable
Retail colocation grows slowest among the space products, at 6.51% a year, but interconnection services sold inside retail buildings grow at 8.09% a year to USD 8.16 billion by 2035. Equinix reported more than 500,000 interconnections globally in February 2026. DC Market Insights models interconnection at 14.5% of retail colocation revenue in 2025, rising to 16.8% in 2035 as enterprises connect to more clouds and AI inference platforms from the same cage.
Market Challenges: What Holds the Multi-Tenant Data Center Market Back?
Power availability and the cost and timing of new supply are the two constraints that DC Market Insights expects to cap growth in the Multi-Tenant Data Center Market through 2028.
Grid Queues Run to Tens of Gigawatts
Utilities in the largest hubs face requests far above the capacity they can connect in time. Dominion Energy, which serves Northern Virginia, reported more than 53 GW of data center capacity in various stages of contracting in July 2026, with about 12 GW under electric service agreements. Northern Virginia was the largest market by inventory at 4,496.5 MW in the first half of 2026, according to CBRE.
Construction Cannot Keep Pace with Absorption
Net absorption across North American primary markets was 1,456.2 MW in the first half of 2026, up 11.7% year over year, while total primary-market supply reached a record 10,903 MW. DC Market Insights expects this to keep enterprise tenant growth at 5.60% a year, the slowest of the five tenant groups.
Market Opportunities: Where Are the New Revenue Pools?
The two largest new revenue pools in the Multi-Tenant Data Center Market are AI and GPU cloud providers, growing at 20.82% a year, and fast-growing country markets such as India, growing at 16.31% a year.
AI and GPU Cloud Providers Grow Revenue Almost Sevenfold by 2035
Specialist GPU cloud operators paid multi-tenant operators USD 4.86 billion in 2025, and DC Market Insights expects USD 32.24 billion in 2035. They lease rather than build because speed to power matters more than ownership, and 80% of their 2025 spend in the DC Market Insights matrix went to hyperscale and wholesale halls.
Asia Pacific and the Middle East Add New Hubs
Asia Pacific is worth USD 13.95 billion in 2025 and grows at 12.11% a year, while the Middle East and Africa grows at 15.52%. Singapore’s Infocomm Media Development Authority (IMDA) opened a second Data Centre Call for Application (DC-CFA2) on 1 December 2025 for at least 200 MW of capacity, which adds capacity in a market where new supply is rationed.
Pricing: How Much Does Multi-Tenant Data Center Capacity Cost per kW?
Average 2025 rent across the installed base is about USD 128 per kW per month for hyperscale leases, USD 158 for wholesale colocation and USD 385 for retail colocation, according to DC Market Insights estimates. Asking rents are higher: CBRE reported USD 190 to USD 235 per kW per month in Northern Virginia and USD 235 to USD 265 in Frankfurt in the first quarter of 2026 (CBRE’s 250-to-500-kW benchmark), an average of USD 403 in Singapore and USD 280 in Tokyo.
| Average rent (USD per kW per month) | 2020 | 2025 | 2030 | 2035 |
|---|---|---|---|---|
| Hyperscale Leasing | 118 | 128 | 141 | 150 |
| Wholesale Colocation | 140 | 158 | 174 | 185 |
| Retail Colocation | 345 | 385 | 420 | 450 |
The averages sit below today’s asking rents because most of the installed base was leased years ago at lower rates. For large requirements of 10 MW and more in Northern Virginia, asking rates were roughly USD 160 to USD 185 per kW per month in mid-2026, and São Paulo ranged from USD 130 to USD 190 in the first quarter of 2026.
Standards and Regulation: Which Rules Shape Multi-Tenant Data Centers?
Four sets of rules shape what a multi-tenant operator builds and reports: the TIA-942 infrastructure standard of the Telecommunications Industry Association (TIA), the Uptime Institute Tier Classification System, the EU data center reporting regulation and national capacity allocation schemes.
ANSI/TIA-942-C (May 2024). The TIA-942 standard specifies the requirements for infrastructure of data centers and computer rooms and applies to both single-tenant enterprise and multi-tenant data centers.
Uptime Institute Tiers. The Tier Classification System grades site infrastructure from Tier I to Tier IV, and Uptime Institute reports more than 4,300 Tier Certifications issued in more than 120 countries (as of October 2026). In the DC Market Insights model, Tier III facilities account for 78.7% of 2025 revenue.
EU Delegated Regulation 2024/1364. Commission Delegated Regulation (EU) 2024/1364 of 14 March 2024 requires operators of data centers with an installed IT power demand of at least 500 kW to report energy, water, waste heat and renewable energy indicators, first by 15 September 2024 and then by 15 May each year. Power usage effectiveness (PUE), water usage effectiveness (WUE), the energy reuse factor (ERF) and the renewable energy factor (REF) are calculated from those reports.
Capacity allocation. Some governments ration new capacity. Singapore’s IMDA allocates new data center capacity through calls for application; the second call, launched on 1 December 2025, makes at least 200 MW available.
Market Segmentation: Which Segment Leads the Multi-Tenant Data Center Market?
Retail colocation leads the Multi-Tenant Data Center Market by service type with 44.7% of 2025 revenue, hyperscale cloud providers lead tenants with 41.8%, and Tier III facilities lead with 78.7%. AI and GPU cloud providers are the fastest-growing segment at 20.82% a year, against 11.87% for hyperscale cloud providers and 5.60% for enterprises, because GPU clusters need large blocks of power quickly and these tenants rarely own land or grid connections.
By Service Type: Retail Colocation Leads with 44.7%
| Service type | 2025 (USD billion) | Share 2025 | 2035 (USD billion) | CAGR 2025-2035 |
|---|---|---|---|---|
| Retail Colocation | 25.87 | 44.7% | 48.60 | 6.51% |
| Hyperscale Leasing | 16.13 | 27.9% | 75.60 | 16.71% |
| Wholesale Colocation | 12.13 | 21.0% | 29.97 | 9.46% |
| Interconnection Services | 3.75 | 6.5% | 8.16 | 8.09% |
Hyperscale leasing overtakes retail colocation before 2030 and reaches 46.6% of the market by 2035, because leased hyperscale capacity grows four times, from about 10.5 GW to about 42.0 GW.
By Tenant Type: Hyperscale Cloud Providers Lead with 41.8%
| Tenant type | 2025 (USD billion) | Share 2025 | 2035 (USD billion) | CAGR 2025-2035 |
|---|---|---|---|---|
| Hyperscale Cloud Providers | 24.20 | 41.8% | 74.26 | 11.87% |
| Enterprises | 16.61 | 28.7% | 28.64 | 5.60% |
| Network and Content Providers | 7.58 | 13.1% | 16.05 | 7.79% |
| AI and GPU Cloud Providers | 4.86 | 8.4% | 32.24 | 20.82% |
| Government and Public Sector | 4.63 | 8.0% | 11.14 | 9.18% |
Hyperscale cloud providers pay USD 24.20 billion in 2025. Network and content providers, including carriers, content delivery networks and internet exchanges, pay USD 7.58 billion and buy the highest share of interconnection. Government and public sector tenants pay USD 4.63 billion and grow at 9.18% a year, which DC Market Insights attributes to sovereign cloud programs.
By Facility Size: The 5 to 20 MW Class Leads with 31.8%
| Facility size (IT capacity) | 2025 (USD billion) | Share 2025 | 2035 (USD billion) | CAGR 2025-2035 |
|---|---|---|---|---|
| 5 to 20 MW | 18.41 | 31.8% | 36.13 | 6.98% |
| 20 to 100 MW | 17.19 | 29.7% | 53.73 | 12.07% |
| Below 5 MW | 13.66 | 23.6% | 20.57 | 4.18% |
| Above 100 MW | 8.62 | 14.9% | 51.91 | 19.66% |
Facilities of 5 to 20 MW are the classic multi-tenant building and still lead in 2025. Facilities above 100 MW grow fastest at 19.66% a year and reach 32.0% of revenue by 2035.
By Tier Level: Tier III Leads with 78.7%
Tier III facilities earn USD 45.56 billion in 2025 and USD 129.56 billion by 2035. Tier IV facilities earn USD 8.39 billion (14.5%) and grow at 12.92% a year. Tier I and II facilities earn USD 3.94 billion (6.8%) and grow only 1.31% a year as older buildings are upgraded or retired.
By Vertical: IT and Telecom Lead with 45.2%
IT and telecom companies account for USD 26.16 billion (45.2%) of 2025 revenue and grow at 12.33% a year, since cloud, AI and network operators sit in this vertical. Banking, financial services and insurance (BFSI) follows with USD 9.44 billion (16.3%), then retail and e-commerce with 9.4%, government with 7.7%, media and entertainment with 7.4%, healthcare with 6.2% and others with 7.8%. Healthcare grows fastest outside IT and telecom at 11.53% a year, in the DC Market Insights model, as clinical AI workloads move into leased halls.
DC Exclusive: The Leased Capacity × Rent Model and Tenant × Service Matrix
At 13.86 billion US dollars in 2025, hyperscale cloud leases are the single largest cell of the matrix and 23.9% of all multi-tenant data center revenue, followed closely by enterprise retail colocation at USD 13.42 billion. The matrix cross-tabulates who leases and what they lease. It is a DC Market Insights model, not a survey, built from 59 inputs: 16 capacity anchors for the 3 leased capacity pools, 14 rent anchors, 4 interconnection ratios, 5 tenant splits, 5 regional splits, 12 country weights and 3 operator disclosures used as a cross-check.
| 2025, USD billion | Hyperscale Leasing | Wholesale Colocation | Retail Colocation | Interconnection Services | Total |
|---|---|---|---|---|---|
| Hyperscale Cloud Providers | 13.86 | 6.44 | 3.22 | 0.68 | 24.20 |
| Enterprises | 0.00 | 1.90 | 13.42 | 1.29 | 16.61 |
| Network and Content Providers | 0.10 | 0.89 | 5.15 | 1.44 | 7.58 |
| AI and GPU Cloud Providers | 2.01 | 1.90 | 0.86 | 0.09 | 4.86 |
| Government and Public Sector | 0.16 | 1.00 | 3.22 | 0.25 | 4.63 |
| Total | 16.13 | 12.13 | 25.87 | 3.75 | 57.89 |
Hyperscale cloud providers put 57% of their spend into hyperscale leases, while enterprises put 81% into retail colocation; an operator that sells only retail space is selling mostly to the slowest-growing tenant. Network and content providers spend 19% of their budget on interconnection, the highest share of any tenant.
The leased capacity × rent model behind these figures has two inputs that any reader can check: leased IT capacity in each pool (about 22.5 GW in total in 2025) and the average monthly rent per kW. Multiplying the two, and adding interconnection, gives the market. The model and its assumptions are explained on our research methodology page.
Regional Insights: Which Region Leads the Multi-Tenant Data Center Market?
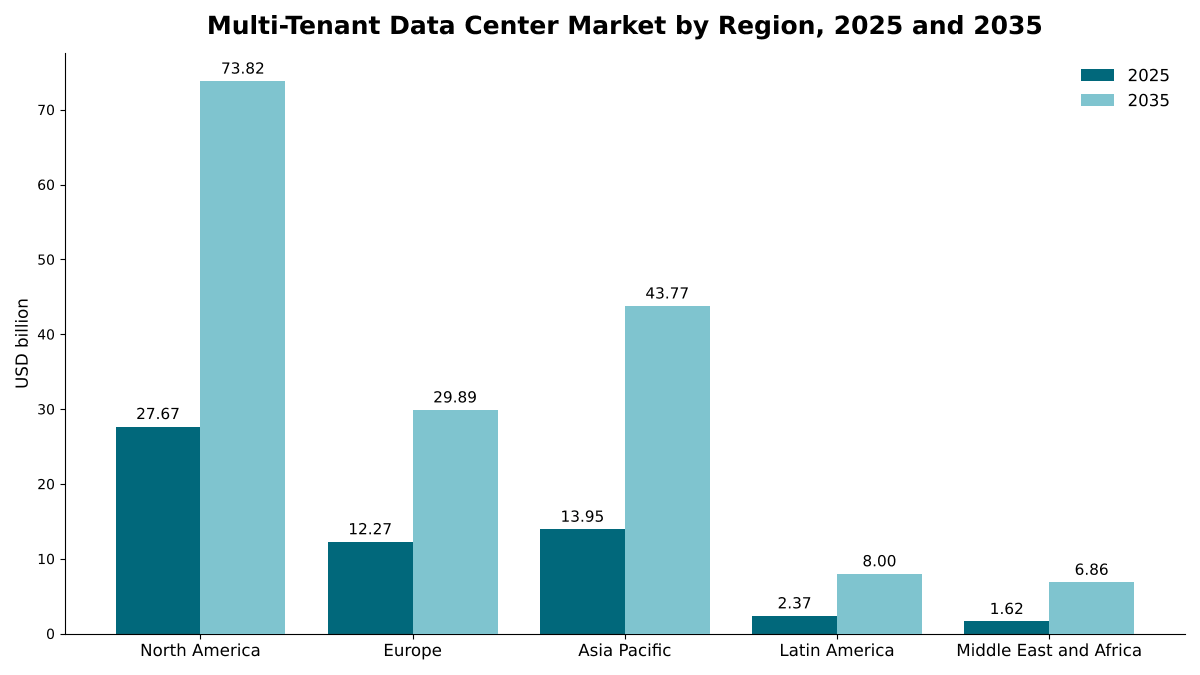
North America leads the Multi-Tenant Data Center Market with 47.8% of 2025 revenue, and the Middle East and Africa is the fastest-growing region at 15.52% a year, because DC Market Insights expects Gulf sovereign AI programs to add leased capacity from a small base.
North America Leads with 47.8% Share
North American operators earned USD 27.67 billion in 2025, and the region is forecast to reach USD 73.82 billion in 2035, a CAGR of 10.31%. Primary-market supply reached a record 10,903 MW in the first half of 2026, up 33.7% year over year, and Northern Virginia remains the largest market by inventory. Atlanta alone had 2,882 MW under construction in the first half of 2026.
Asia Pacific Holds 24.1% Share
Asia Pacific is worth USD 13.95 billion in 2025 and USD 43.77 billion by 2035, a CAGR of 12.11%. CBRE put Asia-Pacific vacancy at 7% in the first quarter of 2026, and net absorption in the four major Asia-Pacific markets reached 608.9 MW. China, Japan, India, Australia and Singapore are the largest country markets in the DC Market Insights allocation.
Europe Holds 21.2% Share
Europe is worth USD 12.27 billion in 2025 and USD 29.89 billion by 2035, a CAGR of 9.31%. Net absorption in Europe’s four largest markets, London, Frankfurt, Paris and Amsterdam, reached 572.1 MW in the first quarter of 2026, up 90% year over year, with overall European vacancy at 7.3%.
Latin America Holds 4.1% Share
Latin America is worth USD 2.37 billion in 2025 and USD 8.00 billion by 2035, a CAGR of 12.92%. Inventory in the four largest markets, São Paulo, Querétaro, Santiago and Bogotá, rose 41.3% year over year to 1,045.0 MW in the first quarter of 2026.
Middle East and Africa Holds 2.8% Share
The Middle East and Africa is worth USD 1.62 billion in 2025 and USD 6.86 billion by 2035, growing fastest at 15.52% a year. DC Market Insights expects Saudi Arabia and the United Arab Emirates to drive most of the growth. Investors weighing new markets can read how we assess power, fiber routes and permitting in our data center site selection and feasibility work.
Country Analysis: Which Countries Lead Multi-Tenant Data Center Revenue?
The United States is the largest country market for multi-tenant data centers at USD 25.04 billion in 2025, 43.3% of global revenue, followed by China at USD 4.81 billion (8.3%) and Canada at USD 2.63 billion (4.5%). The 12 largest countries account for 81.6% of 2025 revenue.
| Rank | Country | Region | 2025 (USD billion) | Share 2025 | 2035 (USD billion) | CAGR 2025-2035 |
|---|---|---|---|---|---|---|
| 1 | United States | North America | 25.04 | 43.3% | 66.01 | 10.18% |
| 2 | China | Asia Pacific | 4.81 | 8.3% | 14.06 | 11.31% |
| 3 | Canada | North America | 2.63 | 4.5% | 7.81 | 11.51% |
| 4 | United Kingdom | Europe | 2.63 | 4.5% | 6.05 | 8.71% |
| 5 | Germany | Europe | 2.41 | 4.2% | 5.97 | 9.51% |
| 6 | Japan | Asia Pacific | 2.34 | 4.0% | 6.66 | 11.01% |
| 7 | India | Asia Pacific | 1.37 | 2.4% | 6.20 | 16.31% |
| 8 | France | Europe | 1.29 | 2.2% | 3.31 | 9.91% |
| 9 | Australia | Asia Pacific | 1.28 | 2.2% | 4.17 | 12.51% |
| 10 | Netherlands | Europe | 1.20 | 2.1% | 2.60 | 8.01% |
| 11 | Singapore | Asia Pacific | 1.19 | 2.0% | 3.14 | 10.21% |
| 12 | Brazil | Latin America | 1.07 | 1.9% | 3.71 | 13.22% |
India is the fastest-growing large country market at 16.31% a year, ahead of Brazil at 13.22% and Australia at 12.51%, as cloud and AI capacity expands from a small base. Singapore grows slower than the region, at 10.21% a year, because new capacity is rationed. The country figures are a DC Market Insights allocation of the regional totals, weighted by each country’s estimated share of leased and new multi-tenant capacity.
Forecast Scenarios: How Could the 2035 Forecast Change?
The Multi-Tenant Data Center Market reaches USD 162.33 billion by 2035 in the base case, with a range of USD 135.55 billion to USD 187.01 billion across the low and high scenarios.
| Scenario | Assumption from 2026 | 2035 (USD billion) | CAGR 2025-2035 |
|---|---|---|---|
| Low | Leased capacity 12% below base by 2035; rents flat in real terms after 2028 | 135.55 | 8.88% |
| Base | Leased capacity reaches about 64.5 GW; rents rise 1% to 2% a year | 162.33 | 10.86% |
| High | Leased capacity 10% above base; hyperscalers lease a larger share of new AI capacity | 187.01 | 12.44% |
The low case is what a two-year pause in AI capital spending looks like: hyperscalers slow pre-leasing, new campuses open with vacancy and rents stall. The high case assumes grid connections arrive on time and hyperscalers lease a larger share of their AI capacity. Self-build versus lease is the main swing factor.
Competitive Insights: Who Leads the Multi-Tenant Data Center Market?
- Equinix
- Digital Realty
- NTT DATA Global Data Centers
- CoreSite (American Tower)
- Iron Mountain Data Centers
- Aligned Data Centers
- Vantage Data Centers
- QTS Data Centers
- CyrusOne
- STACK Infrastructure
- AirTrunk
- Switch
- Cologix
- DataBank
- GDS Holdings
- Princeton Digital Group
- Yondr Group
Equinix is the market leader with about 16% of the Multi-Tenant Data Center Market in 2025, and three large US-listed operators, Equinix, Digital Realty and American Tower’s CoreSite data center business, together hold about 28% (DC Market Insights estimate: their reported 2025 revenues of USD 9.22 billion, USD 6.11 billion and USD 1.05 billion set against the USD 57.89 billion market). Equinix runs 280 data centers in 77 markets in 36 countries for more than 10,500 customers, according to its annual report filed with the US Securities and Exchange Commission, and delivered record capacity in 2025, including 23,250 retail cabinets and more than 90 MW of xScale capacity. It expects 2026 revenue of USD 10.12 billion to USD 10.22 billion. Digital Realty operates more than 300 facilities in more than 55 metros across more than 30 countries. NTT DATA, Aligned, Vantage, QTS, CyrusOne, STACK and AirTrunk compete for hyperscale and AI leases, while Cologix, DataBank and Switch focus on enterprise and network tenants.
Recent Developments
- In July 2025, NTT DATA’s NTT DC REIT listed in Singapore in a USD 773 million initial public offering, with six assets of about 90.7 MW of design IT load in Northern Virginia, Northern California, Vienna and Singapore (Source: W.Media news report).
- In August 2025, Vantage Data Centers launched Frontier, a USD 25 billion, 1.4 GW hyperscale campus in Shackelford County, Texas (Source: DigitalBridge press release).
- In October 2025, a consortium of AIP, MGX and GIP agreed to acquire Aligned Data Centers in a transaction valued at USD 40 billion (Source: W.Media news report).
- In February 2026, Equinix reported 2025 revenue of USD 9.22 billion and guided to USD 10.12 billion to USD 10.22 billion for 2026 (Source: Equinix earnings release).
- In March 2026, Digital Realty announced the final close of its first US hyperscale data center fund with USD 3.25 billion of equity commitments (Source: Digital Realty press release).
- In July 2026, the AIP, MGX and GIP consortium closed its acquisition of Aligned Data Centers, which operates 51 campuses with more than 6.4 GW of operational and planned capacity (Source: Capacity Media news report).
We follow these deals, launches and capacity announcements as they happen in our data center industry updates.
Methodology: How We Built the Multi-Tenant Data Center Market Model
DC Market Insights built this market bottom-up from three leased capacity pools, hyperscale leasing, wholesale colocation and retail colocation, each with 16 annual values from 2020 to 2035 and its own average rent per kW per month. Interconnection was added as a share of retail colocation revenue, rising from 13.0% in 2020 to 16.8% in 2035. The total was split by 4 service types, 5 tenant types, 4 facility sizes, 3 tier levels, 7 verticals and 5 regions, and every split sums to the market total. The result was checked against three bounds. First, top-down: the reported 2025 revenues of Equinix, Digital Realty and American Tower’s data center segment (CoreSite) add up to USD 16.38 billion, about 28% of the modeled market, a plausible share for three of the largest operators. Second, a capacity ceiling: about 22.5 GW of leased IT capacity would draw at most about 31.5 GW at full load and a PUE of 1.4, below the roughly 47 GW of average load implied by the IEA’s 415 TWh of data center electricity use in 2024. Third, a North American cross-check: CBRE’s primary-market supply of 10,903 MW in mid-2026, up 33.7% year over year, implies about 8.16 GW a year earlier, and DC Market Insights estimates North American leased capacity, including secondary markets, at about 10.4 GW on average in 2025, between the two primary-market readings plus a secondary-market allowance. The analyst named on this page built the model, and the reviewer checked the arithmetic, the sources and the dates before publication.
Table of contents
- 01Introduction
- 1.1Market Definition and Scope
- 1.2Service Types, Tenants and Regions Covered
- 1.3Currency, Base Year and Forecast Period
- 1.4Key Questions Answered
- 02Research Methodology
- 2.1Leased Capacity × Rent Model
- 2.2Capacity Pools: Hyperscale, Wholesale and Retail
- 2.3Interconnection Revenue Model
- 2.4Top-Down Check Against Operator Disclosures
- 2.5Capacity and Power Bound Checks
- 2.6Assumptions and Limitations
- 03Executive Summary
- 3.1Market at a Glance, 2020-2035
- 3.2Key Findings
- 3.3Analyst Recommendations by Tenant Type
- 04Market Dynamics
- 4.1Drivers
- 4.2Challenges and Restraints
- 4.3Opportunities
- 4.4Trends
- 4.5Impact Analysis of Drivers and Challenges, 2025-2035
- 05Pricing and Rent Analysis
- 5.1Average Rent per kW: Hyperscale, Wholesale and Retail, 2020-2035
- 5.2Asking Rents in Major Markets, 2026
- 5.3Interconnection Pricing and Share of Retail Revenue
- 06Standards and Regulation
- 6.1ANSI/TIA-942-C
- 6.2Uptime Institute Tier Classification
- 6.3EU Delegated Regulation 2024/1364
- 6.4National Capacity Allocation Schemes
- 07Supply Chain and Value Chain Analysis
- 7.1Land, Power and Grid Connections
- 7.2Development and Construction
- 7.3Operators, Funds and REITs
- 7.4Tenants and Interconnection Ecosystems
- 08Global Multi-Tenant Data Center Market Size and Forecast
- 8.1Market Size, 2020-2024
- 8.2Market Size, 2025
- 8.3Market Forecast, 2026-2035
- 8.4Leased Capacity, 2020-2035
- 09Market by Service Type
- 9.1Retail Colocation
- 9.2Wholesale Colocation
- 9.3Hyperscale Leasing
- 9.4Interconnection Services
- 10Market by Tenant Type
- 10.1Hyperscale Cloud Providers
- 10.2Enterprises
- 10.3Network and Content Providers
- 10.4AI and GPU Cloud Providers
- 10.5Government and Public Sector
- 11Market by Facility Size
- 11.1Below 5 MW
- 11.25 to 20 MW
- 11.320 to 100 MW
- 11.4Above 100 MW
- 12Market by Tier Level
- 12.1Tier I and II
- 12.2Tier III
- 12.3Tier IV
- 13Market by Vertical
- 13.1IT and Telecom
- 13.2BFSI
- 13.3Retail and E-commerce
- 13.4Government
- 13.5Media and Entertainment
- 13.6Healthcare
- 13.7Others
- 14DC Exclusive: Tenant × Service Type Matrix
- 14.1Tenant × Service Type Matrix, 2025
- 14.2Spend Mix by Tenant, 2025
- 14.3Implications for Operators
- 15Market by Region
- 15.1North America (United States, Canada)
- 15.2Europe (United Kingdom, Germany, France, Netherlands, Rest of Europe)
- 15.3Asia Pacific (China, Japan, India, Australia, Singapore, Rest of Asia Pacific)
- 15.4Latin America (Brazil, Rest of Latin America)
- 15.5Middle East and Africa
- 15.6Top 12 Countries, 2025 and 2035
- 16Regional Cross-Sections
- 16.1Region Share and Growth, 2025 and 2035
- 16.2Country Share Within Each Region, 2025 and 2035
- 17Forecast Scenarios
- 17.1Base, Low and High Cases to 2035
- 17.2Sensitivity to Leased Capacity
- 17.3Sensitivity to Rents
- 17.4Self-Build Versus Lease
- 18Competitive Landscape
- 18.1Market Share of Leading Operators, 2025
- 18.2Top-Three Concentration
- 18.3Mergers, Acquisitions and Capital Raises, 2025-2026
- 18.4New Campus Launches
- 19Company Profiles
- 19.1Equinix
- 19.2Digital Realty
- 19.3NTT DATA Global Data Centers
- 19.4CoreSite (American Tower)
- 19.5Iron Mountain Data Centers
- 19.6Aligned Data Centers
- 19.7Vantage Data Centers
- 19.8QTS Data Centers
- 19.9CyrusOne
- 19.10STACK Infrastructure
- 19.11AirTrunk
- 19.12Switch
- 19.13Cologix
- 19.14DataBank
- 19.15GDS Holdings
- 19.16Princeton Digital Group
- 19.17Yondr Group
- 20Analyst Recommendations
- 20.1For Multi-Tenant Operators
- 20.2For Hyperscale, AI and Enterprise Tenants
- 20.3For Investors
- Fig. 1Multi-Tenant Data Center Market Size, 2020-2035
- Fig. 2Leased Capacity by Pool, 2020-2035
- Fig. 3Average Rent per kW by Service Type, 2020-2035
- Fig. 4Market Share by Service Type, 2025 and 2035
- Fig. 5Market Share by Tenant Type, 2025 and 2035
- Fig. 6Market by Facility Size, 2025 and 2035
- Fig. 7Tenant × Service Type Matrix, 2025
- Fig. 8Market by Region, 2025 and 2035
- Fig. 9Top 12 Countries, 2025
- Fig. 10Forecast Scenarios, 2025-2035
- Fig. 11Top-Three Operator Concentration, 2025
- Table 1Report Attributes
- Table 2Average Rent per kW, 2020-2035
- Table 3Market by Service Type, 2025 and 2035
- Table 4Market by Tenant Type, 2025 and 2035
- Table 5Market by Facility Size, 2025 and 2035
- Table 6Market by Tier Level, 2025 and 2035
- Table 7Market by Vertical, 2025 and 2035
- Table 8Tenant × Service Type Matrix, 2025
- Table 9Market by Region, 2025 and 2035
- Table 10Top 12 Countries, 2025 and 2035
- Table 11Forecast Scenarios, 2035
- Table 12Mergers, Acquisitions and Capital Raises, 2025-2026
- Table 13Company Profiles: Portfolio and Tenant Focus
About this report
Written by Priyanka Mor and reviewed by Deepti Agrawal, Senior Editor, Research. Figures are built top-down and bottom-up and reconciled before publication, with 2025 as the base year.
Read our methodologyHow we built this
- Historical period2020-2024
- Base year2025
- Forecast period2026-2035
- Sizing approachTop-down + bottom-up
Need more than the report?
Advisory on this market
Due diligence, site selection and market entry work, by the analysts who wrote this report.
See consulting servicesFrequently asked questions
USD 57.89 billion in 2025, rising to USD 162.33 billion by 2035. DC Market Insights estimates the market at USD 35.74 billion in 2020.
10.86% a year from 2025 to 2035, up from 10.13% a year between 2020 and 2025, as hyperscale and AI tenants lease whole campuses.
Retail colocation, with USD 25.87 billion or 44.7% of 2025 revenue. Hyperscale leasing grows fastest at 16.71% a year and overtakes retail colocation before 2030.
About USD 128 per kW per month for hyperscale leases, USD 158 for wholesale colocation and USD 385 for retail colocation on average in 2025, according to DC Market Insights estimates.
North America, with USD 27.67 billion or 47.8% of 2025 revenue. The Middle East and Africa grows fastest at 15.52% a year.
Equinix leads with about 16% of the market, and Equinix, Digital Realty and CoreSite (American Tower) together hold about 28% (DC Market Insights estimate). NTT DATA, Iron Mountain, Aligned, Vantage, QTS, CyrusOne, STACK, AirTrunk and others also compete.
AI and GPU cloud providers, at 20.82% a year from USD 4.86 billion in 2025. Hyperscale cloud providers are the largest tenant group with 41.8% of revenue.
The United States, with USD 25.04 billion or 43.3% of 2025 revenue. India grows fastest among large country markets at 16.31% a year (DC Market Insights estimate).
Licences, delivery and payment
Which licence should I choose?
Single User is a view-only PDF for one person. Multi User adds a printable PDF and the Excel data for unlimited users at one location. Enterprise covers your whole company and includes 100 free analyst hours.
How and when will I receive the report?
By email, within 24–48 business hours of payment, in the formats of your licence.
How can I pay?
Securely through PayPal: with a PayPal account, a debit or credit card, or PayPal Pay Later where available. Prices are in US dollars.
Can I see a sample first?
Yes. Request a free sample and we will email it to you.
Can the report be tailored to my needs?
Yes. We can add countries, segments or data cuts. Talk to an analyst about the scope you need.
Can I get an invoice or pay against a purchase order?
Write to sales@dcmarketinsights.com and our team will help.