
Data Center Construction Materials Supply Chain Market Size, Share & Forecast to 2035
Market at a glance
The Data Center Construction Materials Supply Chain market was worth USD 10.62 billion in 2025 and is forecast to reach USD 24.33 billion by 2035, growing at a 8.64% CAGR.
 By Amit Jain, Senior Consultant, ICT & Emerging Technologies
 Reviewed by Deepti Agrawal
Last updated 5 Nov 2026
Base year 2025 PDF + Excel
Key findings
US Data Center Construction Hit a USD 96.46 Billion Annual Rate in September 2026
Microsoft and Meta Put Cross-Laminated Timber Into Data Center Shells
Steel Price Swings of 107% Since 2020 Make Fixed-Price Shell Contracts Risky
Prefabricated and Modular Structures Reach USD 5.59 billion by 2035
What is inside the report
- 01Introduction
- 02Executive Summary
- 03Market Scope
- 04Market Dynamics
- 05Pricing Analysis
- 06Standards and Regulation
- 07Market Segmentation by Material Type
- 08Market Segmentation by Construction Method
- 09Market Segmentation by Facility Type
- 10Market Segmentation by Procurement Model
- 17chapters
- 2020-2024Historical period
- 2026-2035Forecast period
- 16Companies profiled
Segmentation
Companies profiled
- Kingspan Group
- Nucor Corporation
- Amrize
- CRH
- Saint-Gobain
- Steel Dynamics
- Commercial Metals Company
- ArcelorMittal
- Stegra
- Martin Marietta Materials
- Vulcan Materials
- Heidelberg Materials
- Owens Corning
- Clark Pacific
- Tindall Corporation
- Orion Group Holdings
Recent developments
Martin Marietta reported record third-quarter aggregates shipments of 67.1 million tons and expected continued strength in data centers (Source: Martin Marietta).
Amrize reported commercial roofing volumes led by large-scale data centers (Source: Amrize).
Commercial Metals Company reported downstream backlog volumes up 15.5% year on year, with data center-related activity supporting merchant bar demand (Source: CMC).
Google agreed to buy green steel certificates for up to 91,000 tonnes from Stegra (Source: Google).
Saint-Gobain reported 1,085 data center projects under specification in 32 countries (Source: Saint-Gobain).
Proclamation 11032 added steel racks to the Section 232 derivative list and cut the American-metal threshold to 85% (Source: Federal Register).
Full analysis
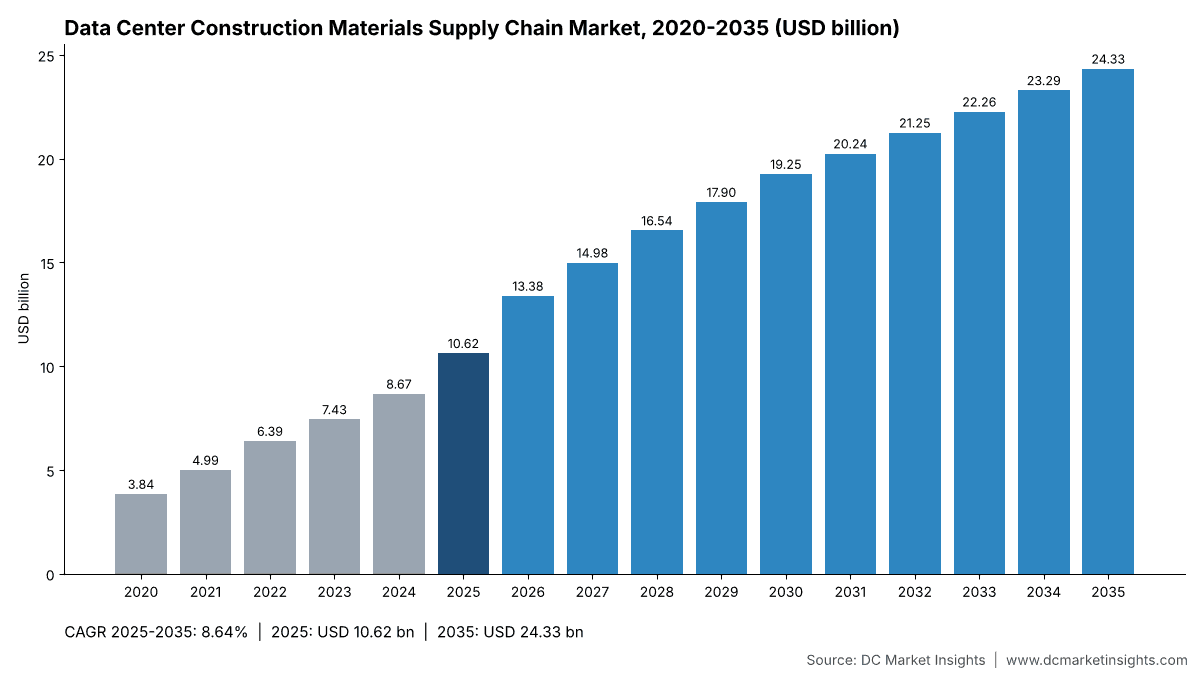
The Data Center Construction Materials Supply Chain Market is valued at USD 13.38 billion in 2026 and is projected to reach USD 24.33 billion by 2035, up from USD 10.62 billion in 2025, a CAGR of 8.64% from 2025 to 2035 (DC Market Insights estimate). What moves the money here is a metals price shock landing on a record build: US Census Bureau data show private data center construction put in place rising from USD 34.80 billion in 2024 to USD 49.74 billion in 2025 and to a seasonally adjusted annual rate of USD 96.46 billion in September 2026, while the Section 232 steel tariff went to 50% in June 2025 and, from 6 April 2026, to the full customs value of derivative products. The producer price index for steel mill products climbed 24% between December 2025 and September 2026, so every tonne of frame, deck and rebar in a new hall now costs more than it did when the campus was budgeted.
The market covers the shell, structure, envelope and site materials delivered to data center construction sites: structural steel and metal deck, ready-mix concrete and reinforcing steel, precast concrete, insulated metal panels and roofing, fire-rated gypsum and insulation, and aggregates, piles and site civil materials. The 2025 receipt is 12,000 megawatts (MW) of new IT capacity × USD 849,500 of shell-and-core materials per MW = USD 10.19 billion, plus USD 427.20 million of materials for expansions and rebuilds inside the 116,000 MW installed base. Mass Timber Hybrid structures grow fastest at 19.07% a year because Microsoft and Meta are piloting cross-laminated timber to cut embodied carbon, and Middle East and Africa is the fastest region at 13.87% as Gulf campuses move from plans to poured slabs.
Key Market Statistics: How Big Is the Data Center Construction Materials Supply Chain Market in 2026?
The Data Center Construction Materials Supply Chain Market reaches USD 13.38 billion in 2026, 26.01% above the USD 10.62 billion of 2025, as new IT capacity rises from 12,000 MW to 15,000 MW and tariff-driven steel prices lift the cost of each frame (DC Market Insights estimate).
- Market size 2025: USD 10.62 billion
- Market size 2026: USD 13.38 billion
- Market size 2030: USD 19.25 billion
- Market size 2035: USD 24.33 billion
- CAGR 2025-2035: 8.64% (low case 6.26%, high case 10.83%)
- Largest material type: Structural Steel and Metal Deck, 22.60% of 2025 value
- Fastest segment: Mass Timber Hybrid structures, 19.07% a year
- Leading region: North America, 45.00% of 2025 value; fastest region: Middle East and Africa, 13.87%
- Largest country: United States, USD 4.35 billion in 2025
- Materials per new MW: USD 849,500 in 2025 (DC Market Insights estimate)
- Largest named data-sector supplier: Kingspan, whose Advnsys data infrastructure division turned over EUR 1,654.9 million in 2025 (Kingspan Annual Report 2025)
Key Takeaways: Why Are Data Center Shells Getting More Expensive per Megawatt?
- Structural Steel and Metal Deck leads with 22.60% of 2025 value, because a frame of about 60 tonnes per MW is bought at roughly USD 3,200 per tonne fabricated and delivered.
- Materials per new MW rise from USD 849,500 in 2025 to about USD 859,900 in 2026, because tariff-driven steel prices outrun the savings from denser artificial intelligence (AI) halls.
- Owner-Direct Framework Agreements grow 13.47% a year, because hyperscalers now buy steel, concrete mixes and panels themselves to lock in supply and embodied-carbon limits.
- Precast Concrete Components grow 10.39% a year, faster than cast-in-place concrete, because precast and prefabricated systems cut site time on campuses that must energise in under two years.
Executive Summary: What Is the Data Center Construction Materials Supply Chain Market Worth?
The Global Data Center Construction Materials Supply Chain Market size was valued at USD 3.84 billion in 2020, reached USD 10.62 billion in 2025, and is anticipated to reach USD 24.33 billion by 2035, at a CAGR of 8.64% during the forecast period (DC Market Insights estimate).
| Attribute | Detail |
|---|---|
| Historical period | 2020-2024 |
| Base year | 2025 |
| Forecast period | 2026-2035 |
| Market size 2025 | USD 10.62 billion |
| Market size 2026 | USD 13.38 billion |
| CAGR 2025-2035 | 8.64% |
| Market size 2035 | USD 24.33 billion |
| Unit | USD million |
The Data Center Construction Materials Supply Chain Market grew 22.57% a year from 2020 to 2025 as new IT capacity rose from 5,000 MW to 12,000 MW and steel prices doubled; growth slows to 8.64% a year to 2035 because new capacity flattens near 27,000 MW a year and AI halls pack more megawatts into each square foot of building. Average materials per new MW stay in a narrow band of USD 836,100 to USD 859,900 from 2026 to 2035, so capacity sets the volume and metals prices set the swing.
What Materials Does the Data Center Construction Materials Supply Chain Market Include?
The Data Center Construction Materials Supply Chain Market counts USD 10.62 billion of 2025 purchases of shell, structure, envelope and site materials at delivered price to the site, including fabrication of steel and casting of precast, but not installation labour.
Included
- Structural steel, joists and metal deck for data halls, mechanical yards and office blocks
- Ready-mix concrete and reinforcing steel for foundations, slabs and walls
- Precast concrete wall, floor and beam elements and tilt-up panels
- Insulated metal wall panels, roofing membranes and roof systems
- Fire-rated gypsum board, insulation and fire-stopping materials
- Aggregates, foundation piles, paving and stormwater materials for data center sites
Excluded
- Copper cable, busbar and other electrical materials, sized in the Data Center Copper Electrical Materials Market
- Mechanical and electrical equipment (generators, switchgear, chillers, uninterruptible power supply systems)
- Raised floors, containment and racks
- Installation labour, design fees and land
How the segments fit together
Every segment table splits the same total: six material types, four construction methods, three facility types and three procurement models each sum to USD 10.62 billion in 2025, and the five regions and the country rows reconcile to the same figure.
Why Do Data Center Construction Materials Supply Chain Market Estimates Differ?
The DC Market Insights figure of USD 13.38 billion for 2026 counts only shell-and-core materials at delivered price, which is about 16% of the USD 65.60 billion Data Center Construction Market of 2025.
Broader definitions of a data center construction materials supply chain add copper electrical materials, mechanical and electrical equipment, installation labour, logistics services or general contractor margin, and some count the whole construction budget, which multiplies the headline figure several times. Others count only one product family such as steel or cement. The land and shells these materials become are valued in the Data Center Real Estate Market, and design fees in the Data Center Design Market. This edition stays at the materials layer so that it adds up with the sibling reports on construction, copper and equipment without double counting.
| Element | In this report | Why |
|---|---|---|
| Structural steel, concrete, precast, envelope, interior and site materials | Yes, USD 10.62 billion in 2025 | Core shell-and-core purchases |
| Copper cable and busbar | No | Covered by the copper electrical materials report |
| Generators, switchgear, chillers | No | Equipment, sized in equipment reports |
| Installation labour and contractor margin | No | Part of construction services value |
| Expansion and rebuild materials in existing sites | Yes, USD 427.20 million in 2025 | Same materials bought for halls added to live campuses |
Out of scope in prose as well: copper electrical materials, mechanical and electrical equipment, installation labour, logistics and freight services, and land. In scope for every buyer group: hyperscale owners, colocation developers and enterprise and edge builders, including smaller regional contractors that buy through distributors.
Market Drivers: What Is Pushing Up Demand for Data Center Construction Materials?
Three forces lift the Data Center Construction Materials Supply Chain Market from USD 10.62 billion in 2025 to USD 13.38 billion in 2026: a record US build, tariff-driven steel prices and supplier pipelines that doubled in a year.
US Data Center Construction Hit a USD 96.46 Billion Annual Rate in September 2026
The US Census Bureau’s construction spending series shows private data center construction rising every month in 2026, from an annual rate of USD 56.21 billion in January to USD 96.46 billion in September (preliminary), now about twice the rate for general office buildings. Annual spending was USD 12.58 billion in 2022 and USD 49.74 billion in 2025. DC Market Insights puts the United States at USD 4.35 billion of shell-and-core materials in 2025, about 8.8% of that construction value.
Section 232 Steel Tariffs at 50% Reprice Every Frame Bought in the United States From June 2025
Proclamation 10947 raised the US tariff on steel and aluminum and their derivatives from 25% to 50% from 4 June 2025, and Proclamation 11021 applied it to the full customs value of derivative products from 6 April 2026. The producer price index (PPI) for steel mill products rose from 312.4 in December 2025 to 388.6 in September 2026 (US Bureau of Labor Statistics), and the index for bar joists and reinforcing bars rose 14% between May and September 2026. DC Market Insights lifts the structural steel price in its model by 8% for 2026.
Saint-Gobain Counts 1,085 Data Center Projects Under Specification in 32 Countries
Saint-Gobain reported on 30 July 2026 that its data center project pipeline had grown to 1,085 projects under specification in 32 countries, almost double a year earlier, with North America at 250 projects against 80. Kingspan reported that its Advnsys data infrastructure division entered 2026 with backlog up 24% and order intake in 2026 to date double the prior year (Kingspan Annual Report 2025). These pipelines support the jump to 15,000 MW of new IT capacity in 2026 in the DC Market Insights model.
Market Trends: How Are Data Center Builders Changing the Materials They Buy?
Hyperscale owners are shifting 2.00% of 2025 value into mass timber and pushing low-carbon concrete and steel into their specifications.
Microsoft and Meta Put Cross-Laminated Timber Into Data Center Shells
Microsoft said in October 2024 that its first hybrid cross-laminated timber (CLT) data centers in northern Virginia cut embodied carbon by 35% against conventional steel construction and 65% against typical precast concrete. Meta began piloting mass timber in 2025 at Aiken, South Carolina, and says it can reduce foundation concrete requirements by up to 50% (Meta, February 2026). DC Market Insights models Mass Timber Hybrid structures rising from USD 212.42 million in 2025 to USD 1.22 billion by 2035.
AI-Designed Low-Carbon Concrete Moves Into Hyperscale Specifications
An AI-optimised concrete mix developed by Meta and Amrize for Meta’s Rosemount, Minnesota data center cut the concrete carbon footprint by an estimated 35% and gained early strength 43% faster (Amrize). Amazon Web Services (AWS) reported 43 data centers built with lower-carbon concrete, steel or both, and higher-strength steel that saves 70 tons per two-storey building (Amazon, October 2023). DC Market Insights keeps these mixes inside the Ready-Mix Concrete and Rebar line, which grows 7.83% a year as slab and foundation volumes per MW fall.
Google Buys 91,000 Tonnes of Green Steel From Stegra
Google agreed in September 2026 to buy green steel certificates for up to 91,000 tonnes from Stegra’s first year of production and says its approach can cut embodied carbon in data center infrastructure by up to 40%. Owner-direct buying of this kind is why Owner-Direct Framework Agreements grow from USD 2.34 billion in 2025 to USD 8.27 billion by 2035 in the DC Market Insights model.
Market Challenges: What Could Slow Data Center Materials Supply?
Two constraints hold the Data Center Construction Materials Supply Chain Market below the pace of construction spending: metals cost volatility and new carbon rules on imported steel and cement.
Steel Price Swings of 107% Since 2020 Make Fixed-Price Shell Contracts Risky
The steel mill products PPI moved from 187.3 in January 2020 to a peak of 449.7 in December 2021, down to 266.5 in December 2024 and back up to 388.6 in September 2026 (US Bureau of Labor Statistics). For a 300 MW campus at 60 tonnes per MW, each 10% move in delivered steel price changes the materials bill by about USD 5.76 million (DC Market Insights estimate).
The EU Carbon Border Adjustment Mechanism Adds a Carbon Cost to Imported Steel and Cement From January 2026
The EU Carbon Border Adjustment Mechanism (CBAM) entered its definitive regime on 1 January 2026 for imports of cement, iron and steel and aluminium, with certificate prices tied to EU emissions trading auctions (European Commission). Importers of under 50 tonnes a year are exempt under Regulation (EU) 2025/2083, but data center frames run to thousands of tonnes, so European builders face higher costs on imported structural steel; DC Market Insights holds Europe at 7.98% a year, below the global rate.
Market Opportunities: Where Will Data Center Materials Suppliers Win the Most?
Prefabricated structures and site civil works for gigawatt campuses carry the largest new value, together worth USD 9.87 billion by 2035.
Prefabricated and Modular Structures Reach USD 5.59 billion by 2035
Clark Pacific says its AccelCore precast system delivers data centers 30-50% faster with floor capacity up to 600 pounds per square foot. DC Market Insights models Prefabricated and Modular Structures growing 14.17% a year from USD 1.49 billion in 2025, as owners trade higher material cost per MW for months saved on site.
Aggregates, Piles and Site Civil Materials for Gigawatt Campuses Reach USD 4.28 billion by 2035
Microsoft’s Fairwater campus in Mount Pleasant, Wisconsin needed 46.6 miles of deep foundation piles on a 315-acre site, and Martin Marietta shipped a record 67.1 million tons of aggregates in the third quarter of 2026 while naming data centers as a source of continued strength. DC Market Insights grows Aggregates and Site Civil Materials 9.74% a year, faster than the market, because gigawatt campuses need more piling, paving and stormwater works per MW.
Pricing: How Much Do Data Center Construction Materials Cost per Megawatt?
Shell-and-core materials cost about USD 849,500 per new MW in 2025, against USD 729,400 in 2020, as steel and concrete prices rose faster than building density (DC Market Insights estimate).
| Year | Materials per new MW (USD) | Structural steel, fabricated and delivered (USD per tonne) | Ready-mix concrete (USD per cubic metre) |
|---|---|---|---|
| 2020 | 729,400 | 1,984 | 128 |
| 2025 | 849,500 | 3,200 | 175 |
| 2030 | 836,100 | 3,668 | 194 |
| 2035 | 848,000 | 3,952 | 214 |
Public price anchors: the fabricated structural metal products PPI stood at 237.5 in January 2020 and 418.3 in September 2026 (+76%), the ready-mix concrete PPI rose from 286.5 to 402.8 (+41%) and the gypsum products PPI from 327.5 to 488.9 (+49%) over the same period (US Bureau of Labor Statistics). The 2030 and 2035 unit prices are DC Market Insights estimates with steel up 1.5% a year and concrete up 2% a year after 2026.
Standards and Regulation: Which Rules Change What Data Center Builders Buy?
Five rules shape the Data Center Construction Materials Supply Chain Market: two US tariff proclamations, the EU carbon border mechanism, the EU buildings directive and US federal low-carbon material limits.
- US Proclamation 10947 (June 2025): Section 232 tariff on steel and aluminum raised to 50% (Source: Federal Register).
- US Proclamation 11021 (April 2026): derivative tariffs apply to the full customs value; 10% for goods made of US-melted metal (Source: Federal Register).
- US Proclamation 11032 (June 2026): steel racks added and the American-metal threshold cut from 95% to 85% (Source: Federal Register).
- EU Carbon Border Adjustment Mechanism, definitive from 1 January 2026, covering cement, iron and steel and aluminium (Source: European Commission).
- EU Energy Performance of Buildings Directive (EU) 2024/1275: life-cycle global warming potential disclosed for new buildings over 1,000 square metres from 2028 and all new buildings from 2030 (Source: European Commission).
- US General Services Administration (GSA) low-embodied-carbon limits for concrete, cement, steel and glass, for example 728 kgCO2e per tonne for top-20% fabricated rebar (Source: GSA, July 2025).
Market Segmentation: Which Segments Lead the Data Center Construction Materials Supply Chain Market?
Structural Steel and Metal Deck leads with USD 2.40 billion in 2025, Cast-in-Place and Steel Frame construction holds 54.00%, and Hyperscale and AI Campuses buy 56.00% of value (DC Market Insights estimate).
Data Center Construction Materials Supply Chain Market by Material Type
Structural steel and envelope systems are almost equal in 2025, but Precast Concrete Components grow fastest at 10.39% as owners move to factory-made elements.
| Segment | 2025 (USD million) | Share 2025 | 2035 (USD million) | CAGR 2025-2035 |
|---|---|---|---|---|
| Structural Steel and Metal Deck | 2,400.55 | 22.60% | 4,918.62 | 7.44% |
| Ready-Mix Concrete and Rebar | 2,219.26 | 20.89% | 4,715.68 | 7.83% |
| Precast Concrete Components | 1,062.75 | 10.01% | 2,856.51 | 10.39% |
| Building Envelope and Roofing Systems | 2,375.55 | 22.37% | 5,641.00 | 9.03% |
| Interior Fire-Rated and Insulation Materials | 875.20 | 8.24% | 1,918.32 | 8.16% |
| Aggregates and Site Civil Materials | 1,687.89 | 15.89% | 4,275.89 | 9.74% |
Data Center Construction Materials Supply Chain Market by Construction Method
Cast-in-Place and Steel Frame falls from 54% to 40% of value by 2035 while Mass Timber Hybrid rises from 2% to 5%.
| Segment | 2025 (USD million) | Share 2025 | 2035 (USD million) | CAGR 2025-2035 |
|---|---|---|---|---|
| Cast-in-Place and Steel Frame | 5,735.45 | 54.00% | 9,730.41 | 5.43% |
| Precast and Tilt-Up | 3,186.36 | 30.00% | 7,784.33 | 9.34% |
| Prefabricated and Modular Structures | 1,486.97 | 14.00% | 5,594.98 | 14.17% |
| Mass Timber Hybrid | 212.42 | 2.00% | 1,216.30 | 19.07% |
Data Center Construction Materials Supply Chain Market by Facility Type
Hyperscale and AI Campuses rise from 56% to 66% of value by 2035; Enterprise and Edge Facilities grow only 2.25% a year.
| Segment | 2025 (USD million) | Share 2025 | 2035 (USD million) | CAGR 2025-2035 |
|---|---|---|---|---|
| Hyperscale and AI Campuses | 5,947.87 | 56.00% | 16,055.17 | 10.44% |
| Colocation Facilities | 3,505.00 | 33.00% | 6,811.29 | 6.87% |
| Enterprise and Edge Facilities | 1,168.33 | 11.00% | 1,459.56 | 2.25% |
Data Center Construction Materials Supply Chain Market by Procurement Model
Contractor-Procured Supply still buys 66.00% of 2025 value, but owner-direct framework buying grows more than twice as fast.
| Segment | 2025 (USD million) | Share 2025 | 2035 (USD million) | CAGR 2025-2035 |
|---|---|---|---|---|
| Contractor-Procured Supply | 7,010.00 | 66.00% | 12,163.01 | 5.67% |
| Owner-Direct Framework Agreements | 2,336.66 | 22.00% | 8,270.85 | 13.47% |
| Modular Integrator-Supplied | 1,274.54 | 12.00% | 3,892.16 | 11.81% |
DC Exclusive: The Shell-and-Core Materials Bill for One New Megawatt, 9 Line Items Totalling USD 849,500
This teardown is a DC Market Insights model estimate built on 13 inputs: nine material quantities and unit prices, the Fairwater steel and floor-area figures, the Abilene campus density and the US producer price indexes.
| Line item | Quantity per MW | Unit price (USD) | USD per MW, 2025 |
|---|---|---|---|
| Structural steel frame and metal deck | 60 tonnes | 3,200 per tonne | 192,000 |
| Ready-mix concrete | 700 cubic metres | 175 per cubic metre | 122,500 |
| Reinforcing steel | 50 tonnes | 1,100 per tonne | 55,000 |
| Precast concrete elements | lump sum | – | 85,000 |
| Insulated metal wall panels | 3,000 square feet | 35 per square foot | 105,000 |
| Roofing system | 5,000 square feet | 17 per square foot | 85,000 |
| Fire-rated gypsum, insulation and fire stopping | lump sum | – | 70,000 |
| Foundation piles and aggregates | lump sum | – | 80,000 |
| Paving, stormwater and site civil | lump sum | – | 55,000 |
| Total | 849,500 |
The steel line is the swing item. Microsoft’s Fairwater campus used 26.5 million pounds (about 12,000 tonnes) of structural steel for 1.2 million square feet under roof, about 22 pounds per square foot; at the density of Crusoe’s 1.2 gigawatt (GW), 4 million square foot Abilene campus (about 3,300 square feet per MW) that works out to about 33 tonnes per MW, roughly half the 60-tonne blended figure used for the mix of AI, colocation and enterprise halls. An AI hall built at that density saves about USD 86,400 of steel per MW, which is why materials per MW stay flat even as steel prices rise.
Regional Insights: Which Region Buys the Most Data Center Construction Materials?
North America leads with USD 4.78 billion in 2025 (45.00%), and Middle East and Africa grows fastest at 13.87% a year to USD 1.95 billion by 2035 (DC Market Insights estimate).
North America Data Center Construction Materials Supply Chain Market
North America reaches USD 9.24 billion by 2035 at 6.82% a year. Saint-Gobain’s North American data center pipeline rose from 80 to 250 projects in a year, and Steel Dynamics reported a steel fabrication backlog nearly 50% above the prior year in September 2026, naming data center development among its drivers.
Europe Data Center Construction Materials Supply Chain Market
Europe grows from USD 1.81 billion in 2025 to USD 3.89 billion by 2035 at 7.98% a year. The Carbon Border Adjustment Mechanism and the 2028 life-cycle carbon disclosure rule push European builders towards local low-carbon steel and cement.
Asia Pacific Data Center Construction Materials Supply Chain Market
Asia Pacific grows 10.05% a year to USD 8.03 billion by 2035, led by China at USD 1.27 billion in 2025 and India at 15.22% a year. Saint-Gobain counted almost 50 data center projects under specification in South-East Asia in July 2026.
Latin America Data Center Construction Materials Supply Chain Market
Latin America grows from USD 424.85 million in 2025 to USD 1.22 billion by 2035 at 11.09% a year, with Brazil at USD 223.05 million in 2025 (DC Market Insights estimate).
Middle East and Africa Data Center Construction Materials Supply Chain Market
Middle East and Africa is the fastest region at 13.87% a year, led by Saudi Arabia, which grows 14.89% a year from USD 169.94 million in 2025 as Gulf AI campuses move into construction (DC Market Insights estimate).
Country Analysis: Which Countries Buy the Most Data Center Construction Materials?
The United States buys USD 4.35 billion or 41.00% of 2025 value, and India is the fastest large country at 15.22% a year (DC Market Insights estimate).
| Rank | Country | Region | 2025 (USD million) | Share 2025 | 2035 (USD million) | CAGR 2025-2035 |
|---|---|---|---|---|---|---|
| 1 | United States | North America | 4,354.69 | 41.00% | 8,368.15 | 6.75% |
| 2 | China | Asia Pacific | 1,274.54 | 12.00% | 3,040.75 | 9.08% |
| 3 | Japan | Asia Pacific | 382.36 | 3.60% | 875.74 | 8.64% |
| 4 | Germany | Europe | 361.12 | 3.40% | 778.43 | 7.98% |
| 5 | Canada | North America | 350.50 | 3.30% | 778.43 | 8.31% |
| 6 | United Kingdom | Europe | 318.64 | 3.00% | 681.13 | 7.89% |
| 7 | India | Asia Pacific | 318.64 | 3.00% | 1,313.61 | 15.22% |
| 8 | Australia | Asia Pacific | 276.15 | 2.60% | 681.13 | 9.45% |
| 9 | Malaysia | Asia Pacific | 276.15 | 2.60% | 729.78 | 10.21% |
| 10 | Brazil | Latin America | 223.05 | 2.10% | 632.48 | 10.99% |
| 11 | Saudi Arabia | Middle East and Africa | 169.94 | 1.60% | 681.13 | 14.89% |
| 12 | Ireland | Europe | 159.32 | 1.50% | 291.91 | 6.24% |
Forecast Scenarios: How Large Could the Data Center Construction Materials Supply Chain Market Be by 2035?
The Data Center Construction Materials Supply Chain Market reaches USD 24.33 billion by 2035 in the base case, within a range of USD 19.48 billion to USD 29.71 billion (DC Market Insights estimate).
| Scenario | 2035 size | CAGR 2025-2035 | Assumption |
|---|---|---|---|
| Low | USD 19.48 billion | 6.26% | New IT capacity 22,000 MW in 2035; steel prices 3% below base |
| Base | USD 24.33 billion | 8.64% | New IT capacity 27,000 MW in 2035; steel +1.5% and concrete +2% a year |
| High | USD 29.71 billion | 10.83% | New IT capacity 32,000 MW in 2035; tariffs and carbon costs lift prices 4% |
Competitive Insights: Who Supplies Materials to Data Center Builders?
The Data Center Construction Materials Supply Chain Market is fragmented: the five largest suppliers by data center sales, Kingspan, Nucor, Amrize, CRH and Saint-Gobain, hold about 19% of 2025 value (DC Market Insights estimate, based on disclosed data-sector sales and shipments; concrete and aggregates are bought locally).
- Kingspan Group
- Nucor Corporation
- Amrize
- CRH
- Saint-Gobain
- Steel Dynamics
- Commercial Metals Company
- ArcelorMittal
- Stegra
- Martin Marietta Materials
- Vulcan Materials
- Heidelberg Materials
- Owens Corning
- Clark Pacific
- Tindall Corporation
- Orion Group Holdings
Kingspan reported EUR 1,654.9 million of 2025 turnover in Advnsys, its data infrastructure division, and plans a Kentucky plant with about USD 600 million of annual revenue potential for the data sector (Kingspan Annual Report 2025); much of Advnsys sits outside this market’s scope in raised floors and containment. Nucor sold 237,000 tons of joist and deck in the third quarter of 2026, up 20% on the second quarter, and shipped 667,000 tons of structural steel (Nucor, October 2026). Commercial Metals Company reported downstream rebar backlog volumes up 15.5% year on year and named data center activity in its merchant bar demand (CMC, October 2026). Amrize said its commercial roofing volumes were led by large-scale data centers in the third quarter of 2026, and CRH cited data center activity in its Americas business (CRH, October 2026).
Recent Developments in the Data Center Construction Materials Supply Chain Market
- In November 2026, Martin Marietta reported record third-quarter aggregates shipments of 67.1 million tons and expected continued strength in data centers (Source: Martin Marietta).
- In October 2026, Amrize reported commercial roofing volumes led by large-scale data centers (Source: Amrize).
- In October 2026, Commercial Metals Company reported downstream backlog volumes up 15.5% year on year, with data center-related activity supporting merchant bar demand (Source: CMC).
- In September 2026, Google agreed to buy green steel certificates for up to 91,000 tonnes from Stegra (Source: Google).
- In July 2026, Saint-Gobain reported 1,085 data center projects under specification in 32 countries (Source: Saint-Gobain).
- In June 2026, Proclamation 11032 added steel racks to the Section 232 derivative list and cut the American-metal threshold to 85% (Source: Federal Register).
Research Methodology: How DC Market Insights Sized the Data Center Construction Materials Supply Chain Market
DC Market Insights sized the Data Center Construction Materials Supply Chain Market bottom-up: new IT capacity of 12,000 MW in 2025, 22,000 MW in 2030 and 27,000 MW in 2035 × materials per MW by six material types (USD 849,500 in 2025), adjusted for price indexes and building density, plus USD 4,000 per installed MW-year for expansions inside live campuses (USD 427.20 million in 2025).
Three bound checks hold the estimate in place. Ceiling one: the USD 10.62 billion of 2025 is about 16% of the USD 65.60 billion DC Market Insights Data Center Construction Market. Ceiling two: the United States share of USD 4.35 billion is about 8.8% of the USD 49.74 billion of US data center construction put in place in 2025 (US Census Bureau). Floor: at Fairwater steel intensity and Abilene density, 12,000 MW × 33 tonnes × USD 3,200 per tonne gives about USD 1.27 billion of structural steel, below the USD 2.40 billion steel line. Segments, five regions and 12 countries are shares that sum to the total each year. See the DC Market Insights research methodology.
Table of contents
- 01Introduction
- 1.1Market Definition and Scope
- 1.2Research Methodology
- 02Executive Summary
- 2.1Market Snapshot, 2025, 2026 and 2035
- 2.2Key Market Statistics
- 2.3Key Takeaways
- 03Market Scope
- 3.1Included Materials
- 3.2Excluded Items
- 3.3Why Estimates Differ
- 04Market Dynamics
- 4.1US Data Center Construction at a USD 96.46 Billion Annual Rate
- 4.2Section 232 Steel Tariffs at 50%
- 4.3Saint-Gobain 1,085-Project Pipeline
- 4.4Cross-Laminated Timber in Data Center Shells
- 4.5AI-Designed Low-Carbon Concrete
- 4.6Google and Stegra Green Steel
- 4.7Steel Price Volatility
- 4.8EU Carbon Border Adjustment Mechanism
- 4.9Prefabricated and Modular Structures Opportunity
- 4.10Aggregates and Site Civil Opportunity
- 05Pricing Analysis
- 5.1Materials per New MW, 2020-2035
- 5.2Steel and Concrete Unit Prices
- 06Standards and Regulation
- 6.1US Section 232 Proclamations
- 6.2EU CBAM
- 6.3EU Energy Performance of Buildings Directive
- 6.4GSA Low-Embodied-Carbon Limits
- 07Market Segmentation by Material Type
- 7.1Structural Steel and Metal Deck
- 7.2Ready-Mix Concrete and Rebar
- 7.3Precast Concrete Components
- 7.4Building Envelope and Roofing Systems
- 7.5Interior Fire-Rated and Insulation Materials
- 7.6Aggregates and Site Civil Materials
- 08Market Segmentation by Construction Method
- 8.1Cast-in-Place and Steel Frame
- 8.2Precast and Tilt-Up
- 8.3Prefabricated and Modular Structures
- 8.4Mass Timber Hybrid
- 09Market Segmentation by Facility Type
- 9.1Hyperscale and AI Campuses
- 9.2Colocation Facilities
- 9.3Enterprise and Edge Facilities
- 10Market Segmentation by Procurement Model
- 10.1Contractor-Procured Supply
- 10.2Owner-Direct Framework Agreements
- 10.3Modular Integrator-Supplied
- 11DC Exclusive: Shell-and-Core Materials Bill per MW
- 11.1Nine Line Items, USD 849,500
- 11.2Steel Intensity at AI Density
- 12Regional Insights
- 12.1North America
- 12.2Europe
- 12.3Asia Pacific
- 12.4Latin America
- 12.5Middle East and Africa
- 13Country Analysis
- 13.1United States
- 13.2China
- 13.3Japan
- 13.4Germany
- 13.5Canada
- 13.6United Kingdom
- 13.7India
- 13.8Australia
- 13.9Malaysia
- 13.10Brazil
- 13.11Saudi Arabia
- 13.12Ireland
- 14Forecast Scenarios
- 14.1Low Case
- 14.2Base Case
- 14.3High Case
- 15Competitive Insights
- 15.1Kingspan Group
- 15.2Nucor Corporation
- 15.3Amrize
- 15.4CRH
- 15.5Saint-Gobain
- 15.6Steel Dynamics
- 15.7Commercial Metals Company
- 15.8ArcelorMittal
- 15.9Stegra
- 15.10Martin Marietta Materials
- 15.11Vulcan Materials
- 15.12Heidelberg Materials
- 15.13Owens Corning
- 15.14Clark Pacific
- 15.15Tindall Corporation
- 15.16Orion Group Holdings
- 16Recent Developments
- 16.1Developments, June-November 2026
- 17Research Methodology
- 17.1Bottom-Up Model
- 17.2Bound Checks
- Fig. 1Data Center Construction Materials Supply Chain Market Size, 2020-2035
- Table 1Market Attributes
- Table 2Scope Comparison
- Table 3Materials Price per MW, 2020-2035
- Table 4Market by Material Type
- Table 5Market by Construction Method
- Table 6Market by Facility Type
- Table 7Market by Procurement Model
- Table 8Shell-and-Core Materials Bill per MW
- Table 9Top 12 Countries
- Table 10Forecast Scenarios, 2035
About this report
Written by Amit Jain and reviewed by Deepti Agrawal, Senior Editor, Research. Figures are built top-down and bottom-up and reconciled before publication, with 2025 as the base year.
Read our methodologyHow we built this
- Historical period2020-2024
- Base year2025
- Forecast period2026-2035
- Sizing approachTop-down + bottom-up
Need more than the report?
Advisory on this market
Due diligence, site selection and market entry work, by the analysts who wrote this report.
See consulting servicesFrequently asked questions
USD 13.38 billion in 2026, up 26.01% from USD 10.62 billion in 2025, according to DC Market Insights estimates. The market is projected to reach USD 24.33 billion by 2035, a CAGR of 8.64% from 2025.
8.64% a year from 2025 to 2035, after 22.57% a year from 2020 to 2025, as new data center IT capacity rises from 12,000 MW in 2025 to 27,000 MW a year by 2035 (DC Market Insights estimate).
About USD 849,500 of shell-and-core materials per new MW in 2025, including about 60 tonnes of structural steel, 700 cubic metres of concrete and 50 tonnes of rebar (DC Market Insights estimate). Microsoft’s Fairwater campus used about 12,000 tonnes of structural steel.
Structural Steel and Metal Deck, with USD 2.40 billion or 22.60% of 2025 value. Precast Concrete Components grow fastest among material types at 10.39% a year.
The Section 232 tariff on steel rose to 50% from 4 June 2025 and applies to the full customs value of derivative products from 6 April 2026. The steel mill products price index rose 24% from December 2025 to September 2026.
From 1 January 2026 the EU Carbon Border Adjustment Mechanism charges a carbon cost on imported cement, iron and steel and aluminium, priced on EU emissions trading auctions, which raises the cost of imported structural steel for European data centers.
North America, with USD 4.78 billion or 45.00% of 2025 value. Middle East and Africa grows fastest at 13.87% a year, and India is the fastest large country at 15.22%.
Yes. 2.00% of 2025 value is Mass Timber Hybrid structures, growing 19.07% a year. Microsoft’s cross-laminated timber data centers cut embodied carbon 35% against steel, and Meta began mass timber pilots in 2025.
About 19% of 2025 value goes to Kingspan, Nucor, Amrize, CRH and Saint-Gobain (DC Market Insights estimate). Steel Dynamics, Commercial Metals Company, ArcelorMittal, Stegra, Martin Marietta and Clark Pacific are also active.
The DC Market Insights figure of USD 13.38 billion for 2026 counts only shell, structure, envelope and site materials at delivered price. Estimates that add copper electrical materials, equipment, labour or contractor margin are several times larger.
Get this report
How do I get the full report?
Request a quote; we reply by email within one business day.
How and when will I receive the report?
By email, within 24–48 business hours of payment.
How can I pay?
Once you accept the quote, we email you a secure payment link.
Can I see a sample first?
Yes. Request a free sample and we will email it to you.
Can the report be tailored to my needs?
Yes. We can add countries, segments or data cuts. Talk to an analyst about the scope you need.
Can I get an invoice or pay against a purchase order?
Write to sales@dcmarketinsights.com and our team will help.