
Vietnam Data Center Cooling Market Size, Share & Forecast to 2035
Market at a glance
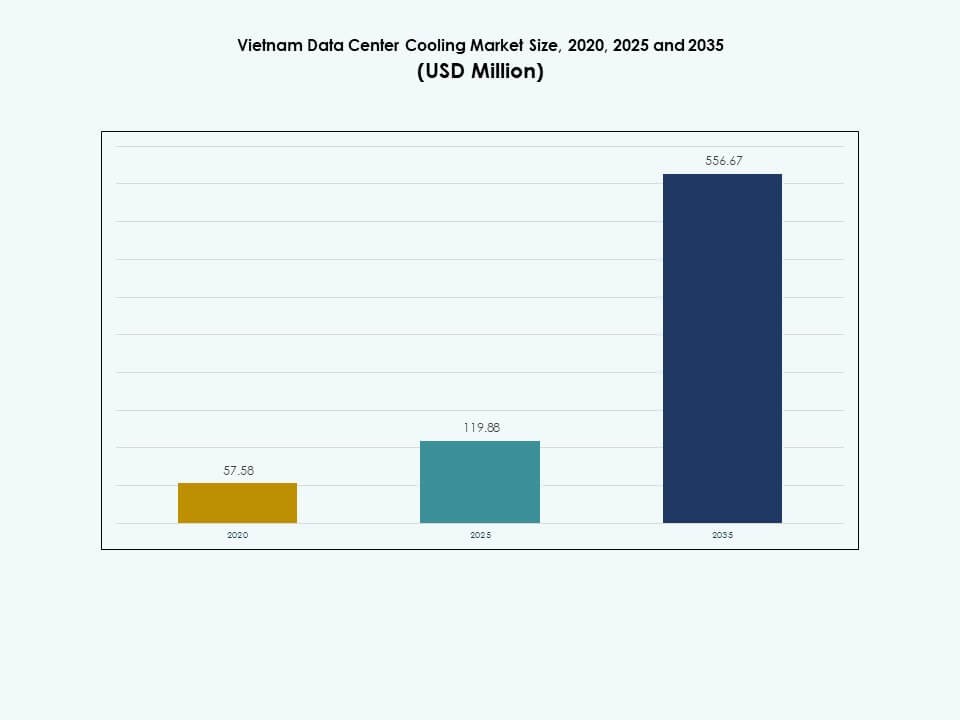
The Vietnam Data Center Cooling market was worth USD 119.9 million in 2025 and is forecast to reach USD 556.7 million by 2035, growing at a 16.52% CAGR.
 By Satyabrat Rajawat, Senior Research Analyst, Strategic Advisory
 Reviewed by Deepti Agrawal
Last updated 3 Dec 2025
Base year 2024 PDF + Excel
Key findings
Growing Deployment of Liquid and Immersion Cooling for AI Workloads
High Infrastructure Costs and Limited Availability of Skilled Technical Talent
Rising Demand for Green Cooling and Low-Energy Designs
What is inside the report
- 01Introduction
- 02Executive Summary
- 03Market Dynamics
- 04Vietnam Data Center Cooling Market – Market Sizing & Forecast
- 05Capital Expenditure (CapEx) Analysis
- 06Data Center Cooling Capacity & Utilization
- 07Data Center Cooling Market, Energy & Resource Consumption Analysis
- 08Vietnam Data Center Cooling Market – By Component
- 09Vietnam Data Center Cooling Market – By Data Center Cooling Solution
- 10Vietnam Data Center Cooling Market – By Service
- 20chapters
- 2020-2023Historical period
- 2025-2035Forecast period
- 9Companies profiled
Segmentation
Companies profiled
- Daikin Industries Ltd
- Mitsubishi Electric Corporation
- Carrier
- Johnson Controls International plc
- Danfoss
- Vertiv Group Corp
- Schneider Electric
- STULZ GmbH
- CoolIT Systems
Recent developments
Daikin Applied announced the acquisition of Chilldyne, a leader in negative pressure liquid cooling for data centers, solidifying Daikin's commitment to advanced cooling technologies for hyperscale and AI data centers.
Mitsubishi Electric Corporation entered into a memorandum of understanding with Hon Hai Precision Industry Co., Ltd. (Foxconn) to establish a global alliance for AI data center solutions, aiming to supply advanced cooling systems and intelligent infrastructure for hyperscale environments.
Boyd announced the expansion of its manufacturing facility in Bac Ninh, Vietnam, doubling its space to 800,000 square feet to boost production of liquid cooling solutions for data centers, especially those leveraging artificial intelligence. This development is aimed at addressing the growing demand for advanced cooling systems capable of handling high thermal density and compute loads.
Carrier Global Corporation formed an investment and technology partnership with ZutaCore, an innovator in two-phase direct-to-chip liquid cooling. The collaboration focuses on developing high-performance cooling solutions targeted at AI and high-density computing workloads, establishing a foundation for sustainable, waterless cooling in new-generation data centers.
Full analysis
Executive summary
The Vietnam Data Center Cooling Market size was valued at USD 57.58 million in 2020 to USD 119.88 million in 2025 and is anticipated to reach USD 556.67 million by 2035, at a CAGR of 16.52% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2035 |
| Vietnam Data Center Cooling Market Size 2025 | USD 119.88 Million |
| Vietnam Data Center Cooling Market, CAGR | 16.52% |
| Vietnam Data Center Cooling Market Size 2035 | USD 556.67 Million |
Strong market growth is driven by rising deployment of high-density workloads, advanced cooling adoption, and rapid expansion of hyperscale and colocation facilities. Operators shift to liquid cooling, precision systems, and AI-driven thermal control to manage heavier heat loads. Innovation in energy-efficient systems strengthens long-term value for investors. Businesses prioritize cooling upgrades to secure performance stability and support complex digital applications across sectors.
Northern Vietnam leads due to major hyperscale clusters and strong connectivity infrastructure. Southern provinces expand quickly as enterprise and retail sectors scale digital footprints. Central Vietnam emerges as a developing zone due to increasing land availability and supportive local policies. Each region diversifies growth by attracting new cooling investments aligned with rising cloud, telecom, and data-driven demands.
Market Drivers
Rising Demand for High-Density Workloads and Efficient Cooling Technologies
The Vietnam Data Center Cooling Market gains momentum from stronger AI and cloud needs. High-density racks push operators to adopt liquid and precision cooling. Many facilities replace legacy systems to reduce heat stress in new workloads. Investors treat Vietnam as a strategic point for regional computing growth. Businesses expand capacity to support fast digital adoption in major cities. It strengthens the role of efficient cooling across new builds. Operators deploy advanced systems to maintain stable rack performance. The trend shapes long-term infrastructure spending across the country. Cooling vendors target Vietnam due to predictable demand growth.
- For example, Viettel’s Hoa Lac Data Center in Hanoi operates with a reported PUE of 1.4–1.45 and uses renewable energy for 30% of its power supply. The facility is Vietnam’s largest, supporting over 2,400 racks with a total capacity of 30 MW. HSBC confirmed the site’s eligibility for sustainable financing based on its green infrastructure commitments.
Growing Focus on Energy Efficiency and Green Cooling Innovation
Energy rules push data centers to adopt efficient cooling designs. Operators shift toward modular chillers and low-power cooling lines. Many projects now test AI-driven controls to cut energy use. Green goals increase interest in systems with strong power savings. The market supports new eco-friendly cooling models in hyperscale sites. It opens space for advanced innovation across the supply chain. Businesses view efficient cooling as a direct cost advantage. Investors show confidence in Vietnam due to stable energy planning. Operators treat green cooling as a core design requirement.
- For example, FPT Telecom operates the Fornix HCM01 data center in Ho Chi Minh City, which is built to meet Tier III standards and serves large enterprise and cloud clients. The facility has been featured in national tech events such as FPT Techday, where the company highlighted its data-center expansion and digital infrastructure capabilities. These updates reflect ongoing improvements in reliability and operational performance.
Shift Toward Large-Scale Hyperscale and Colocation Expansion Across Key Cities
Hyperscale demand grows in Hanoi and Ho Chi Minh City. Colocation firms upgrade cooling to support dense compute zones. It strengthens the Vietnam Data Center Cooling Market as new builds scale. Many sites deploy liquid cooling lines for AI and GPU workloads. Enterprises trust facilities that manage heat with stable redundancy. Investors back large projects due to strong long-term returns. New digital rules encourage higher cooling standards. Vietnam attracts global players seeking safe expansion zones. Cooling adoption rises as more workloads shift to cloud.
Rapid Digitalization Across Telecom, BFSI, and Retail Sectors
Telecom networks expand edge locations that need stable cooling. BFSI sites deploy precision cooling to secure sensitive platforms. Retail platforms depend on reliable cooling to support online operations. Many firms upgrade IT rooms to avoid heat-related failures. It drives steady use of advanced cooling systems. Businesses view cooling as a core part of their digital plans. Investors monitor thermal stability as a sign of site quality. Sector growth supports new projects across major provinces. Cooling adoption stays strong across regulated industries.
Market Trends
Growing Deployment of Liquid and Immersion Cooling for AI Workloads
AI demand pushes facilities to adopt liquid and immersion cooling. Operators redesign racks to support higher heat outputs. Many sites test immersion tanks for dense GPU clusters. The trend builds new interest in coolant-based designs. It supports stable load cycles in advanced compute zones. Businesses rely on these systems to avoid heat spikes. The Vietnam Data Center Cooling Market shifts toward high-density cooling lines. Investors track immersion trials as firms scale AI workloads. Adoption grows fastest in hyperscale environments.
Rising Use of Modular Cooling Units in New Data Center Builds
Developers adopt modular units to cut build time. Many sites install prefabricated cooling blocks for faster setup. Operators trust modular units for predictable performance control. The trend supports flexible expansion in crowded cities. It reduces energy waste with targeted airflow direction. Businesses prefer compact units in dense zones. Investors back modular growth due to low deployment risk. Modular cooling gains traction across mid-sized projects. It supports scalable growth models.
Integration of Smart Monitoring and AI-Based Cooling Control
Facilities deploy sensors to track airflow and heat trends. AI tools adjust cooling output to avoid energy waste. Operators use dashboards to monitor real-time thermal conditions. Many sites improve uptime through automated cooling cycles. The trend supports stronger reliability in digital services. Businesses treat smart cooling as a growth enabler. Investors view data-driven cooling as a safe choice. Smart upgrades reshape operational planning across sites. It aligns cooling with dynamic workloads.
Shift Toward Low-Water and Sustainable Cooling Systems
Facilities prioritize low-water systems to manage climate concerns. Many projects integrate air-cooled chillers to reduce water use. Operators favor sustainable units with stronger energy control. The trend supports new green certifications across sites. Businesses link cooling decisions to long-term climate plans. Investors monitor sustainable cooling lines for portfolio gains. Green models improve brand trust in key industries. It strengthens the push toward eco-friendly data center growth. Adoption accelerates in new urban projects.
Market Challenges
High Infrastructure Costs and Limited Availability of Skilled Technical Talent
High capital needs limit adoption of advanced cooling lines. Many firms delay upgrades due to cost pressure. Operators struggle to hire skilled thermal engineers. The Vietnam Data Center Cooling Market needs more trained specialists. Frequent skill gaps slow complex cooling deployments. Businesses depend on foreign partners for advanced setup. Investors track these limits before funding large builds. It raises challenges for sites managing dense workloads. Growth needs stronger training efforts.
Power Supply Constraints and Regulatory Complexity Across Key Provinces
Power rules vary across major regions. Many sites face delays due to approval cycles. Operators manage heat stress during power constraints. The market faces hurdles due to grid reliability issues. Complex rules slow cooling expansion in crowded zones. Investors monitor policy changes to plan spending. High heat loads create further planning pain points. It limits the pace of cooling modernization. Many firms request simpler approval processes.
Market Opportunities
Expansion of Hyperscale and Edge Data Centers Across Vietnam
Hyperscale demand brings new cooling opportunities across major cities. Edge builds push need for compact cooling units. Many sites adopt liquid cooling to manage high heat loads. Operators invest in scalable cooling designs for long-term use. The Vietnam Data Center Cooling Market benefits from this shift. Businesses value reliable thermal control for digital platforms. Investors gain new entry points across provinces. It builds stronger interest in advanced cooling innovation. Growth expands with every new compute zone.
Rising Demand for Green Cooling and Low-Energy Designs
Green rules create demand for efficient systems. Many sites adopt eco-friendly cooling units to save energy. Operators use AI to control airflow with low power use. Businesses prefer green-certified facilities for corporate goals. The market supports new sustainable cooling solutions. Investors prioritize low-energy lines for stable returns. It strengthens focus on innovation in cooling methods. Demand rises fastest in new urban hubs. Growth aligns with national sustainability goals.
Market Segmentation
By Component
The Vietnam Data Center Cooling Market shows strong dominance of solution-based deployments. Cooling solutions hold the highest share due to wide use in hyperscale, edge, and enterprise sites. Services expand steadily as operators need support for integration and maintenance. Many firms rely on deployment services during capacity upgrades. Consulting grows due to rising demand for cooling optimization. Investors treat solution segments as safe assets due to steady growth. Adoption stays strong across regulated industries. Cooling services create value through long-term contracts. Demand rises as systems scale nationwide.
By Data Center Cooling Solution
Precision air conditioners lead due to strong use in controlled environments. Many hyperscale and enterprise sites depend on precise temperature control. Chillers maintain a solid share due to stable thermal output. Liquid cooling grows fastest in AI-heavy projects. Air handling units support large layouts across major cities. The Vietnam Data Center Cooling Market gains traction as systems modernize. Operators favor solutions that support dense workloads. Growth remains strong in multi-tenant facilities. Demand rises as complexity increases across builds.
By Service
Installation and deployment services lead due to high project activity. Many new builds require full integration support. Maintenance holds strong share due to heavy use of chilled systems. Support and consulting grow as operators improve reliability. The Vietnam Data Center Cooling Market benefits from these service layers. Businesses rely on service partners for uptime. Investors trust service-led models for stable revenue. Many firms seek tailored service bundles. Growth expands in new hyperscale clusters.
By Enterprise Size
Large enterprises dominate due to major digital transformation efforts. Many prefer advanced cooling to manage dense workloads. SMEs increase adoption as cloud use grows. It supports stable growth across smaller server rooms. The Vietnam Data Center Cooling Market expands with both groups. Large firms deploy high-power units across multiple racks. SMEs choose modular cooling for cost control. Many projects scale with rising regional demand. Growth remains strong in digital-first sectors.
By Floor Type
Raised floors hold strong share due to structured cooling layouts. Many sites rely on raised floors to optimize airflow. Non-raised floors grow in modern builds with newer layouts. The Vietnam Data Center Cooling Market supports both formats. Operators choose raised floors in legacy and enterprise sites. Edge sites adopt non-raised floors for compact designs. Many developers blend both for flexible builds. Growth aligns with new project designs. Cooling integration depends on site structure.
By Containment
Hot aisle containment leads in advanced facilities due to strong efficiency. Cold aisle containment holds steady share across older builds. Raised floors without containment remain common in small setups. The Vietnam Data Center Cooling Market shifts toward strong containment planning. Many hyperscale sites deploy HAC to control heat leakage. CAC stays relevant across mid-sized rooms. Operators upgrade containment for better airflow. Many firms add containment during expansion cycles. Efficiency goals shape new deployments.
By Structure
Room-based cooling dominates due to wide adoption in older sites. Row-based cooling grows due to strong efficiency control. Rack-based cooling expands fastest in AI and GPU-heavy workloads. The Vietnam Data Center Cooling Market adapts to dense compute zones. Many developers test rack-based systems for heavy heat loads. Row-based units provide structured temperature control. Room cooling remains cost-effective for large halls. Growth spreads across all formats. Adoption aligns with project scale.
By Application
Hyperscale data centers lead due to massive compute demand. Colocation sites maintain strong share across major cities. Enterprise data centers adopt precision cooling for stable loads. Edge sites grow due to telecom expansion. The Vietnam Data Center Cooling Market supports all applications. Many firms upgrade cooling for long-term reliability. Hyperscale growth drives new liquid cooling lines. Enterprise upgrades remain steady across sectors. Edge builds attract new investment.
By End-user
Telecom leads due to strong 5G and edge growth. IT firms follow with heavy digital workloads. Retail and BFSI adopt stable cooling for critical platforms. Healthcare grows due to sensitive data needs. Energy sites depend on cooling for industrial systems. The Vietnam Data Center Cooling Market supports diverse industries. Many firms upgrade to meet heat demands. Growth spreads across all major verticals. Cooling remains core to digital continuity.
Regional Insights
Northern Vietnam – 55% Share
Northern Vietnam holds the largest share at 55%. Strong hyperscale and colocation growth drives cooling demand. The region hosts major cloud clusters and enterprise hubs. Many developers choose Hanoi due to stable connectivity. The Vietnam Data Center Cooling Market gains strength in this zone. It benefits from better power access and skilled labor. Many investors treat the region as a primary hub. Growth stays stable across large facilities.
- For instance, Boyd Corporation announced in September 2025 the expansion of its Bac Ninh manufacturing facility in Northern Vietnam, doubling its capacity to 800,000 square feet for liquid cooling solutions tailored for AI data centers. This upgrade supports advanced direct-to-chip cooling, allowing hyperscale facilities in the region to handle increased power and thermal density for demanding cloud workloads.
Southern Vietnam – 35% Share
Southern Vietnam maintains a 35% share backed by strong enterprise activity. Ho Chi Minh City hosts many private data centers. Retail and BFSI clusters drive cooling needs. The zone attracts investors due to strong economic growth. The Vietnam Data Center Cooling Market expands with business demand. Many sites adopt modular cooling for dense layouts. Growth rises with digital service expansion. Cooling upgrades increase across mid-sized facilities.
- For example, in July 2024, CMC Corporation invested USD 12.5 million to establish CMC AI Digital Infrastructure (CMC ADI) in the Tan Thuan Export Processing Zone. The new subsidiary focuses on developing and operating hyperscale data centers to support Vietnam’s growing digital economy. Public announcements highlight CMC’s plan to accelerate large-scale infrastructure growth through this dedicated data-center platform.
Central Vietnam – 10% Share
Central Vietnam holds a 10% share due to emerging activity. Da Nang hosts new edge and enterprise sites. Many operators select the zone for land availability. The Vietnam Data Center Cooling Market grows with government support. It gains attention from firms seeking low-cost expansion. Digital adoption rises across industries in the region. Growth remains steady in upcoming projects. Cooling adoption increases across new builds.
Competitive Insights
- Daikin Industries Ltd.
- Mitsubishi Electric Corporation
- Carrier
- Johnson Controls International plc
- Danfoss
- Vertiv Group Corp.
- Schneider Electric
- STULZ GmbH
- Rittal GmbH & Co. KG
- CoolIT Systems
The Vietnam Data Center Cooling Market features strong competition among global HVAC leaders and advanced cooling specialists. Vertiv and Schneider Electric hold solid positions due to integrated cooling portfolios tailored for hyperscale and colocation needs. Daikin, Mitsubishi Electric, and Carrier strengthen their presence through energy-efficient chillers and high-performance CRAC systems. Danfoss expands influence through component innovation that supports liquid and hybrid cooling. STULZ and Rittal provide precision cooling systems that appeal to enterprise and telecom operators. CoolIT Systems gains traction with liquid cooling solutions for AI and GPU-dense racks. The market rewards firms that deliver low-energy performance, quick deployment, and stable thermal control. It encourages ongoing innovation as operators scale capacity and handle higher rack densities across major regions.
Recent Developments
- In November 2025, Daikin Applied announced the acquisition of Chilldyne, a leader in negative pressure liquid cooling for data centers, solidifying Daikin’s commitment to advanced cooling technologies for hyperscale and AI data centers.
- In November 2025, Mitsubishi Electric Corporation entered into a memorandum of understanding with Hon Hai Precision Industry Co., Ltd. (Foxconn) to establish a global alliance for AI data center solutions, aiming to supply advanced cooling systems and intelligent infrastructure for hyperscale environments.
- In September 2025, Boyd announced the expansion of its manufacturing facility in Bac Ninh, Vietnam, doubling its space to 800,000 square feet to boost production of liquid cooling solutions for data centers, especially those leveraging artificial intelligence. This development is aimed at addressing the growing demand for advanced cooling systems capable of handling high thermal density and compute loads.
- In February 2025, Carrier Global Corporation formed an investment and technology partnership with ZutaCore, an innovator in two-phase direct-to-chip liquid cooling. The collaboration focuses on developing high-performance cooling solutions targeted at AI and high-density computing workloads, establishing a foundation for sustainable, waterless cooling in new-generation data centers.
Table of contents
- 01Introduction
- 1.1Market Definition & Scope
- 1.2Research Methodology
- 1.2.1Primary Research
- 1.2.2Secondary Research
- 1.2.3Data Validation & Assumptions
- 1.3Market Segmentation Framework
- 02Executive Summary
- 2.1Market Snapshot
- 2.2Key Findings
- 2.3Analyst Recommendations
- 2.4Market Outlook (2025–2035)
- 03Market Dynamics
- 3.1Market Drivers
- 3.2Market Restraints
- 3.3Market Opportunities
- 3.4Challenges & Risks
- 3.5Value Chain Analysis
- 3.6Porter’s Five Forces Analysis
- 04Vietnam Data Center Cooling Market – Market Sizing & Forecast
- 4.1Historical Market Size (2020–2025)
- 4.2Forecast Market Size (2026–2035)
- 4.3Market Growth Rate Analysis
- 4.4Market Outlook by Country
- 05Capital Expenditure (CapEx) Analysis
- 5.1CapEx Trends by Cooling Solution
- 5.1.1Investment patterns across air-based, liquid-based, hybrid, and immersion cooling
- 5.1.2CapEx share by cooling equipment type (CRAC/CRAH, chillers, cooling towers, economizers, etc.)
- 5.1.3Country-wise CapEx trends
- 5.1.4OEM vs. retrofit investment analysis
- 5.2Return on Investment (ROI) & Payback Period Analysis
- 5.2.1ROI by cooling technology type
- 5.2.2Cost-benefit comparison: air cooling vs. liquid cooling vs. immersion cooling
- 5.2.3Payback period across Tier I–IV data centers
- 5.2.4Case examples of cost savings through energy-efficient cooling adoption
- 06Data Center Cooling Capacity & Utilization
- 6.1Installed Capacity (MW & Sq. Ft.) by Cooling Solution
- 6.1.1Installed cooling capacity by solution type and Country
- 6.1.2Cooling system density (kW/rack and per sq. ft.)
- 6.1.3Capacity expansion trends by hyperscale vs. colocation vs. enterprise
- 6.2Utilization Rates & Efficiency Metrics
- 6.2.1Cooling system utilization vs. design capacity
- 6.2.2Average and peak load management practices
- 6.2.3Equipment lifecycle and performance benchmarks
- 6.3Power Usage Effectiveness (PUE) & Energy Efficiency
- 6.3.1Average PUE by data center size and cooling technology
- 6.3.2Comparison of traditional vs. green cooling systems
- 6.3.3Cooling system contribution to total facility energy consumption
- 6.4Rack Density & Cooling Efficiency
- 6.4.1Average rack density (kW/rack) trends
- 6.4.2Cooling adequacy vs. rack load
- 6.4.3Relationship between high-density workloads (AI, HPC) and cooling requirements
- 07Data Center Cooling Market, Energy & Resource Consumption Analysis
- 7.1Energy Consumption Analysis
- 7.1.1Total energy consumption by cooling solution type (air-based, liquid, hybrid, immersion)
- 7.1.2Energy intensity per MW of IT load
- 7.1.3Energy share of cooling in total facility power (cooling load ratio)
- 7.1.4Annualized Energy Efficiency Ratio (EER / SEER) by cooling system type
- 7.1.5Trend in energy consumption reduction through automation, AI, and free cooling technologies
- 7.2Water Consumption Analysis
- 7.2.1Water Usage Effectiveness (WUE) – liters per kWh of IT load
- 7.2.2Water consumption by cooling technology (evaporative cooling, adiabatic cooling, etc.)
- 7.2.3Water recycling and reuse systems in data centers
- 7.2.4Impact of Country-wise water scarcity regulations on cooling system choice
- 7.2.5Shift from water-intensive to air-based or hybrid systems
- 7.3Combined Energy–Water Efficiency Metrics
- 7.3.1Energy-Water Nexus in cooling optimization
- 7.3.2Correlation between PUE, WUE, and total operational cost (OpEx)
- 7.3.3Case studies of zero-water or waterless cooling deployments
- 7.4Benchmarking & Comparative Analysis
- 7.4.1Benchmarking against ASHRAE, Uptime Institute, and DOE standards
- 7.4.2Comparison of Vietnam WUE/PUE averages by Country
- 7.4.3Best practices adopted by hyperscalers (AWS, Google, Microsoft, Meta, etc.)
- 08Vietnam Data Center Cooling Market – By Component
- 8.1Solution
- 8.2Services
- 09Vietnam Data Center Cooling Market – By Data Center Cooling Solution
- 9.1Air Conditioners
- 9.2Precision Air Conditioners
- 9.3Chillers
- 9.4Air Handling Units
- 9.5Liquid Cooling
- 9.6Others
- 10Vietnam Data Center Cooling Market – By Service
- 10.1Installation & Deployment
- 10.2Support & Consulting
- 10.3Maintenance Services
- 11Vietnam Data Center Cooling Market – By Enterprise Size
- 11.1Large Enterprises
- 11.2Small & Medium Enterprises (SMEs)
- 12Vietnam Data Center Cooling Market – By Floor Type
- 12.1Raised Floors
- 12.2Non-Raised Floors
- 13Vietnam Data Center Cooling Market – By Containment
- 13.1Raised Floor with Hot Aisle Containment (HAC)
- 13.2Raised Floor with Cold Aisle Containment (CAC)
- 13.3Raised Floor without Containment
- 14Vietnam Data Center Cooling Market – By Structure
- 14.1Rack-Based Cooling
- 14.2Row-Based Cooling
- 14.3Room-Based Cooling
- 15Vietnam Data Center Cooling Market – By Application
- 15.1Hyperscale Data Center
- 15.2Colocation Data Center
- 15.3Enterprise Data Center
- 15.4Edge Data Center
- 15.5Other Data Centers
- 16Vietnam Data Center Cooling Market – By End-user
- 16.1Telecom
- 16.2IT
- 16.3Retail
- 16.4Healthcare
- 16.5BFSI
- 16.6Energy
- 16.7Others
- 17Sustainability & Green Data Center Cooling
- 17.1Energy Efficiency Initiatives
- 17.1.1Deployment of free cooling, adiabatic cooling, and economizers
- 17.1.2Smart control systems for temperature and airflow optimization
- 17.1.3Case studies of efficiency improvement programs
- 17.2Renewable Energy Integration
- 17.2.1Integration of solar, wind, or geothermal sources in cooling operations
- 17.2.2Hybrid systems combining renewable energy with mechanical cooling
- 17.3Carbon Footprint & Emission Analysis
- 17.4GHG reduction initiatives
- 17.5LEED & Green Certifications
- 17.5.1Share of cooling systems installed in LEED, BREEAM, or Energy Star certified facilities
- 17.5.2Compliance with ASHRAE and ISO energy efficiency standards
- 18Emerging Technologies & Innovations
- 18.1.1Emerging Technologies & Innovations
- 18.1.2Liquid Cooling & Immersion Cooling
- 18.1.3Adoption rate and technology maturity
- 18.1.4Key vendors and installations by Country
- 18.1.5Comparative analysis: performance, cost, and energy savings
- 18.2AI & HPC Infrastructure Integration
- 18.2.1Cooling demand driven by AI training clusters and HPC systems
- 18.2.2Adaptation of cooling design to high heat density workloads
- 18.3Quantum Computing Readiness
- 18.3.1Cooling requirements for quantum processors
- 18.3.2Potential cooling technologies suitable for quantum environments
- 18.4Modular & Edge Data Center Cooling
- 18.4.1Cooling strategies for prefabricated and modular facilities
- 18.4.2Compact and adaptive cooling for edge sites
- 18.5Automation, Orchestration & AIOps
- 18.5.1Integration of AI-driven thermal management
- 18.5.2Predictive maintenance and automated cooling optimization
- 19Competitive Landscape
- 19.1Market Share Analysis
- 19.2Key Player Strategies
- 19.3Mergers, Acquisitions & Partnerships
- 19.4Product & Service Launches
- 20Company Profiles
- 20.1Daikin Industries Ltd.
- 20.2Mitsubishi Electric Corporation
- 20.3Carrier
- 20.4Johnson Controls International plc
- 20.5Danfoss
- 20.6Vertiv Group Corp.
- 20.7Schneider Electric
- 20.8STULZ GmbH
- 20.9Rittal GmbH & Co. KG
- 20.10CoolIT Systems
About this report
Written by Satyabrat Rajawat and reviewed by Deepti Agrawal, Senior Editor, Research. Figures are built top-down and bottom-up and reconciled before publication, with 2024 as the base year.
Read our methodologyHow we built this
- Historical period2020-2023
- Base year2024
- Forecast period2025-2035
- Sizing approachTop-down + bottom-up
Need more than the report?
Advisory on this market
Due diligence, site selection and market entry work, by the analysts who wrote this report.
See consulting servicesFrequently asked questions
The Vietnam Data Center Cooling Market stood at USD 119.88 million in 2025. It is projected to reach USD 556.67 million by 2035, supported by strong demand for efficient cooling in expanding digital infrastructures.
The Vietnam Data Center Cooling Market is expected to grow at a 16.52% CAGR from 2025 to 2035. This growth reflects rising AI workloads, hyperscale investment, and stronger adoption of advanced cooling designs.
In 2025, solution components, particularly precision air conditioners and chillers, held the largest share of the Vietnam Data Center Cooling Market. Strong deployment across hyperscale and colocation facilities drove this lead.
The Vietnam Data Center Cooling Market grows due to rising high-density workloads, green cooling innovation, hyperscale expansion, and stronger digital adoption across regulated sectors. Investors push demand for efficient and scalable cooling systems.
Key players in the Vietnam Data Center Cooling Market include Daikin, Mitsubishi Electric, Carrier, Johnson Controls, Danfoss, Vertiv, Schneider Electric, STULZ, Rittal, and CoolIT Systems. These firms lead through advanced cooling portfolios.
Northern Vietnam held the largest share of the Vietnam Data Center Cooling Market in 2025 at 55%. The region leads due to major hyperscale clusters, strong connectivity, and consistent investment in high-capacity cooling systems.
Get this report
How do I get the full report?
Request a quote; we reply by email within one business day.
How and when will I receive the report?
By email, within 24-48 business hours of payment.
How can I pay?
Once you accept the quote, we email you a secure payment link.
Can I see a sample first?
Yes. Request a free sample and we will email it to you.
Can the report be tailored to my needs?
Yes. We can add countries, segments or data cuts. Talk to an analyst about the scope you need.
Can I get an invoice or pay against a purchase order?
Write to sales@dcmarketinsights.com and our team will help.