
Japan Data Center Infrastructure Market Size, Share & Forecast to 2035
Market at a glance
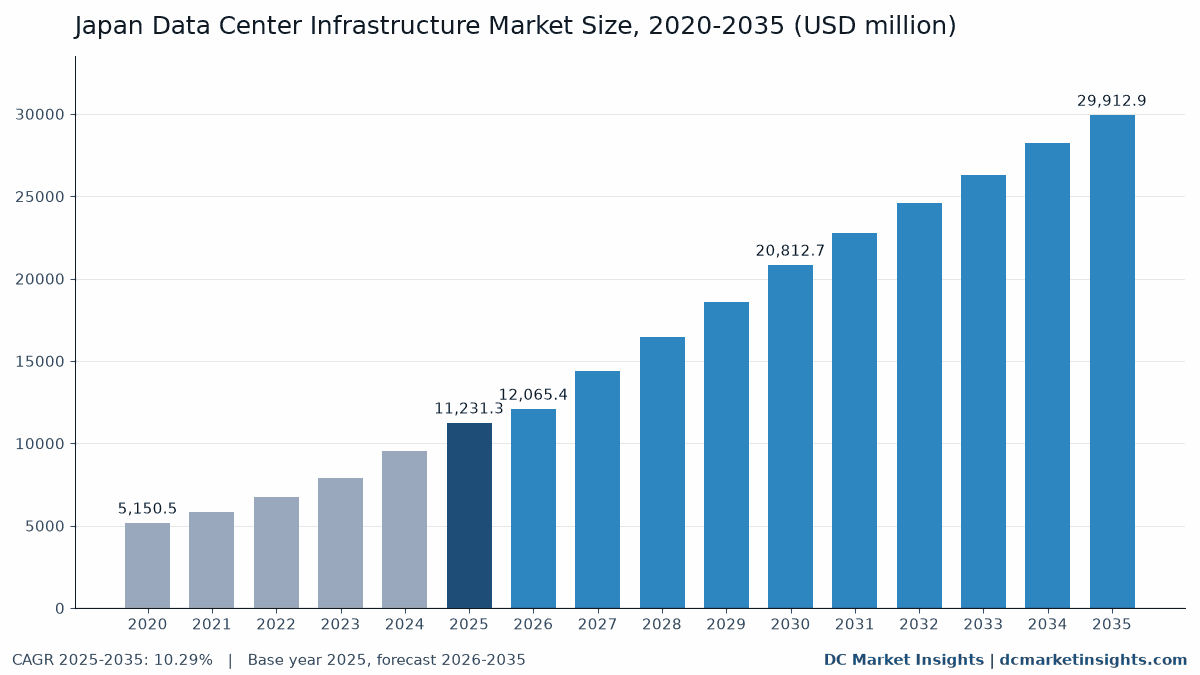
The Japan Data Center Infrastructure market was worth USD 11.23 billion in 2025 and is forecast to reach USD 29.91 billion by 2035, growing at a 10.29% CAGR.
 By Priyanka Mor, Senior Consultant
 Reviewed by Deepti Agrawal
Last updated 18 Nov 2026
Base year 2025 PDF + Excel
What is inside the report
- 01Introduction
- 02Research Methodology
- 03Executive Summary
- 04Market Drivers
- 05Market Trends
- 06Market Challenges
- 07Market Opportunities
- 08Pricing: Capital Cost per MW in Japan
- 09Standards, Regulation, Power and Policy
- 10Japan Data Center Infrastructure Market, By Infrastructure Type
- 20chapters
- 2020-2024Historical period
- 2026-2035Forecast period
- 22Companies profiled
Segmentation
Companies profiled
- Schneider Electric
- Vertiv
- Mitsubishi Electric
- Fuji Electric
- Hitachi
- Toshiba
- Daikin
- ABB
- Eaton
- Delta Electronics
- Kajima
- Obayashi
- Taisei
- Shimizu
- Takenaka
- NTT Facilities
- Fujitsu
- NEC
- Dell Technologies
- HPE
- Cisco
- Lenovo
Full analysis
The Japan Data Center Infrastructure Market is valued at USD 12,065.43 million in 2026 and is projected to reach USD 29,912.86 million by 2035, up from USD 11,231.26 million in 2025, a CAGR of 10.29% from 2025 to 2035 (DC Market Insights estimate). The market is the annual capital spend on data center infrastructure in Japan: electrical, mechanical, civil, structural and architectural, and IT and network, in new builds and in retrofits of live sites. In 2025 Japan added about 291 megawatts (MW) of IT capacity, taking installed IT to about 2,575 MW, and the 2025 receipt is USD 3,749.66 million of facility work (new halls plus retrofits) and USD 7,481.60 million of servers, storage, networking and racks. Rebuilt in November 2026 on a bottom-up capacity model; the earlier edition counted facility spend only partly and left out IT refresh. Retrofit and upgrade spend is the fastest-growing project type at 13.90% a year as AI racks and liquid cooling reach live halls, and Hokkaido is the fastest-growing region at 22.70% a year from USD 281.85 million in 2025.
Key Market Statistics: How Big Is the Japan Data Center Infrastructure Market in 2026?
DC Market Insights values the Japan Data Center Infrastructure Market at USD 12,065.43 million in 2026, 7.4% above 2025, because fewer new MW open in 2026 (246 MW against 291 MW in 2025) while IT refresh on the larger installed base keeps rising. 2026 is an estimate for the current year.
- Market size 2025: USD 11,231.26 million
- Market size 2026: USD 12,065.43 million
- Market size 2030: USD 20,812.71 million
- Market size 2035: USD 29,912.86 million
- CAGR 2025-2035: 10.29% (low case USD 23,527.08 million, high case USD 36,298.64 million in 2035); CAGR 2026-2035: 10.61%; CAGR 2020-2025: 16.87%
- New IT capacity added: 291 MW (2025), 246 MW (2026), 380 MW (2030), 376 MW (2035); installed IT 2,575 MW (2025) and 6,138 MW (2035)
- Largest infrastructure type: IT and Network, 66.6% of 2025 spend (USD 7,481.59 million)
- Facility types in 2025: Electrical 15.0%, Civil, Structural and Architectural 10.0%, Mechanical 8.3%
- Fastest data center type: Edge, 14.07% a year; largest: Colocation, 38.0%
- Leading region: Kanto, 62.1% of 2025 spend; fastest-growing region: Hokkaido, 22.70%
- Capital cost per MW of new IT capacity, 2025: USD 23.81 million (facility USD 11.31 million plus IT and network USD 12.50 million)
Japan Data Center Infrastructure Market Summary: How Much Did Japan Spend on Data Center Infrastructure in 2025?
Japan spent USD 11,231.26 million on data center infrastructure in 2025. The Japan Data Center Infrastructure Market size was valued at USD 5,150.50 million in 2020, reached USD 11,231.26 million in 2025, and is anticipated to reach USD 29,912.86 million by 2035, at a CAGR of 10.29% during the forecast period. Between 2020 and 2025 spend grew 16.87% a year as new IT capacity per year doubled, from 145 MW in 2021 to 291 MW in 2025, and AI servers raised the IT value per MW.
| Report Attribute | Details |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Last Updated | November 2026 |
| Japan Data Center Infrastructure Market Size 2025 | USD 11,231.26 million |
| Japan Data Center Infrastructure Market Size 2026 | USD 12,065.43 million (current-year estimate) |
| Japan Data Center Infrastructure Market CAGR (2025-2035) | 10.29% |
| Japan Data Center Infrastructure Market Size 2035 | USD 29,912.86 million |
| Volume | New IT capacity added per year (MW) |
From 2027 the market climbs again as the large campuses in Inzai, Saitama, Keihanna, Osaka, Tomakomai and Kitakyushu open; DC Market Insights models 380 MW of new IT capacity in 2030 and installed IT of 6,138 MW in 2035. IT and network grows fastest among the infrastructure types at 11.70% a year, because every MW is refreshed about every five years and AI systems carry more value per MW. This report is part of our Asia Pacific Data Center Infrastructure Market coverage.
Key takeaways:
- USD 11,231.26 million in 2025, USD 12,065.43 million in 2026 and USD 29,912.86 million by 2035, a 10.29% CAGR.
- IT and Network is 66.6% of 2025 spend because servers, storage and networking are bought for new halls and refreshed across the installed base.
- Kanto holds 62.1% of 2025 spend; Hokkaido grows fastest at 22.70% on the Tomakomai and Ishikari campuses.
- A new MW of IT capacity costs about USD 23.81 million in 2025, facility plus first IT fit-out; Princeton Digital Group’s TY1 campus is USD 1 billion for 96 MW of IT, about USD 10.4 million per MW.
- Retrofit and upgrade spend rises from USD 5,252.74 million to USD 19,303.37 million as PUE rules and liquid cooling reach live sites.
Market Definition and Scope: What Does the Japan Data Center Infrastructure Market Measure?
Definition. The Japan data center infrastructure market is the annual capital spend on data center infrastructure in Japan, in USD million, valued at first-sale (supplier and contractor) prices and counted in the year the spend is incurred. It covers electrical, mechanical, civil, structural and architectural, and IT and network infrastructure, in new builds and in retrofits of live sites, across hyperscale (self-built), colocation (wholesale and retail), enterprise (in-house) and edge data centers. Land, power bills and other operating costs, operations and maintenance services, software licences, cloud services, and design and consulting fees that are not part of a build contract are excluded.
Measures. Value is capital spend in USD million (JPY spend converted at the annual average rate of each year). Volume is new IT capacity added per year in MW (IT load, not grid or receiving capacity). Spend on a new hall starts before it opens, so value and MW do not move in step in every year. Capital cost per MW is shown on one basis: a new build, facility plus first IT fit-out, per MW of IT capacity.
Coverage. Japan in five regions and sixteen hubs: Kanto (Tokyo, Inzai, Saitama, Yokohama, Rest of Kanto), Kansai (Osaka, Keihanna, Kobe, Rest of Kansai), Hokkaido (Ishikari, Tomakomai, Rest of Hokkaido), Kyushu (Fukuoka, Rest of Kyushu) and Rest of Japan (Chubu; Tohoku, Chugoku, Shikoku and Okinawa). History 2021-2025, base year 2025, forecast 2026-2035.
What is included and excluded
| Item | Status | What it covers |
|---|---|---|
| Electrical | Included | Grid connection and substations on site, MV switchgear, transformers, UPS and batteries, generators, PDUs and busway |
| Mechanical | Included | Cooling plant, CRAH units and fan walls, liquid cooling, pumps and piping, containment, building management system (BMS) |
| Civil, structural and architectural | Included | Site works, shell and core, fit-out, raised floor, fire protection, physical security |
| IT and network | Included | Servers, storage, network equipment, racks, structured cabling |
| New build and retrofit | Included | New halls and campuses; upgrades of live sites (power and cooling retrofits, AI and liquid cooling conversions, IT refresh) |
| Data center types | Included | Hyperscale (self-built), colocation (wholesale and retail), enterprise (in-house), edge |
| Land | Excluded | Land purchase and lease |
| Power bills and other operating costs | Excluded | Electricity, water, staff, rent and other operating costs |
| Operations and maintenance services | Excluded | Facility management and maintenance contracts after handover |
| Software licences | Excluded | Operating systems, DCIM and other software licences |
| Cloud services | Excluded | Cloud, hosting and colocation service revenue |
| Design and consulting fees | Excluded | Design, engineering and consulting fees that are not part of a build contract |
How the segments fit together
Four dimensions (infrastructure type, data center type, project type and tier standard) each cut the full USD 11,231.26 million. The five regions and sixteen hubs cut the same total. New IT capacity in MW is the volume measure; one MW of IT load is the power drawn by servers, not the grid connection or the receiving capacity quoted in many Japanese releases.
How Does This Market Differ from Other Data Center Figures?
Figures for Japanese data centers measure different things, so they cannot be compared with or added to this market’s USD 11,231.26 million in 2025. Rebuilt in November 2026 on a bottom-up capacity model; the earlier edition counted facility spend only partly and left out IT refresh. The table shows what each figure measures.
| Figure | What it measures | How it relates to this market |
|---|---|---|
| Data center services market | Recurring revenue of operators and providers: colocation, hosting, managed and cloud services | A demand-side revenue figure; it pays back infrastructure over many years and is not capital spend |
| Colocation revenue | Rent and power fees paid by tenants to colocation operators | Part of the services market; excluded here. The operator’s build spend on its halls is included |
| Construction-only figures | Building contracts: shell, core, fit-out and often the electrical and mechanical works | A subset of this market: it leaves out IT and network equipment and owner-procured equipment |
| Grid or receiving capacity (MW) | Power the site can draw from the grid, as stated in many Japanese releases | Not the volume of this report, which is IT MW; grid MW is always labelled where quoted |
The Japan Data Center Market report covers the wider data center market; this report counts only the capital spend on infrastructure.
What Is Driving Data Center Infrastructure Spend in Japan?
Three things move the money: hyperscale cloud and AI investment, rising data center power demand, and new capital from developers and funds; together they lift new IT capacity from 291 MW in 2025 to 380 MW in 2030.
Hyperscale cloud and AI: JPY 2.26 trillion from AWS and about USD 10 billion from Microsoft
AWS plans JPY 2.26 trillion in its Tokyo and Osaka regions over 2023-2027, Microsoft announced about USD 10 billion for 2026-2029 in April 2026, and METI approved up to JPY 72.5 billion in 2024 for five domestic GPU cloud plans. Hyperscale data centers grow from USD 3,369.38 million in 2025 to USD 10,469.50 million by 2035, 12.01% a year.
New data center demand of 6.61 GW by FY2035
The OCCTO demand forecast (January 2026) counts new data center peak demand of 0.64 GW in FY2026, 3.28 GW in FY2030 and 6.61 GW in FY2035 (power, not IT load). With a PUE near 1.35 that is a few hundred MW of new IT a year, in line with the 380 MW modelled for 2030.
Developers and funds build AI-ready campuses
Princeton Digital Group launched its TY1 campus in Saitama in April 2025 (USD 1 billion, 96 MW of IT, up to 140 kW per rack), Mitsui bought 50% of a 20 MW Kanagawa data center for JPY 18 billion in March 2025, and Asia Pacific Land and GCI plan a JPY 125 billion, 120 MW campus in Kitakyushu. New build spend reaches USD 10,609.49 million by 2035.
How Is Data Center Infrastructure in Japan Changing?
Japanese halls are moving to AI densities, liquid cooling and prefabricated builds, which lifts the capital cost per MW from USD 23.81 million in 2025 to USD 32.00 million in 2035.
Liquid cooling for 140-150 kW racks
PDG TY1 supports 140 kW per rack with liquid cooling, MC Digital Realty’s NRT14 in Inzai (April 2026) up to 150 kW per rack, and KDDI’s Sakai site runs NVIDIA GB200 NVL72 racks with direct liquid cooling from January 2026. Mechanical spend grows 8.48% a year, faster than electrical (6.88%) and civil (5.36%).
Prefabricated and modular builds to cut build time
NTT Facilities started developing its Hyper Ready Module method in July 2026 to cut permit-to-completion to about two years, Daiwa House sells a modular data center from January 2026, and vendors bring prefabricated power and cooling modules to Japan.
Retrofits of live halls
Energy Conservation Act disclosure from FY2026 and liquid-cooling conversions, such as AirTrunk’s reported additional USD 1 billion for TOK1 in Inzai (October 2026), lift retrofit and upgrade spend 13.90% a year.
What Holds Back Data Center Infrastructure Spend in Japan?
Grid connection and construction capacity hold the market back: new IT capacity dips to 246 MW in 2026, and the low case leaves installed IT at 5,069 MW and the market at USD 23,527.08 million in 2035.
Grid queues: 59 GW of requests in the TEPCO area
TEPCO Power Grid reported data center connection requests of 59.05 GW (506 cases) by August 2024, and contracted power in Inzai-Shiroi was about 30% of original plans and two to three years late. OCCTO notes that data center projects were postponed or redesigned.
Construction cost and labour
The MLIT construction cost deflator rose from 129.0 in FY2024 to 132.4 in FY2025, and the overtime cap for construction workers applies from April 2024, so builds take longer and cost more. Imported IT and equipment priced in US dollars costs more in yen when the yen is weak.
Where Are the New Revenue Opportunities in Japanese Data Center Infrastructure?
The largest new pools are IT and network for AI capacity, USD 22,617.95 million by 2035, and regional clusters in Hokkaido and Kyushu, which together rise from USD 729.43 million in 2025 to USD 3,844.05 million in 2035.
GX strategy areas in Hokkaido and Kyushu
METI named nine data center cluster regions under its GX strategy areas in April 2026, including Ishikari and Tomakomai in Hokkaido, and certified Fukuoka (Kitakyushu, Nogata, Kurate) in September 2026. SoftBank broke ground at Tomakomai in April 2025 (300 MW or more of receiving capacity). Hokkaido grows 22.70% and Kyushu 14.03% a year.
Edge and enterprise refresh
Edge data centers grow 14.07% a year from USD 561.56 million in 2025, and enterprise halls still spend USD 5,982.57 million in 2035, mostly on IT refresh and retrofits.
How Much Does Data Center Infrastructure Cost per MW in Japan?
A new MW of IT capacity in Japan costs about USD 23.81 million in 2025: USD 11.31 million of facility (electrical, mechanical, civil) and USD 12.50 million of first IT and network fit-out (DC Market Insights estimates, land excluded, one basis: new build).
| Capital cost per MW of new IT capacity (USD million) | 2025 | 2030 | 2035 |
|---|---|---|---|
| Electrical | 5.09 | 5.58 | 6.08 |
| Mechanical | 2.83 | 3.35 | 3.91 |
| Civil, Structural and Architectural | 3.39 | 3.47 | 3.51 |
| IT and Network | 12.50 | 16.00 | 18.50 |
| Total new build (facility + IT) | 23.81 | 28.40 | 32.00 |
Public project cost anchors
| Project | Stated cost | Stated capacity and basis | Date and source |
|---|---|---|---|
| Princeton Digital Group TY1 campus, Saitama City | USD 1.0 billion | 96 MW IT: about USD 10.4 million per MW | Apr 2025, PDG release |
| Asia Pacific Land and GCI, Kitakyushu campus | JPY 125 billion | 120 MW power load (60 MW phase 1): JPY 1.04 billion per MW | 2023-2025, Fukuoka Prefecture and APL release |
| GLP Japan data center plan | More than JPY 1.5 trillion | 900 MW power: about JPY 1.67 billion per MW (plan level) | Feb 2022, GLP release |
| Obayashi (MiTASUN), central Tokyo urban data centers | About JPY 100 billion over 10 years | 40 MW class by FY2031: about JPY 2.5 billion per MW incl. buildings | Nov 2024, Obayashi release |
| CapitaLand Investment, first Japan data center, Osaka | More than SGD 900 million incl. freehold land | 50 MW power secured | Feb 2025, CapitaLand release |
| SoftBank Hokkaido Tomakomai AI data center | Up to JPY 30 billion METI subsidy, about half of the first phase | 50 MW receiving capacity, first data hall building | Nov 2023 subsidy; SoftBank release Apr 2025 |
The anchors bracket the facility cost: JPY 1.04 billion per MW of power load in Kitakyushu, about JPY 1.67 billion per MW in GLP’s plan, and about JPY 2.5 billion per MW for Obayashi’s urban Tokyo sites, which include the buildings. Scope differs by project (land, building, equipment).
Which Rules, Power Facts and Policies Shape Data Centers in Japan?
Efficiency rules from the Agency for Natural Resources and Energy, the Watt-Bit collaboration of METI and MIC, GX location policy and grid queues decide where and how Japanese data centers are built. Grid and OCCTO figures are power MW; this report’s volume is IT MW.
| Date | Item | Fact (power MW or IT MW as stated) | Source |
|---|---|---|---|
| Mar 2022 | Energy Conservation Act benchmark | Data center operators: target PUE of 1.4 or lower by FY2030. | ANRE (METI) |
| Sep 2023 | METI regional siting subsidy | JPY 7.1 billion data center regional hub subsidy (FY2021 supplementary budget); half of land, power and telecom costs for sites outside Tokyo and Osaka. | METI |
| 7 Nov 2023 | SoftBank Tomakomai support | METI subsidy of up to JPY 30 billion for SoftBank’s Tomakomai AI data center. | METI; trade press |
| 19 Apr 2024 | GPU cloud subsidies | Up to JPY 72.5 billion for five GPU cloud plans under the Economic Security Promotion Act. | METI |
| 4 Oct 2024 | Digital infrastructure summary 3.0 | METI and MIC: disperse data center siting to Hokkaido and Kyushu, deploy advanced technologies. | MIC |
| FY2024 | MIC dispersion program | JPY 12.0 billion (FY2024 supplementary budget) for regional data center siting; JPY 20.94 billion committed over several years. | MIC |
| 22 Jan 2025 | OCCTO FY2025 forecast | Individually counted data center peak demand 0.47 GW in FY2025 (power MW). | OCCTO |
| Feb 2025 | GX 2040 Vision | Cabinet decision: industrial siting near decarbonised power, Watt-Bit collaboration. | METI |
| 18 Mar 2025 | Watt-Bit council | METI and MIC public-private council on joint planning of power and telecom for data centers. | MIC |
| 21 Mar 2025 | TEPCO Power Grid grid queue | Data center requests 59.05 GW (506 cases) by August 2024; Inzai-Shiroi contracted power about 30% of plans, 2-3 years late (power MW). | TEPCO PG via MIC |
| 12 Jun 2025 | Watt-Bit summary 1.0 | Site where the grid has headroom; rules against speculative capacity reservation; planned grid and telecom build-out for clusters. | METI |
| Aug 2025 | GX strategy area system | Data center cluster type: GW-class cluster within about 10 years, with capital aid and advance grid build-out. | METI |
| 21 Jan 2026 | OCCTO FY2026 forecast | New data center peak demand 0.64 GW (FY2026), 3.28 GW (FY2030), 6.61 GW (FY2035) (power MW). | OCCTO |
| Apr 2026 | Energy Conservation Act measures | New data centers from FY2029 must reach PUE 1.3; data center items in periodic reports from FY2026 with public disclosure. | ANRE (METI) |
| 24 Apr 2026 | GX strategy areas named | Nine data center cluster regions, including Hokkaido (Ishikari, Tomakomai), Tochigi, Ibaraki and Fukuoka. | METI |
| May 2026 | JDCC coexistence guideline | Dialogue with residents on heat, noise, fuel, water and generator exhaust; used in MIC subsidy scoring from FY2026. | Cabinet Secretariat material |
| 11 Sep 2026 | First GX area certified | Fukuoka (Kitakyushu, Nogata, Kurate) certified as a data center cluster GX strategy area. | Fukuoka Prefecture |
Which Segment Leads the Japan Data Center Infrastructure Market, and Which Grows Fastest?
IT and Network leads with 66.6% of 2025 spend, colocation leads data center types with 38.0%, new build leads project types with 53.2%, Tier III takes 70.0%, and edge grows fastest at 14.07% a year. Every split adds to USD 11,231.26 million in 2025 and USD 29,912.86 million in 2035.
By Infrastructure Type
IT and Network leads because servers, storage and networking are bought for every new MW and refreshed across the base. Among facility types, Electrical is largest (USD 1,687.35 million) and Mechanical grows fastest (8.48%) with liquid cooling.
| Infrastructure Type | 2025 (USD million) | Share 2025 | 2035 (USD million) | CAGR 2025-2035 |
|---|---|---|---|---|
| IT and Network | 7,481.59 | 66.6% | 22,617.95 | 11.70% |
| Electrical | 1,687.35 | 15.0% | 3,282.71 | 6.88% |
| Civil, Structural and Architectural | 1,124.90 | 10.0% | 1,896.68 | 5.36% |
| Mechanical | 937.42 | 8.3% | 2,115.52 | 8.48% |
| Total | 11,231.26 | 100.0% | 29,912.86 | 10.29% |
Electrical: sub-items
| Electrical sub-item | 2025 (USD million) | 2035 (USD million) | CAGR 2025-2035 |
|---|---|---|---|
| Grid connection and on-site substations | 236.23 | 526.29 | 8.34% |
| MV switchgear and transformers | 371.22 | 723.64 | 6.90% |
| UPS and batteries | 472.46 | 888.11 | 6.51% |
| Generators and fuel systems | 354.34 | 624.96 | 5.84% |
| PDUs, busway and LV distribution | 253.10 | 519.71 | 7.46% |
| Electrical, total | 1,687.35 | 3,282.71 | 6.88% |
Mechanical: sub-items
| Mechanical sub-item | 2025 (USD million) | 2035 (USD million) | CAGR 2025-2035 |
|---|---|---|---|
| Cooling plant (chillers, cooling towers, heat rejection) | 299.98 | 528.88 | 5.83% |
| CRAH units and fan walls | 243.73 | 359.64 | 3.97% |
| Liquid cooling (CDUs, rear-door, direct-to-chip) | 74.99 | 550.03 | 22.05% |
| Pumps and piping | 178.11 | 401.95 | 8.48% |
| Containment and BMS | 140.61 | 275.02 | 6.94% |
| Mechanical, total | 937.42 | 2,115.52 | 8.48% |
Civil, Structural and Architectural: sub-items
| Civil, Structural and Architectural sub-item | 2025 (USD million) | 2035 (USD million) | CAGR 2025-2035 |
|---|---|---|---|
| Site works and foundations (incl. seismic isolation) | 179.98 | 303.47 | 5.36% |
| Shell and core (structure and envelope) | 539.95 | 891.44 | 5.14% |
| Fit-out (raised floor, ceilings, white space) | 157.49 | 246.57 | 4.58% |
| Fire protection | 146.24 | 265.53 | 6.15% |
| Physical security | 101.24 | 189.67 | 6.48% |
| Civil, Structural and Architectural, total | 1,124.90 | 1,896.68 | 5.36% |
IT and Network: sub-items
| IT and Network sub-item | 2025 (USD million) | 2035 (USD million) | CAGR 2025-2035 |
|---|---|---|---|
| Servers (incl. AI accelerated) | 4,937.85 | 16,511.11 | 12.83% |
| Storage | 1,122.24 | 2,714.15 | 9.23% |
| Network equipment | 1,047.42 | 2,487.97 | 9.04% |
| Racks and structured cabling | 374.08 | 904.72 | 9.23% |
| IT and Network, total | 7,481.59 | 22,617.95 | 11.70% |
By Data Center Type
Colocation (wholesale and retail) is the largest type, hyperscale (self-built) grows to USD 10,469.50 million, enterprise (in-house) halls grow slowest at 7.03%, and edge grows fastest.
| Data Center Type | 2025 (USD million) | Share 2025 | 2035 (USD million) | CAGR 2025-2035 |
|---|---|---|---|---|
| Colocation | 4,267.88 | 38.0% | 11,366.89 | 10.29% |
| Hyperscale | 3,369.38 | 30.0% | 10,469.50 | 12.01% |
| Enterprise | 3,032.44 | 27.0% | 5,982.57 | 7.03% |
| Edge | 561.56 | 5.0% | 2,093.90 | 14.07% |
| Total | 11,231.26 | 100.0% | 29,912.86 | 10.29% |
By Project Type
New Build covers new halls and campuses (facility plus first IT fit-out); Retrofit and Upgrade covers power and cooling retrofits, AI and liquid cooling conversions and IT refresh in live sites; it is larger than new build in most years from 2026 and close to twice its size by 2035.
| Project Type | 2025 (USD million) | Share 2025 | 2035 (USD million) | CAGR 2025-2035 |
|---|---|---|---|---|
| New Build | 5,978.52 | 53.2% | 10,609.49 | 5.90% |
| Retrofit and Upgrade | 5,252.74 | 46.8% | 19,303.37 | 13.90% |
| Total | 11,231.26 | 100.0% | 29,912.86 | 10.29% |
By Tier Standard
Tier III takes most of the spend; Tier IV grows faster at 12.53% for finance and mission-critical sites; Tier I and II covers small enterprise and edge rooms.
| Tier Standard | 2025 (USD million) | Share 2025 | 2035 (USD million) | CAGR 2025-2035 |
|---|---|---|---|---|
| Tier III | 7,861.88 | 70.0% | 20,490.31 | 10.05% |
| Tier IV | 2,021.63 | 18.0% | 6,580.83 | 12.53% |
| Tier I and II | 1,347.75 | 12.0% | 2,841.72 | 7.75% |
| Total | 11,231.26 | 100.0% | 29,912.86 | 10.29% |
Delivery models
The client buys a build in one of several ways. The delivery model is not a separate segment: the spend of every model sits inside the four infrastructure types.
| Delivery model | How it works | Use in Japan | Dated examples |
|---|---|---|---|
| Design-build by a general contractor | One contractor designs and builds under one contract, often including MEP works | Most common for Japanese owners and many foreign developers | Taisei designed and built ZED Ishikari (opened 1 Oct 2024); Obayashi offers full turnkey design-build |
| Design-bid-build with a main contractor | A separate designer; the general contractor builds to the design | Large campuses of foreign developers | Kajima built TY1 core and shell in Saitama (design Nikken Sekkei, completed Mar 2024); HASEKO is main contractor for DayOne Fuchu phase 1 (Aug 2025) |
| EPC and EPCC | Engineering, procurement, construction and commissioning by one firm, often power-led | Power-heavy and AI sites | Toshiba Plant Systems data center infrastructure office (Jul 2025); Mitsubishi Heavy Industries one-stop power and cooling (Oct 2023) |
| Turnkey and modular / prefabricated | Factory-built power modules, pods or containers delivered and connected on site | Fast capacity, edge and AI pods | Delta power train units in Hokkaido (Dec 2024); Daiwa House Module DPDC (Jan 2026); NTT Facilities Hyper Ready Module (Jul 2026) |
| Construction management and owner-led | The owner manages trade packages and procures equipment directly | Hyperscalers and experienced operators | Owner-procured UPS, cooling and IT; NTT GDC and TEPCO PG joint venture for Inzai-Shiroi (Dec 2023) |
| Conversion and retrofit | Existing buildings or plants converted, or live halls upgraded | Urban Tokyo and brownfield plants | Obayashi MiTASUN office conversions (Nov 2024); KDDI Sakai reused power and cooling of a former LCD plant (Jan 2026) |
DC Exclusive: Japan Pipeline Teaser and Region by Infrastructure Type Matrix
Our Data Center Map for Japan tracks 74 data centers run by 20 operators (3 November 2026 update): 54 operational, 9 under construction and 11 planned, with 697 MW stated at operational sites, 437 MW under construction and 622 MW planned. The table shows 10 projects with a stated capacity, at most two per operator, each listed once.
| Operator | Campus | Prefecture | MW (basis) | Stage | Date |
|---|---|---|---|---|---|
| AirTrunk | TOK1 | Chiba (Inzai) | 300 MW (total) | Operational | 2021 |
| AirTrunk | TOK2 | Tokyo | 110 MW (total) | Operational | 2024 |
| STACK Infrastructure | TKY01 Inzai | Chiba (Inzai) | 36 MW (total) | Operational | 2024 |
| Internet Initiative Japan (IIJ) | Shiroi campus, phase 2 building | Chiba (Shiroi) | 10 MW (total) | Operational | 2023 |
| NTT DATA | Keihanna OSK11 | Kyoto | 30 MW (IT) | Operational | 2026 |
| ST Telemedia Global Data Centres | Tokyo campus (TYO1 and TYO2) | Chiba (Inzai) | 70.8 MW (IT) | Under construction | Pipeline |
| Princeton Digital Group | TY1 phase 1 | Saitama | 48 MW (as stated) | Under construction | Pipeline |
| Colt DCS | Tokyo Inzai 4 | Chiba (Inzai) | 20 MW (IT) | Under construction | Pipeline |
| EdgeConneX | ITM01 Kagoya Tatara campus | Kyoto (Kyotanabe) | 200 MW (total) | Under construction | Pipeline |
| Vantage Data Centers | Osaka (KIX1) campus | Osaka (Ibaraki) | 68 MW (IT) | Under construction | Pipeline |
MW basis: IT where the source states IT load, otherwise total; ‘as stated’ where the source does not say. Date: year opened; Pipeline: not yet open.
The region by infrastructure type matrix applies the model’s split to each region (2025, USD million; 20 inputs).
| Region | Electrical | Mechanical | Civil, Structural and Architectural | IT and Network | Total |
|---|---|---|---|---|---|
| Kanto | 1,048.46 | 582.48 | 698.97 | 4,648.76 | 6,978.67 |
| Kansai | 408.20 | 226.78 | 272.13 | 1,809.95 | 2,717.06 |
| Hokkaido | 42.34 | 23.52 | 28.23 | 187.76 | 281.85 |
| Kyushu | 67.24 | 37.36 | 44.83 | 298.15 | 447.58 |
| Rest of Japan | 121.11 | 67.28 | 80.74 | 536.97 | 806.10 |
| Total | 1,687.35 | 937.42 | 1,124.90 | 7,481.59 | 11,231.26 |
Which Region Leads Japan’s Data Center Infrastructure Spend, and Which Grows Fastest?
Kanto leads with USD 6,978.67 million (62.1%) in 2025, and Hokkaido grows fastest at 22.70% a year to USD 2,179.77 million by 2035.
| Region | 2025 (USD million) | Share 2025 | 2035 (USD million) | CAGR 2025-2035 |
|---|---|---|---|---|
| Kanto | 6,978.67 | 62.1% | 15,818.02 | 8.53% |
| Kansai | 2,717.06 | 24.2% | 8,409.77 | 11.96% |
| Hokkaido | 281.85 | 2.5% | 2,179.77 | 22.70% |
| Kyushu | 447.58 | 4.0% | 1,664.28 | 14.03% |
| Rest of Japan | 806.10 | 7.2% | 1,841.02 | 8.61% |
| Total | 11,231.26 | 100.0% | 29,912.86 | 10.29% |
Kanto
Kanto is the core of the market: Tokyo for latency-sensitive and urban sites, Inzai and Shiroi in Chiba for hyperscale campuses (AirTrunk TOK1, Colt Inzai, STACK TKY01, MC Digital Realty NRT, Google Inzai), Saitama for new AI-ready campuses (PDG TY1) and Yokohama and Kanagawa for enterprise and hyperscale sites. Grid connection limits in Inzai-Shiroi slow the region’s growth, so its share of spend falls over the forecast while it stays the largest region. Kanto spends USD 6,978.67 million in 2025 and USD 15,818.02 million by 2035.
Kansai
Kansai is the second hub and Japan’s main disaster recovery location: Osaka and Minoh (Equinix, Digital Realty KIX, CapitaLand), Keihanna (NTT DATA OSK11, Colt Keihanna, EdgeConneX Kyotanabe), Sakai (KDDI and SoftBank AI sites on the former Sharp plant) and Kobe. Kansai spends USD 2,717.06 million in 2025 and USD 8,409.77 million by 2035.
Hokkaido
Hokkaido grows from a small base on clean power and policy support: SoftBank’s Tomakomai AI data center (300 MW+ receiving capacity, opening FY2026), Sakura Internet and ZED in Ishikari, and both sites named GX strategy areas. Hokkaido spends USD 281.85 million in 2025 and USD 2,179.77 million by 2035.
Kyushu
Kyushu grows on clean power, semiconductor clusters and policy: the Kitakyushu campus of Asia Pacific Land and GCI (120 MW power, phase 1 in 2027) and Fukuoka’s GX strategy area certification (September 2026). Kyushu spends USD 447.58 million in 2025 and USD 1,664.28 million by 2035.
Rest of Japan
Rest of Japan covers Chubu (Nagoya and Hokuriku) and the Tohoku, Chugoku, Shikoku and Okinawa regions: mostly enterprise, edge and regional data centers today, with GX area candidates in Akita, Miyagi, Toyama and Kagawa. Rest of Japan spends USD 806.10 million in 2025 and USD 1,841.02 million by 2035.
Which Japanese Hubs Lead Data Center Infrastructure Spend?
Tokyo leads the sixteen hubs with USD 2,593.04 million in 2025 (23.1%), Inzai follows with USD 2,480.30 million and overtakes Tokyo by 2035, and Tomakomai grows fastest at 38.58% a year as SoftBank’s AI data center opens.
| Rank | Hub | Region | 2025 (USD million) | 2035 (USD million) | CAGR 2025-2035 |
|---|---|---|---|---|---|
| 1 | Tokyo | Kanto | 2,593.04 | 4,860.29 | 6.48% |
| 2 | Inzai | Kanto | 2,480.30 | 5,302.12 | 7.89% |
| 3 | Osaka | Kansai | 1,691.12 | 4,565.72 | 10.44% |
| 4 | Saitama | Kanto | 676.45 | 1,914.66 | 10.96% |
| 5 | Yokohama | Kanto | 665.17 | 1,531.73 | 8.70% |
| 6 | Rest of Kanto | Kanto | 563.71 | 2,209.22 | 14.64% |
| 7 | Chubu | Rest of Japan | 462.24 | 1,075.16 | 8.81% |
| 8 | Keihanna | Kansai | 450.96 | 2,061.94 | 16.42% |
| 9 | Tohoku, Chugoku, Shikoku and Okinawa | Rest of Japan | 343.86 | 765.86 | 8.34% |
| 10 | Rest of Kansai | Kansai | 338.22 | 1,060.43 | 12.11% |
| 11 | Fukuoka | Kyushu | 284.11 | 1,016.24 | 13.59% |
| 12 | Kobe | Kansai | 236.76 | 721.68 | 11.79% |
| 13 | Ishikari | Hokkaido | 169.11 | 1,001.52 | 19.47% |
| 14 | Rest of Kyushu | Kyushu | 163.47 | 648.04 | 14.77% |
| 15 | Rest of Hokkaido | Hokkaido | 78.92 | 294.56 | 14.08% |
| 16 | Tomakomai | Hokkaido | 33.82 | 883.69 | 38.58% |
How Could the 2035 Japan Data Center Infrastructure Forecast Change?
The 2035 market ranges from USD 23,527.08 million to USD 36,298.64 million depending on how fast new IT capacity is connected, around a base case of USD 29,912.86 million.
| Scenario | Installed IT MW 2035 | Market 2035 (USD million) | Assumption |
|---|---|---|---|
| Low | 5,069 | 23,527.08 | New IT capacity after 2025 is 30% below the base case: grid queues and labour limits delay campuses |
| Base | 6,138 | 29,912.86 | DC Market Insights Global Capacity model path; dated campuses open on announced timelines with some delay |
| High | 7,207 | 36,298.64 | New IT capacity 30% above base: GX clusters, Tomakomai and Kitakyushu scale up and AI demand stays strong |
Competitive Insights: Who Supplies Data Center Infrastructure in Japan?
Three groups sell into this market: electrical and mechanical vendors, general contractors that design and build the facilities, and IT and network vendors. Only companies with a dated Japan data center role are listed; KIO Networks, Acer, Inspur, Oracle, IBM and Huawei are not, because no dated Japan data center infrastructure supply was found.
Companies profiled
- Schneider Electric
- Vertiv
- Mitsubishi Electric
- Fuji Electric
- Hitachi
- Toshiba
- Daikin
- ABB
- Eaton
- Delta Electronics
- Kajima
- Obayashi
- Taisei
- Shimizu
- Takenaka
- NTT Facilities
- Fujitsu
- NEC
- Dell Technologies
- HPE
- Cisco
- Lenovo
Electrical and mechanical vendors: Schneider Electric, Vertiv, Mitsubishi Electric, Fuji Electric, Hitachi, Toshiba, Daikin, ABB, Eaton, Delta Electronics; General contractors: Kajima, Obayashi, Taisei, Shimizu, Takenaka, NTT Facilities; IT and network vendors: Fujitsu, NEC, Dell Technologies, HPE, Cisco, Lenovo.
Schneider Electric has been in Japan since 1962 and launched its liquid cooling line there in October 2025 with CDUs up to 1.7 MW; Mitsubishi Electric targets JPY 400 billion of data center revenue by FY2030; Fuji Electric supplied large UPS systems for IIJ’s Shiroi campus; Vertiv set up a Japan entity in February 2025. Kajima built the core and shell of PDG TY1 in Saitama (2024), Taisei designed and built ZED Ishikari (2024), Obayashi develops its own urban data centers through MiTASUN, and NTT Facilities is developing a prefabricated method for hyperscale halls. HPE supplied the GB200 NVL72 racks for KDDI Sakai, and Dell signed an MOU in October 2026 to supply rack-scale AI systems for a 400 MW site at JERA’s Chiba power station.
Buyers: operators and hyperscale cloud providers
AirTrunk, NTT DATA, MC Digital Realty, Colt DCS, Equinix, Princeton Digital Group, KDDI, SoftBank and Sakura Internet build and run the halls; AWS, Microsoft, Google and Oracle buy and lease capacity for their cloud regions. They are customers of the suppliers above, not suppliers, and are not counted twice.
What Changed in Japan’s Data Center Infrastructure Market in 2025 and 2026?
- In February 2025, Schneider Electric completed the purchase of 75% of Motivair, a liquid cooling maker, agreed for USD 850 million (Source: Schneider Electric).
- In April 2025, Princeton Digital Group launched its USD 1 billion, 96 MW TY1 campus in Saitama (Source: Princeton Digital Group).
- In April 2025, SoftBank broke ground on its Tomakomai AI data center in Hokkaido (Source: SoftBank).
- In January 2026, KDDI started its Osaka Sakai AI data center with GB200 NVL72 racks and direct liquid cooling built with HPE (Source: HPE).
- In April 2026, NTT DATA opened Keihanna OSK11 with 30 MW of IT capacity (Source: NTT DATA).
- In September 2026, Fukuoka Prefecture’s Kitakyushu area was certified as a data center cluster GX strategy area (Source: Fukuoka Prefecture).
- In October 2026, JERA, Dell Technologies and RHAELM signed an MOU for a 400 MW AI data center at JERA’s Chiba power station (Source: DCD).
How Did DC Market Insights Build the Japan Data Center Infrastructure Market Model (Methodology)?
DC Market Insights built the Japan Data Center Infrastructure Market bottom-up from Japan’s installed IT capacity in its Global Capacity model: 2,283.8 MW at the end of 2024 and 2,575.2 MW at the end of 2025 (291 MW added), and 6,138.0 MW in 2035. Spend = facility build on new IT MW (USD 11.30 million per MW in 2025, half spent in the year before opening) + facility retrofit on the installed base (USD 0.30 million per MW a year) + IT and network: first fit-out of new live MW (USD 12.50 million per MW, 80% utilisation) and a five-year refresh of the live base. For 2025 that is USD 3,064.52 million + USD 685.14 million + USD 2,914.00 million + USD 4,567.60 million = USD 11,231.26 million.
- Check 1 (project cost): PDG TY1 at about USD 10.4 million per MW of IT, against the model’s USD 11.30 million facility cost per MW.
- Check 2 (power): OCCTO’s new data center demand of 3.28 GW in FY2030 divided by a PUE near 1.35 gives about 2.4 GW of new IT load, against 1,629 MW added between 2025 and 2030 in the model.
- Check 3 (split): IT and network is 66.6% of 2025 spend; a separate bottom-up estimate from company investment plans gave about 64%.
Rebuilt in November 2026 on a bottom-up capacity model; the earlier edition counted facility spend only partly and left out IT refresh. Every split adds to the total in every year. See our research methodology and the global Data Center Infrastructure Market report for the capacity method.
Table of contents
- 01Introduction
- 1.1Market Definition and Scope
- 1.2What Is Included and Excluded
- 1.3How This Market Differs from Other Data Center Figures
- 1.4Historical Period 2020-2024, Base Year 2025 and Forecast Period 2026-2035
- 1.5Report Attributes
- 02Research Methodology
- 2.1Installed and New IT Capacity (Global Capacity Model)
- 2.2Facility Build, Retrofit and IT Spend per MW
- 2.3Region and Hub Allocation
- 2.4Bound Checks
- 03Executive Summary
- 3.1Market Snapshot, 2025, 2026 and 2035
- 3.2Key Market Statistics
- 3.3Key Takeaways
- 04Market Drivers
- 4.1Hyperscale Cloud and AI Investment
- 4.2New Data Center Power Demand to FY2035
- 4.3Developers and Funds Build AI-Ready Campuses
- 05Market Trends
- 5.1Liquid Cooling for 140-150 kW Racks
- 5.2Prefabricated and Modular Builds
- 5.3Retrofits of Live Halls
- 06Market Challenges
- 6.1Grid Connection Queues
- 6.2Construction Cost and Labour
- 07Market Opportunities
- 7.1GX Strategy Areas in Hokkaido and Kyushu
- 7.2Edge and Enterprise Refresh
- 08Pricing: Capital Cost per MW in Japan
- 8.1Capital Cost per MW by Infrastructure Type, 2025, 2030 and 2035
- 8.2Public Project Cost Anchors
- 09Standards, Regulation, Power and Policy
- 9.1Energy Conservation Act and PUE Rules
- 9.2Watt-Bit Collaboration
- 9.3GX 2040 Vision and GX Strategy Areas
- 9.4Grid Queues and OCCTO Demand Forecasts
- 9.5Regional Siting Subsidies
- 10Japan Data Center Infrastructure Market, By Infrastructure Type
- 10.1Electrical (with sub-items)
- 10.2Mechanical (with sub-items)
- 10.3Civil, Structural and Architectural (with sub-items)
- 10.4IT and Network (with sub-items)
- 11Japan Data Center Infrastructure Market, By Data Center Type
- 11.1Hyperscale
- 11.2Colocation
- 11.3Enterprise
- 11.4Edge
- 12Japan Data Center Infrastructure Market, By Project Type
- 12.1New Build
- 12.2Retrofit and Upgrade
- 13Japan Data Center Infrastructure Market, By Tier Standard
- 13.1Tier I and II
- 13.2Tier III
- 13.3Tier IV
- 14Delivery Models
- 14.1Design-build by a general contractor
- 14.2Design-bid-build with a main contractor
- 14.3EPC and EPCC
- 14.4Turnkey and modular / prefabricated
- 14.5Construction management and owner-led
- 14.6Conversion and retrofit
- 15DC Exclusive
- 15.1Japan Pipeline Teaser
- 15.2Region by Infrastructure Type Matrix, 2025
- 16Japan Data Center Infrastructure Market, By Region
- 16.1Kanto
- 16.2Kansai
- 16.3Hokkaido
- 16.4Kyushu
- 16.5Rest of Japan
- 17Japan Data Center Infrastructure Market, By Hub
- 17.1Tokyo
- 17.2Inzai
- 17.3Osaka
- 17.4Saitama
- 17.5Yokohama
- 17.6Rest of Kanto
- 17.7Chubu
- 17.8Keihanna
- 17.9Tohoku, Chugoku, Shikoku and Okinawa
- 17.10Rest of Kansai
- 17.11Fukuoka
- 17.12Kobe
- 17.13Ishikari
- 17.14Rest of Kyushu
- 17.15Rest of Hokkaido
- 17.16Tomakomai
- 18Forecast Scenarios
- 18.1Low Case
- 18.2Base Case
- 18.3High Case
- 19Competitive Insights and Company Profiles
- 19.1Schneider Electric
- 19.2Vertiv
- 19.3Mitsubishi Electric
- 19.4Fuji Electric
- 19.5Hitachi
- 19.6Toshiba
- 19.7Daikin
- 19.8ABB
- 19.9Eaton
- 19.10Delta Electronics
- 19.11Kajima
- 19.12Obayashi
- 19.13Taisei
- 19.14Shimizu
- 19.15Takenaka
- 19.16NTT Facilities
- 19.17Fujitsu
- 19.18NEC
- 19.19Dell Technologies
- 19.20HPE
- 19.21Cisco
- 19.22Lenovo
- 19.23Buyers: Operators and Hyperscale Cloud Providers
- 20Recent Developments, 2025-2026
- 20.1Dated Developments
- Fig. 1Japan Data Center Infrastructure Market Size, 2020-2035 (USD Million)
- Table 1Report Attributes
- Table 2Market Definition: What Is Included and Excluded
- Table 3How This Market Differs from Other Data Center Figures
- Table 4Capital Cost per MW of New IT Capacity, 2025, 2030 and 2035
- Table 5Public Project Cost Anchors
- Table 6Power and Policy: Dated Rules and Facts
- Table 7Market by Infrastructure Type, 2025 and 2035
- Table 8Electrical Sub-items, 2025 and 2035
- Table 9Mechanical Sub-items, 2025 and 2035
- Table 10Civil, Structural and Architectural Sub-items, 2025 and 2035
- Table 11IT and Network Sub-items, 2025 and 2035
- Table 12Market by Data Center Type, 2025 and 2035
- Table 13Market by Project Type, 2025 and 2035
- Table 14Market by Tier Standard, 2025 and 2035
- Table 15Delivery Models for Data Center Builds in Japan
- Table 16Japan Pipeline Teaser
- Table 17Region by Infrastructure Type Matrix, 2025
- Table 18Market by Region, 2025 and 2035
- Table 19Market by Hub, 2025 and 2035
- Table 20Forecast Scenarios, 2035
About this report
Written by Priyanka Mor and reviewed by Deepti Agrawal, Senior Editor, Research. Figures are built top-down and bottom-up and reconciled before publication, with 2025 as the base year.
Read our methodologyHow we built this
- Historical period2020-2024
- Base year2025
- Forecast period2026-2035
- Sizing approachTop-down + bottom-up
Need more than the report?
Advisory on this market
Due diligence, site selection and market entry work, by the analysts who wrote this report.
See consulting servicesFrequently asked questions
USD 12,065.43 million in 2026, up from USD 11,231.26 million in 2025, according to DC Market Insights. The market reaches USD 29,912.86 million by 2035.
USD 29,912.86 million by 2035, a CAGR of 10.29% from 2025 (10.61% from 2026), as installed IT capacity rises from 2,575 MW to 6,138 MW.
Annual capital spend on electrical, mechanical, civil, structural and architectural, and IT and network infrastructure in Japan, in new builds and retrofits, across hyperscale, colocation, enterprise and edge data centers. Land, operating costs, O&M services, software, cloud services and stand-alone design fees are excluded.
USD 11,231.26 million in 2025 because the report was rebuilt in November 2026 on a bottom-up capacity model; the earlier edition counted facility spend only partly and left out IT refresh.
IT and Network, 66.6% of 2025 spend (USD 7,481.59 million). Among facility types, Electrical is largest at 15.0%.
Kanto, USD 6,978.67 million or 62.1% of 2025 spend, led by Tokyo and Inzai. Hokkaido grows fastest at 22.70% a year.
About USD 23.81 million per MW of new IT capacity in 2025: USD 11.31 million of facility and USD 12.50 million of IT and network (DC Market Insights estimate).
Schneider Electric, Mitsubishi Electric, Fuji Electric, Hitachi and Vertiv in power and cooling; Kajima, Obayashi, Taisei, Shimizu and Takenaka as builders; Fujitsu, NEC, Dell Technologies and HPE in IT and network.
The Energy Conservation Act sets a PUE 1.4 benchmark by FY2030 and PUE 1.3 for data centers built from FY2029; Watt-Bit and GX strategy areas steer new sites to regions with grid headroom.
Get this report
How do I get the full report?
Request a quote; we reply by email within one business day.
How and when will I receive the report?
By email, within 24-48 business hours of payment.
How can I pay?
Once you accept the quote, we email you a secure payment link.
Can I see a sample first?
Yes. Request a free sample and we will email it to you.
Can the report be tailored to my needs?
Yes. We can add countries, segments or data cuts. Talk to an analyst about the scope you need.
Can I get an invoice or pay against a purchase order?
Write to sales@dcmarketinsights.com and our team will help.