

Key takeaways
- Four new data centre campuses totalling 2,795 MW were proposed in the UK and Spain between 18 and 23 October: Era4’s 1 GW “The Mill” in Newport, the 1 GW Longmarsh scheme in Norfolk, O-Green’s 570 MW in Zaragoza and Krolmap’s 225 MW off-grid site in Belchite (Era4, Longmarsh Green Energy, Heraldo de Aragón).
- Only 90 MW of those 2,795 MW, about 3%, has grid access stated for 2029 or earlier: O-Green’s first phase. Longmarsh’s grid date is 2031 and Krolmap plans to run without the grid (our calculation from developer and press figures).
- Microsoft pulled out of Nscale’s Loughton site, billed as the UK’s largest sovereign AI data centre, after the local network operator said it would not be powered in time; grid officials reportedly said the 2030s (City AM, Bloomberg, 19 Oct 2026).
- Power is now what buyers pay for: KDDI and Telehouse closed a deal of more than £220 million on 29 October for an East India Dock estate with 65 MVA secured, about £3.4 million per MVA (Telehouse; our calculation).
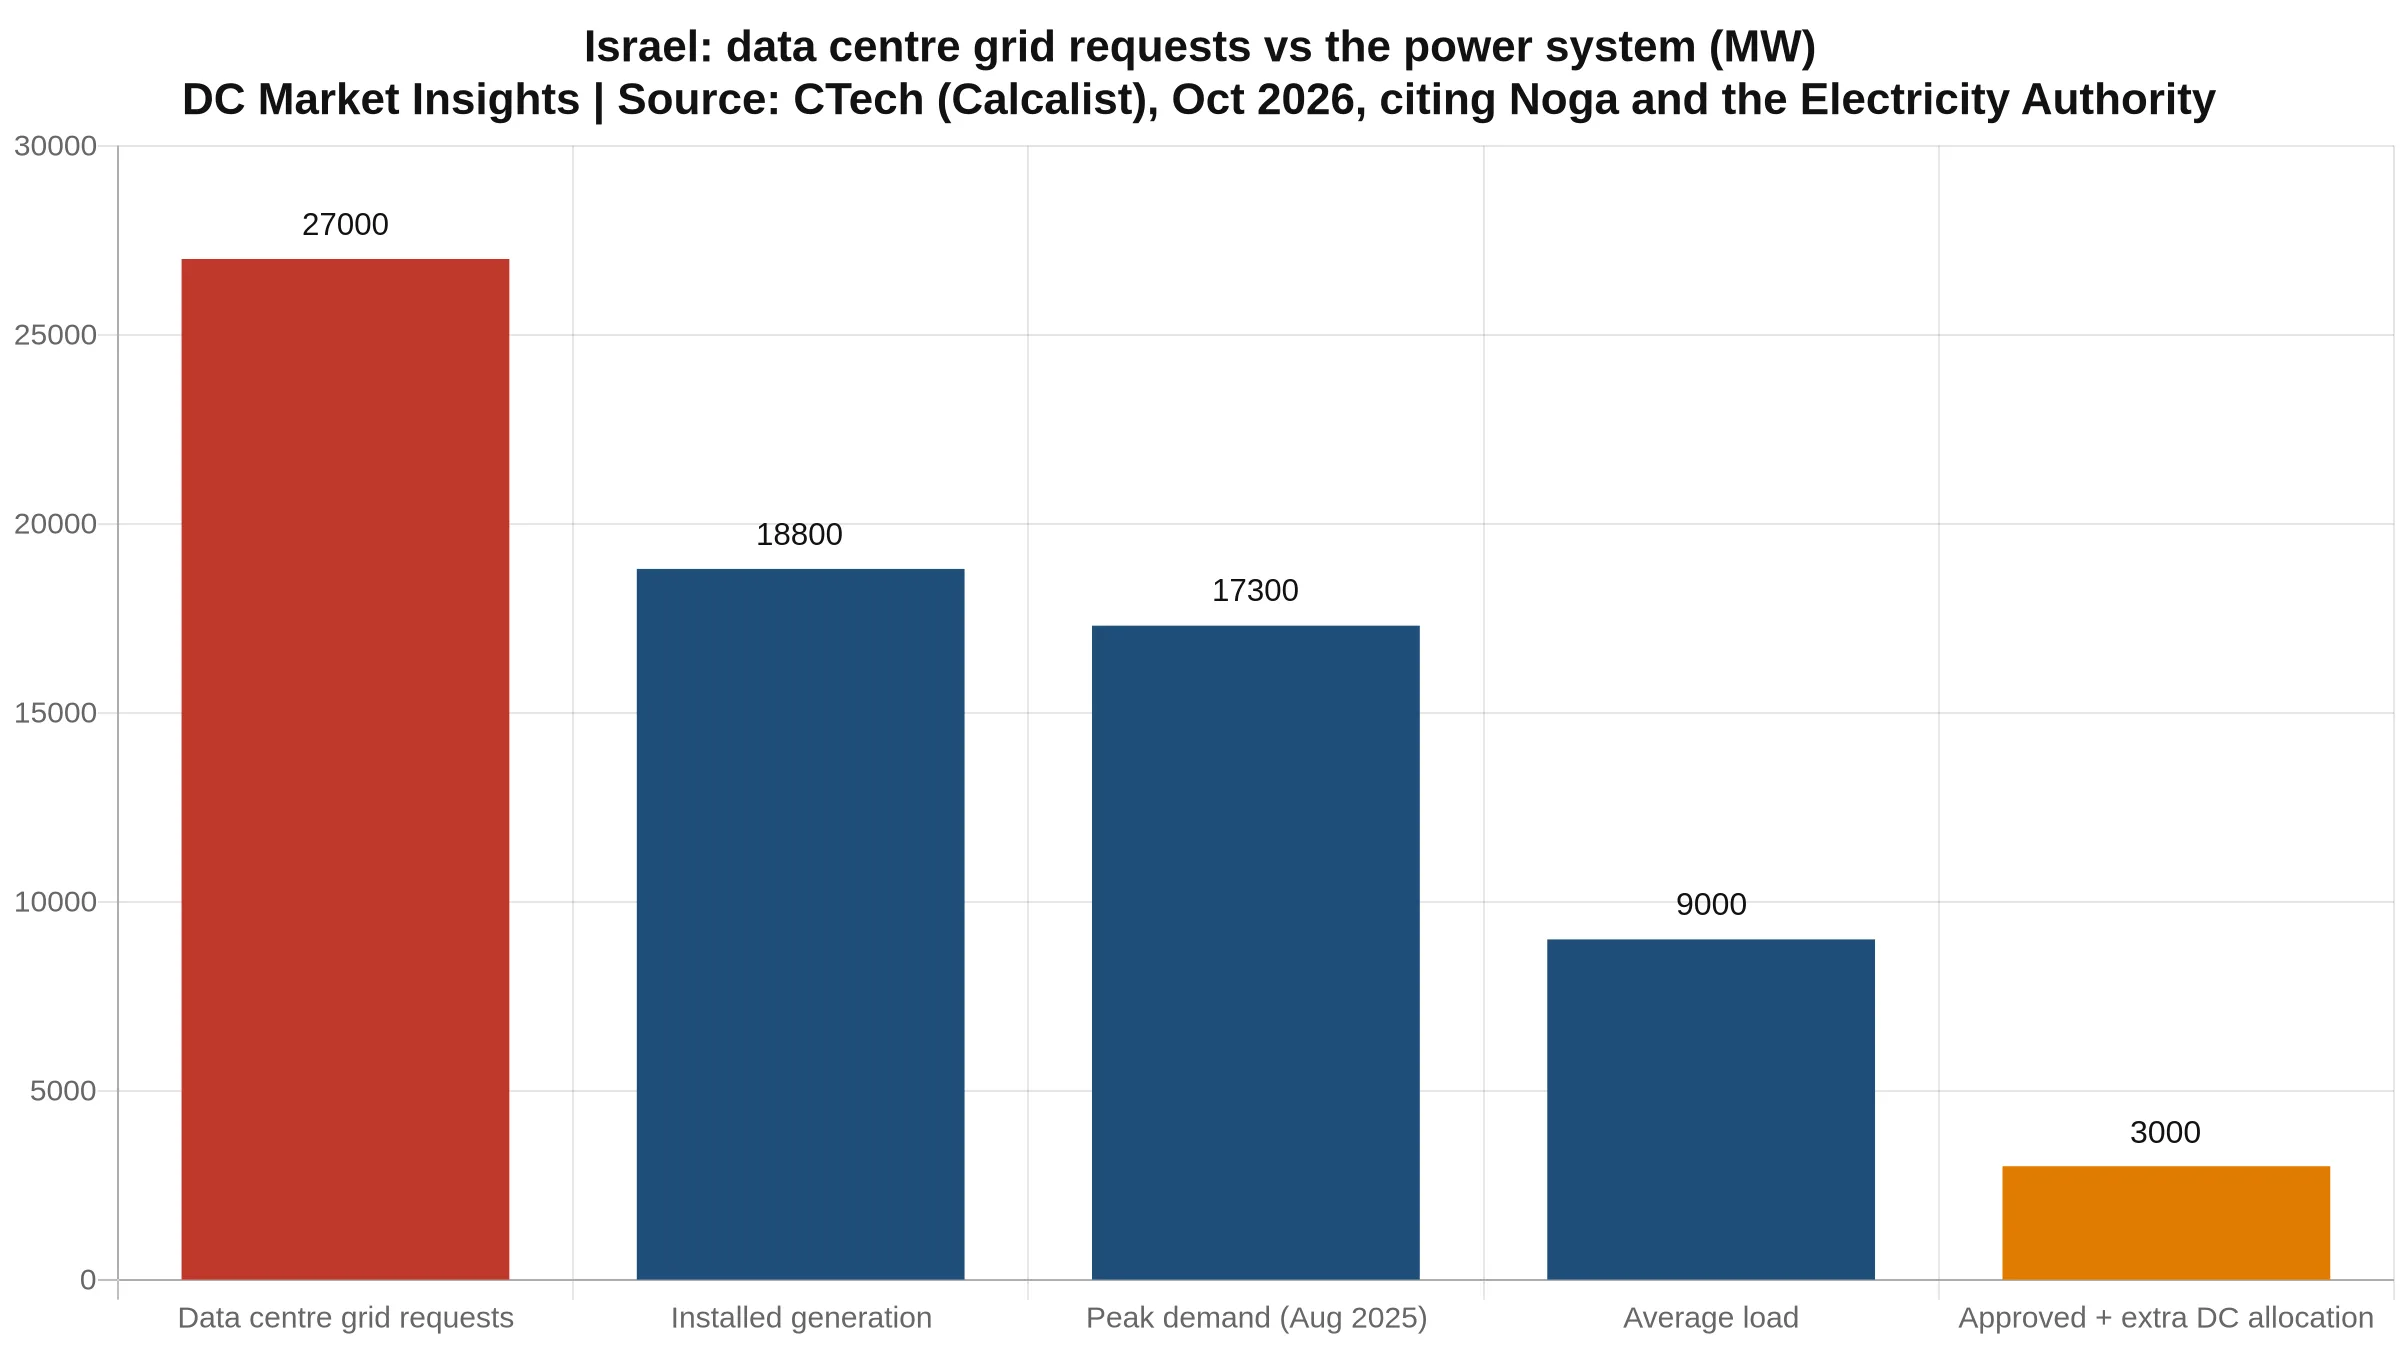
- Israel’s Electricity Authority plans a 200 MW cap per new data centre after developers asked for 27,000 MW of connections, 1.44 times the country’s 18,800 MW of installed generation (CTech, 14 and 19 Oct 2026).
In ten days, developers proposed almost 2.8 GW of new data centre capacity across the UK and Spain, and less than a thirtieth of it has a grid date before 2030. The same fortnight showed what happens when power is late: Microsoft walked away from the UK’s flagship AI site, and Israel moved to cap every new campus at 200 MW.
Why now: this is the Friday read of our trackers for Europe, the Middle East and Africa. The signal this week is the gap between announced megawatts and connected megawatts. Spain’s revised data centre decree went to the Council of State on 26 October, Israel’s consultation on its cap is open, and Germany’s grid connection package and the EU’s AI gigafactory bids both fall due in the next two weeks. Each will decide which of these plans gets power.
New facilities: gigawatt plans, megawatt connections
The UK produced two gigawatt proposals in three days. On 22 October Era4, the developer known as Carbon3.ai until March, detailed “The Mill”, an AI campus on a former steelworks site on Corporation Road in Newport, South Wales, designed to reach 1 GW and capacity for up to 400,000 Nvidia GPUs, with a first phase due in 2027. The site sits inside the South Wales AI Growth Zone, which promises priority grid access, but Era4 has not published a connection date or capacity for the first phase. Two days earlier, Evolution Power’s subsidiary EPL Norfolk opened consultation on Longmarsh Green Energy, up to 1 GW of data centres with 1.3 GW of solar and batteries on about 4,695 acres near King’s Lynn. It would connect at the Walpole substation in 2031, reNEWS reported, with a development consent application planned for April 2027 and operation by 2032.
Spain added two more. An Oman-linked fund, O-Green, is financing a 570 MW campus at San Mateo de Gállego near Zaragoza, €7.446 billion over four phases to 2035, with a first phase of 90 MW and €1.17 billion for the data centre by 2029, Heraldo de Aragón reported on 20 October. Grid permits cover that first 90 MW: 80 MW at the Peñaflor substation and 10 MW at Villanueva de Gállego. The rest has no access yet. In Belchite, the engineering firm Krolmap plans a €1.5 billion, 225 MW campus that would run on its own renewables, batteries and cogeneration with no transmission connection, Heraldo reported on 18 October. No tenant or financial partner has been named.
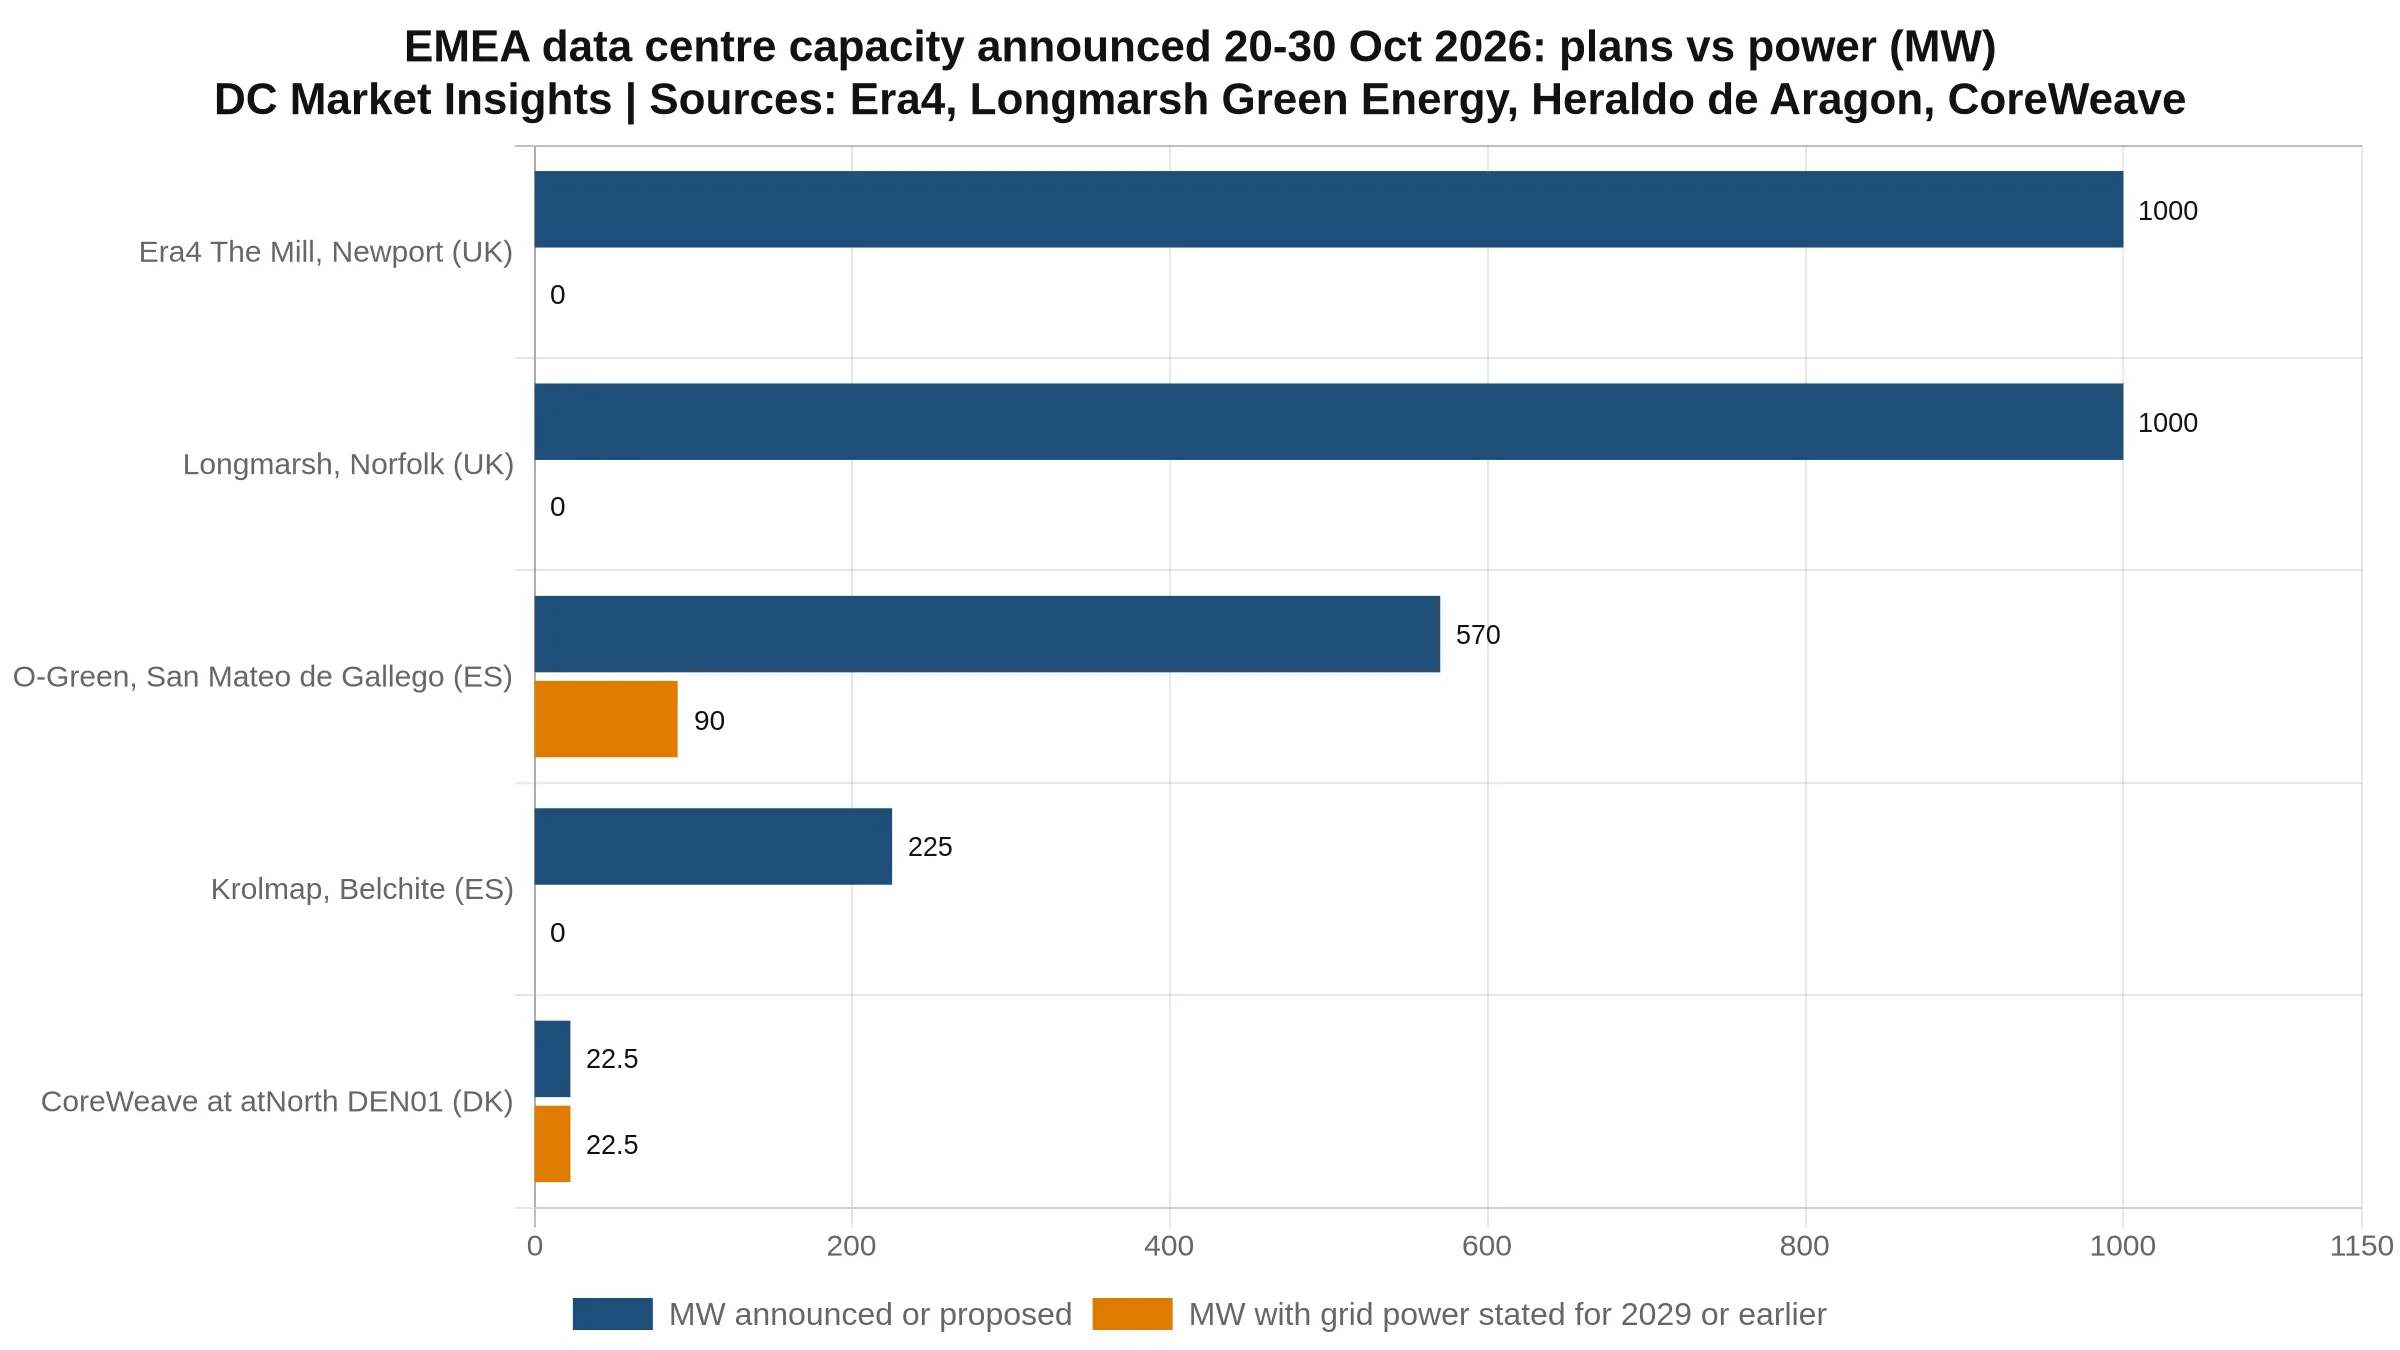
Added up, the four proposals come to 2,795 MW. Only O-Green’s 90 MW, about 3%, has grid access on the record for 2029 or earlier (our calculation). The two UK gigawatt plans alone equal 2.5 times the 804 MW of live UK capacity that DC Market Insights tracks, and 28% of the 7,065 MW of UK plans already in our tracker.
| Project | Country | Announced | MW proposed | Grid position stated | Stated investment | Investment per MW (our calc.) |
|---|---|---|---|---|---|---|
| Era4, The Mill, Newport | UK | 22 Oct | 1,000 | AI Growth Zone priority access; no date or MW published | not disclosed | – |
| EPL Norfolk, Longmarsh Green Energy | UK | 20 Oct | 1,000 | Walpole substation, 2031 | “could attract £25bn” (developer, incl. 1.3 GW solar) | not comparable |
| O-Green, San Mateo de Gállego | Spain | 20 Oct | 570 | 90 MW permitted (Peñaflor 80, Villanueva 10) | €7.446bn | €13.1m |
| Krolmap, Belchite | Spain | 18-23 Oct | 225 | Off-grid by design | €1.5bn | €6.7m |
| Total | 2,795 | 90 MW (3%) by 2029 |
Sources: Era4 project page; Longmarsh Green Energy consultation and reNEWS; Heraldo de Aragón (20 and 18 Oct 2026); El Periódico de Aragón (Vantage plot, 24 Jul 2026). Investment per MW = stated investment ÷ MW proposed (our calculation). Krolmap’s figure appears to exclude the on-site power plant’s full cost and is not directly comparable. O-Green’s first phase works out at €13.0m per MW (€1.17bn ÷ 90 MW), close to the US$12.76 per watt European build cost in Turner & Townsend’s 2026-27 index, which we covered on 29 October.
The Zaragoza site carries its own warning. O-Green’s partners took over a plan that Vantage Data Centers had announced in September 2025 at nearby Villanueva de Gállego and gave up in July 2026 over connection problems at the saturated Villanueva and Peñaflor nodes, El Periódico de Aragón reported. The new plan draws on the same two substations.
Status moves: what actually switched on
Against 2.8 GW of plans, the capacity that went live this fortnight was measured in tens of megawatts. On 27 October CoreWeave said most of its 22.5 MW of planned IT capacity at atNorth’s DEN01 in Ballerup, Greater Copenhagen, was online, its first site in Denmark and part of a European footprint of nine data centres, the company said.
Our customers need more than access to computing capacity.
Our own tracker moved the same way. Between 21 and 30 October the UK records in DC Market Insights data rose from 184 to 187 facilities; live capacity went from 760 MW to 804 MW (+44 MW), under-construction capacity fell from 286 MW to 260 MW as sites completed, and planned capacity rose from 6,935 MW to 7,065 MW (+130 MW). UK plans are now 8.8 times live capacity. Germany’s figures were unchanged at 844 MW live, 2,014 MW under construction and 2,415 MW planned. Across all 65 countries we track, 19,845 MW is live, 30,988 MW is under construction and 68,818 MW is planned, in 2,968 facilities.
| DC Market Insights data | UK, 21 Oct | UK, 30 Oct | Change | Germany, 30 Oct | All 65 countries, 30 Oct |
|---|---|---|---|---|---|
| Facilities tracked | 184 | 187 | +3 | 177 | 2,968 |
| Live MW | 759.6 | 804.0 | +44.4 | 843.8 | 19,845.1 |
| Under construction MW | 286.0 | 260.0 | -26.0 | 2,013.9 | 30,988.2 |
| Planned MW | 6,935.4 | 7,064.9 | +129.5 | 2,414.8 | 68,818.3 |
| Planned ÷ live | 9.1× | 8.8× | 2.9× | 3.5× |
Source: DC Market Insights data (facilities tracker, read 30 Oct 2026, 04:53-04:55 UTC; UK figures for 21 Oct from our 21 October analysis). MW are tracker totals for facilities with a stated or estimated MW (104 of 187 UK sites; 88 of 177 German sites), so they understate the full market. The two new UK gigawatt proposals were not yet in the tracker at the time of reading.
Deals: buyers pay for power, and one anchor tenant left
The biggest closed deal of the week in the region was in London’s Docklands. On 29 October KDDI and Telehouse completed the purchase of the Inventory Estate at East India Dock, next to the Telehouse campus, from LaSalle Investment Management and Trilogy Real Estate for more than £220 million (US$294 million), Telehouse said. The estate comes with 65 MVA of secured power. That prices the site at about £3.4 million per MVA of secured supply (our calculation). The sellers bought the estate from Criterion Capital for £170 million in 2015, so the value rose about 29% (our calculation).
represents an important step in the long-term development of our London Docklands campus
Ten days earlier the region lost a headline tenant. On 19 October Microsoft confirmed it had ended its plan to anchor Nscale’s data centre at Loughton, Essex, after UK Power Networks said the site’s connection would not be ready for its 2026 target because of upstream transmission works, City AM reported. Grid officials told Nscale the site would not have power until the 2030s, according to UK media cited by Bloomberg. Microsoft said the decision “relates to a single site”; Nscale said it was “exploring alternative power sources”. Nscale had pledged £2 billion for the facility. DC Market Insights tracks one Nscale UK site in planning at 50 MW.
Germany got the week’s largest pledge. On 20 October Amazon said it plans to invest €16 billion in Germany in 2027, including €4.8 billion to expand the AWS Europe (Frankfurt) Region, Amazon said at the Invest in Germany Summit in Berlin. AWS is 30% of the total (our calculation). Our German tracker shows 300 MW in the AWS pipeline there.
Amazon’s investment is a clear vote of confidence in Germany as a location for the future.
Rules: Israel caps, Spain relaxes
Israel is the sharpest case of demand outrunning a grid. Developers have asked Noga, the system operator, for 27,000 MW of data centre connections, against 18,800 MW of installed generation, an average load of about 9,000 MW and a peak of 17,300 MW in August 2025, CTech reported on 14 October. Requests include 50 facilities above 200 MW. The Electricity Authority’s answer is a ceiling of 200 MW for any new data centre, with no geographic limits; on that basis the 1,100 MW Mega DC project in Hadera and the 875 MW SDS project in Nesher could not go ahead as planned.
The Authority published the main points on 18 October, CTech reported the next day: about 2,000 MW of connections already approved, 1,000 MW more allocated to large data centres, and a guarantee of NIS 2 million per MW requested. The full decision then goes to a three-week public consultation. Approved and allocated capacity of about 3,000 MW covers 11% of the 27,000 MW requested (our calculation). For a 200 MW campus, which CTech puts at more than NIS 4 billion to build, the guarantee would be NIS 400 million, about 10% of build cost (our calculation).
Spain is moving the other way. On 26 October the government sent a revised royal decree on data centre energy, environmental, resilience and digital sovereignty requirements to the Council of State after more than 600 submissions, El Periódico de la Energía reported. The rules now apply from 10 MW of access capacity, up from 1 MW, with sites of the same owner counted together. The core rule stays: 80% of consumption from additional renewables, matched hour by hour. But plants up to 36 months old (from 18) now count, minimum PPA terms fall from ten to six years, storage counts towards hourly matching, and the PUE ceiling rises from 1.15 to 1.25 for sites that sign access contracts before 1 January 2029, until the end of 2031. WUE stays at 0.1. Sites that opt out of the 80% rule must join the interruptibility scheme. We covered the first draft and Aragón’s 12 GW of grid access on 13 October.
| Rule | Country | Date | What it does | Status |
|---|---|---|---|---|
| 200 MW cap per new data centre | Israel | Main points 18 Oct 2026 | Caps new sites at 200 MW; ~2,000 MW approved + 1,000 MW extra for large DCs; NIS 2m/MW guarantee | Proposed; three-week consultation on the full decision |
| Revised data centre royal decree | Spain | To Council of State 26 Oct 2026 | Threshold 1 → 10 MW; 80% hourly-matched new renewables; PUE 1.15 → 1.25 to 2031; WUE 0.1 | Draft; government aims to approve before 29 Nov election |
| Data centre connection reforms | UK | 29 Jul 2026 | Proposed data centre connection reforms, alongside Ofgem’s proposed Data Centre Commitment Fee (our 19 Oct analysis) | Proposed (DCMI policy PP-GB-013) |
| Netzanschlusspaket | Germany | Draft 29 Jul 2026 | Grid connection package (EnWG, KraftNAV, StromNEV changes) | Bundestag readings expected 9-13 Nov (DCMI policy PP-DE-009) |
Sources: CTech (14 and 19 Oct 2026); El Periódico de la Energía (26 Oct 2026); DC Market Insights power and policy tracker (UK and Germany rows). Spain’s pre-election approval aim was reported by Reuters on 26-27 Oct; we could not open the wire copy and list it as a reported aim, not a fixed date.
The wider pattern: power is the scarce asset
This fortnight’s four data levels point the same way. New plans are large and mostly unpowered; the capacity that switched on was small and sat in an existing building; the best-priced deal was for land with secured power; and the anchor tenant that left did so because the grid was late. Regulators are now rationing connections outright (Israel), charging for them (Britain’s proposed security fee, which we analysed on 19 October) or loosening other rules so that connected sites can fill (Spain).
Developers are responding by bringing their own power. Krolmap plans no grid link at all; Longmarsh pairs 1 GW of load with 1.3 GW of solar and batteries; Nscale is “exploring alternative power sources” at Loughton. Solar of 1.3 GW cannot run a 1 GW load around the clock, so such schemes still depend on the grid or on gas and batteries for most hours. The same tension showed in the Netherlands, where data centres hold about 15 GW of queued grid requests, as we reported on 26 October.
What it means for operators, investors and vendors
Our view, based on the figures above:
- Discount announced megawatts by their grid date. Of 2,795 MW proposed in the UK and Spain this fortnight, only 90 MW (3%) has grid access stated for 2029 or earlier; value the rest as options, not capacity.
- Price secured power, not land. The East India Dock deal implies about £3.4 million per MVA; use that as a London benchmark for sites with a firm connection.
- In Israel, design to 200 MW and budget the guarantee. NIS 2 million per MW is NIS 400 million on a 200 MW request, about 10% of build cost; 50 requested sites above 200 MW will have to shrink or split.
- In Spain, sites of 10 MW or more still need 80% hourly-matched new renewables. A 90 MW first phase like O-Green’s would need about 72 MW of hourly-matched renewable supply at full load (our calculation), plus storage; the PUE relief to 1.25 lasts only to 2031.
- Vendors: on-site power is the growth line. Off-grid and grid-light campuses (225 MW at Belchite, 1.3 GW solar at Longmarsh) need generators, batteries and microgrid controls before they need servers.
For market sizing, see our UK AI Data Center Market report for British AI capacity and spend, the Spain Data Center Market report for the Iberian build-out, and the Data Center Generator Market report for on-site power. For the data behind this read, see the Deal Tracker, our United Kingdom power and policy page and our Germany power and policy page.
What to watch next
- Early November 2026: Spain’s Council of State opinion and Council of Ministers approval of the revised data centre decree, which the government aims to pass before the 29 November election.
- Early to mid November 2026: Israel’s three-week consultation on the full 200 MW decision; the exact closing date depends on when the full text was published.
- 9-13 November 2026: expected second and third Bundestag readings of Germany’s grid connection package.
- 12 November 2026: bid deadline for the EU AI gigafactory call, for sites of up to 150 MW (the call page has also shown 3 December).
- 26 November 2026: Longmarsh Green Energy community consultation closes; a development consent application is planned for April 2027.
- 29 November 2026: Spain’s general election.
Frequently asked questions
How much new data centre capacity was announced in Europe in late October 2026?
About 2,795 MW in four UK and Spanish proposals between 18 and 23 October: Era4 Newport (1 GW), Longmarsh Norfolk (1 GW), O-Green Zaragoza (570 MW) and Krolmap Belchite (225 MW). Only 90 MW, about 3%, has grid access stated for 2029 or earlier (our calculation).
Why did Microsoft pull out of Nscale’s Loughton data centre?
Because the grid was late. UK Power Networks said the Loughton site would not be connected by its 2026 target due to upstream transmission works, and UK media reported power only in the 2030s. Microsoft said on 19 October the decision related to a single site; Nscale had pledged £2 billion for it.
What is Israel’s 200 MW data centre cap?
A proposed Electricity Authority rule limiting any new data centre to 200 MW, after developers requested 27,000 MW of connections against 18,800 MW of installed generation. About 2,000 MW is approved, 1,000 MW more is allocated to large data centres, and applicants post NIS 2 million per MW.
What changed in Spain’s data centre decree?
The revised draft, sent to the Council of State on 26 October, applies from 10 MW instead of 1 MW, keeps the 80% hourly-matched renewables rule, lets older plants and six-year PPAs count, and raises the PUE limit from 1.15 to 1.25 until 2031 for sites contracting grid access before 2029.
Sources
- Era4, “The Mill”, project page, Oct 2026. Link
- Longmarsh Green Energy (EPL Norfolk), community consultation, Oct 2026. Link
- reNEWS, “EPL Norfolk proposes 1.3GW solar project”, Oct 2026. Link
- Heraldo de Aragón, “O-Green eleva la inversión de su centro de datos en Zaragoza a 7.446 millones de euros”, 20 Oct 2026. Link
- Heraldo de Aragón, “Una ingeniería aragonesa proyecta en Belchite el primer centro de datos de España sin conexión a la red eléctrica”, 18 Oct 2026. Link
- El Periódico de Aragón, “Vantage reubicará su centro de datos tras renunciar a Zaragoza”, 24 Jul 2026. Link
- CoreWeave, “CoreWeave expands global AI cloud platform with new capacity in Denmark and first AI network backbone”, 27 Oct 2026. Link
- Telehouse, “KDDI and Telehouse complete land acquisition worth over £220 million to expand London Docklands campus”, 29 Oct 2026. Link
- City AM, “Microsoft pulls out of Nscale deal for UK’s largest AI data centre”, 19 Oct 2026. Link
- Bloomberg via BNN Bloomberg, “Microsoft pulled out of AI data centre deal with a UK startup”, 19 Oct 2026. Link
- Amazon, “Amazon plans to invest €16 billion in Germany in 2027”, 20 Oct 2026. Link
- CTech (Calcalist), “Israel to cap new data centers at 200 megawatts amid AI power crunch”, 14 Oct 2026. Link
- CTech (Calcalist), Electricity Authority data centre rules, 19 Oct 2026. Link
- El Periódico de la Energía, “El Gobierno da un respiro a los centros de datos con requisitos energéticos menos exigentes”, 26 Oct 2026. Link
- DC Market Insights data: facilities tracker (UK, Germany, all countries) and power and policy tracker, read 30 Oct 2026. Link
- DC Market Insights, UK AI Data Center Market, Spain Data Center Market and Data Center Generator Market reports. Link