
AI Server Analog IC Market Size, Share & Forecast to 2035
Market at a glance
The AI Server Analog IC market was worth USD 1,360.0 million in 2025 and is forecast to reach USD 5,590.0 million by 2035, growing at a 15.19% CAGR.
 By Amit Jain, Senior Consultant, ICT & Emerging Technologies
 Reviewed by Deepti Agrawal
Last updated 29 Oct 2026
Base year 2025 PDF + Excel
Key findings
1,400 W Accelerator Boards Need About 19 Smart Power Stages Each
800 V DC Racks from 2027 Create a 64:1 Converter Socket on Every Tray
High-Ratio Converter Controllers and Drivers: USD 670.33 Million by 2035
What is inside the report
- 01Introduction
- 02Executive Summary
- 03Market Scope
- 04Why AI Server Analog IC Market Estimates Differ
- 05Market Drivers
- 06Market Trends
- 07Market Challenges and Restraints
- 08Market Opportunities
- 09Pricing Analysis
- 10Standards and Regulation
- 19chapters
- 2020-2024Historical period
- 2026-2035Forecast period
- —Companies profiled
Segmentation
Recent developments
Rambus reported record third-quarter product revenue of USD 114.3 million, up 22% year on year (Source: Rambus).
Texas Instruments said data center revenue grew about 95% year on year and reached about 13% of company revenue (Source: Texas Instruments third-quarter 2026 remarks).
Meta reported third-quarter capital expenditure of USD 34.91 billion and narrowed 2026 guidance to USD 135 billion to USD 145 billion (Source: Meta).
Infineon raised its fiscal 2026 AI power revenue target to more than EUR 1.6 billion and said it would raise its fiscal 2027 projection (Source: Infineon third-quarter fiscal 2026 statement).
onsemi said AI data center revenue would more than double in 2026 (Source: onsemi).
SiTime completed its acquisition of the Renesas timing business, adding more than 550 clocking products (Source: SiTime).
Full analysis
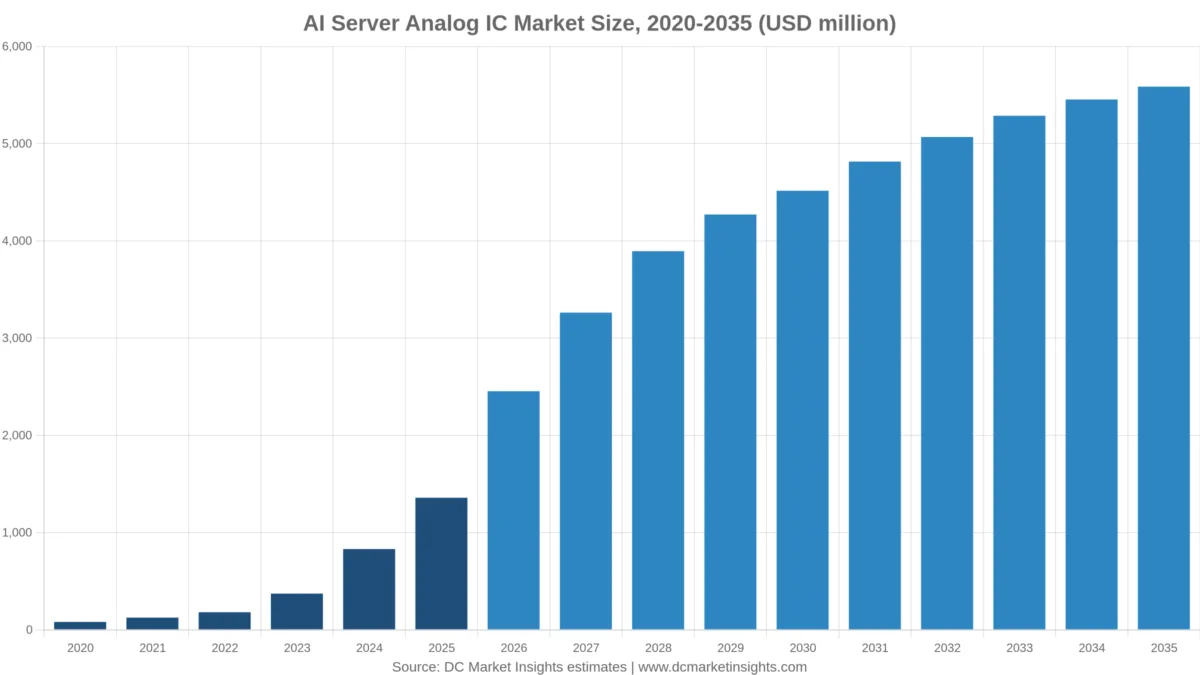
The AI Server Analog IC Market is valued at USD 2.45 billion in 2026 and is projected to reach USD 5.59 billion by 2035, up from USD 1.36 billion in 2025, a CAGR of 15.19% from 2025 to 2035 (DC Market Insights estimate). Money in this market follows amperes on the board rather than server counts: an AMD Instinct MI355X is rated at 1,400 W of typical board power, according to AMD, so its core rail needs roughly 19 smart power stages where a 400 W A100-class board needed six. Monolithic Power Systems (MPS) showed how fast that demand arrived when its Enterprise Data revenue rose 164.3% year on year to USD 380.6 million in the second quarter of 2026, according to its second-quarter 2026 results filing. The market covers the analog and mixed-signal chips soldered into AI servers: multiphase voltage-regulator controllers and smart power stages, electronic fuses (eFuses) and hot-swap controllers, power management ICs (PMICs) for server memory, clock generators, linear redrivers, and current and temperature sensors. DC Market Insights builds it from the board-level conversion value of AI servers (USD 1.80 billion in 2025) times a 55% silicon share, plus 11.48 million accelerators times USD 32 of non-power analog content. High-ratio converter controllers and drivers grow fastest at 28.57% a year because 800 V racks add a new converter on every tray, and the Middle East and Africa is the fastest region at 19.03%.
Key Market Statistics: How Big Is the AI Server Analog IC Market in 2026?
The AI Server Analog IC Market is worth USD 2.45 billion in 2026, 80.7% more than the USD 1.36 billion of 2025, according to DC Market Insights estimates.
- Market size 2025: USD 1.36 billion
- Market size 2026: USD 2.45 billion
- Market size 2030: USD 4.52 billion
- Market size 2035: USD 5.59 billion
- CAGR 2025-2035: 15.19% (low case 11.47%, high case 17.89%)
- Largest product type: Multiphase Controllers and Smart Power Stages, 60% of 2025 value
- Fastest product type: High-Ratio Converter Controllers and Drivers, 28.57% a year
- Leading region: North America, 59.4% of 2025 value; fastest region: Middle East and Africa, 19.03% a year
- Largest country: United States, 54.8% of 2025 value
- Market leader: Monolithic Power Systems, about 27% of 2025 value (DC Market Insights estimate)
Executive Summary: What Is Driving AI Server Analog Chip Spending?
The Global AI Server Analog IC Market size was valued at USD 81.04 million in 2020, reached USD 1.36 billion in 2025, and is anticipated to reach USD 5.59 billion by 2035, at a CAGR of 15.19% during the forecast period.
| Attribute | Value |
|---|---|
| Historical period | 2020-2024 |
| Base year | 2025 |
| Forecast period | 2026-2035 |
| Market size 2025 | USD 1.36 billion |
| Market size 2026 | USD 2.45 billion |
| CAGR 2025-2035 | 15.19% |
| Market size 2035 | USD 5.59 billion |
AI server analog chip spending grew 75.73% a year from 2020 to 2025 as accelerator shipments went from 1.10 million to 11.48 million and board power climbed past 1,000 W. Growth slows to 15.19% a year after 2025 because DC Market Insights expects shipments to flatten near 29 million units by 2035 and analog content per kilowatt of board power to halve, from USD 188.5 to USD 94.8, as suppliers integrate more phases per die. The 2026 jump of 80.7% reflects the Blackwell and MI355X ramp, with the AI server analog IC market content per accelerator rising to about USD 158.3 in 2026.
Market Scope: Which Chips Count as AI Server Analog ICs?
The AI server analog IC market counts USD 1.36 billion of analog and mixed-signal silicon in 2025, sold into servers built around AI accelerators.
Included
- Multiphase voltage-regulator controllers and smart power stages (DrMOS-type driver plus MOSFET packages) on accelerator modules, baseboards and host boards.
- Electronic fuses, hot-swap controllers and other input protection ICs.
- PMICs on DDR5 server memory modules and on LPDDR5X Small Outline Compression Attached Memory Modules (SOCAMM2).
- Clock generators, clock buffers and oscillators for accelerators, CPUs and network interface cards.
- Linear redrivers, isolators and other signal integrity and interface ICs.
- Current, voltage and temperature sensing and power monitoring ICs, plus the controllers and drivers of 48 V and 800 V converters mounted on the server tray.
Excluded
- Inductors, capacitors, module packaging and assembly value of power modules (covered as module value in the AI Server Power Modules Market).
- Silicon carbide and gallium nitride power devices inside AC-DC power supply units and power shelves.
- Digital retimers, serializer-deserializer (SerDes) chips, optical digital signal processors and transceiver analog front ends.
- Analog chips in general-purpose servers, storage arrays and facility power and cooling equipment.
How the Segments Fit Together
Every split of the AI server analog IC market sums to the same total each year: product type, accelerator platform, board location and end user each add up to USD 1.36 billion in 2025 and USD 5.59 billion in 2035. Regions and countries follow where AI accelerators are installed, using the shares of the DC Market Insights Data Center Accelerator Market model.
Why Do AI Server Analog IC Market Estimates Differ?
The AI Server Analog IC Market is USD 2.45 billion in 2026 in the DC Market Insights definition, which counts only board-level analog and mixed-signal chips inside AI servers.
Broader estimates for AI server analog ICs usually add three layers. The first is power semiconductors in the rack power shelves and AC-DC power supplies, where silicon carbide and gallium nitride switches sit. The second is the analog front end of optical transceivers, such as laser drivers and transimpedance amplifiers. The third is analog content in conventional servers, storage and networking gear that carries no AI accelerator. Some definitions also count digital retimers as interface chips. Each of these sits outside this estimate, which keeps the board as the boundary so that the figures line up with the AI Server Power Modules Market and the High End AI Server PCB Market. Buyers inside the scope include hyperscale cloud providers, GPU cloud and neocloud operators, enterprises and government AI programs, as well as the original design manufacturers that build their trays.
| Element | In this report | Why |
|---|---|---|
| Power ICs on AI server boards | Yes, USD 990.59 million (2025) | Silicon share of board-level conversion |
| Timing, interface, sensing and memory PMICs | Yes, USD 367.36 million (2025) | Non-power analog content per accelerator |
| Power shelf and PSU semiconductors | No | Counted in power supply unit value |
| Optical analog front ends and retimers | No | Counted in optics and interconnect value |
| Analog chips in general-purpose servers | No | No AI accelerator on the board |
Market Drivers: Why Are AI Servers Using More Analog Chips?
AI server analog IC demand rose from USD 73.7 of content per accelerator in 2020 to USD 118.3 in 2025, and three market-specific forces explain most of that move.
1,400 W Accelerator Boards Need About 19 Smart Power Stages Each
Core-rail current scales with board power, and board power keeps climbing. AMD lists 1,400 W of typical board power for the Instinct MI355X, and NVIDIA’s reference architecture puts a full GB300 NVL72 rack at up to 142 kW, according to NVIDIA documentation. At 90 A per stage and 80% loading, DC Market Insights counts about 19 stages for a 1,400 W part against six for a 400 W board in 2020. That is why the analog IC content of a GPU-based AI server reached about USD 166.0 per GPU in 2025, against about USD 60.3 per custom application-specific integrated circuit (ASIC).
MPS Enterprise Data Revenue Rose 164.3% in the Second Quarter of 2026
Supplier results show the order flow behind the AI server analog IC market. MPS reported Enterprise Data revenue of USD 380.6 million in the second quarter of 2026, up 44.8% from the first quarter, and guided total third-quarter revenue to USD 1.14 billion to USD 1.16 billion, according to its results filing. Alpha and Omega Semiconductor (AOS) said in August 2026 that its AI and server business would grow more than 60% sequentially, according to its prepared remarks. Both companies sell smart power stages that sit next to the accelerator.
Hyperscaler Capex Guides of USD 135 Billion to USD 205 Billion for 2026
The buyers of AI servers raised spending again in 2026. Alphabet lifted its 2026 capital expenditure guidance to USD 195 billion to USD 205 billion in July 2026, Amazon guided to about USD 200 billion, and Meta narrowed its range to USD 135 billion to USD 145 billion in October 2026, according to the companies’ own earnings releases. DC Market Insights ties about 15.50 million accelerator shipments in 2026 to that spending, which lifts the AI server analog IC market by 80.7% in one year.
Market Trends: How Is the AI Server Analog Chip Mix Changing?
Three trends move the AI server analog IC mix toward high-ratio conversion, timing consolidation and memory PMICs between 2025 and 2035.
800 V DC Racks from 2027 Create a 64:1 Converter Socket on Every Tray
NVIDIA plans 800 V direct-current (VDC) power for 1 MW racks from 2027, with its Kyber rack holding 576 Rubin Ultra GPUs. In NVIDIA’s design a high-ratio 64:1 LLC (inductor-inductor-capacitor resonant) converter steps 800 VDC down to 12 VDC next to the GPU, and NVIDIA names Texas Instruments, Analog Devices, Infineon, MPS, Renesas and onsemi among the silicon partners, according to its 800 VDC ecosystem blog of October 2025. Google, Meta and Microsoft are pushing a parallel plus-or-minus 400 VDC design through the Open Compute Project (OCP), according to Google Cloud. DC Market Insights expects high-ratio converter controllers and drivers to rise from 4% of AI server analog IC value in 2025 to 12% by 2035.
SiTime Closes Its USD 1.5 Billion Purchase of the Renesas Timing Business
Clock chips are consolidating around AI demand. SiTime agreed to buy the Renesas timing business for USD 1.5 billion in cash plus about 4.13 million shares, a unit expected to bring about USD 300 million of revenue in its first 12 months with nearly 75% from AI, data center and communications, according to SiTime. The deal closed on 1 July 2026 and added more than 550 clocking products. Timing and clock ICs hold 10% of the AI server analog IC market in 2025.
SOCAMM2 and DDR5 Modules Put More PMICs Next to the Processor
Server memory now carries its own power management chip. The Joint Electron Device Engineering Council (JEDEC) PMIC5100 and PMIC5200 standards (JESD301-2 and JESD301-3) define the DDR5 module PMIC, and JESD328 covers SOCAMM2 modules for LPDDR5X server memory, according to JEDEC’s standards list. Rambus reported record third-quarter 2026 product revenue of USD 114.3 million, up 22%, and cited a PMIC for LPDDR6 SOCAMM2, according to its results release of October 2026. Memory PMICs grow from 6% to 7% of the AI server analog IC market by 2035.
Market Challenges and Restraints: What Could Slow AI Server Analog IC Demand?
Two restraints weigh on the AI server analog IC market: trade action on US analog chips and falling content per kilowatt.
China’s Anti-Dumping Case on US Analog Chips and the 10 November 2026 Truce Date
China’s Ministry of Commerce (MOFCOM) opened an anti-dumping investigation into US-origin analog chips on 13 September 2025, covering commodity interface ICs and gate-driver ICs made on 40 nm and larger processes, according to MOFCOM Announcement No. 27 of 2025. The applicant said imports rose 37% from 2022 to 2024 while import prices fell 52%, according to MOFCOM. The White House fact sheet of 1 November 2025 says China will terminate its investigations of US semiconductor firms, and MOFCOM restated in September 2026 that the suspension of certain measures runs until 10 November 2026. China holds about 11.1% of the AI server analog IC market in 2025 by installation, so a lapse would shift sockets toward Chinese and non-US suppliers rather than cut demand.
Analog Content per Kilowatt Falls from USD 188.5 to USD 94.8 by 2035
Each new accelerator generation needs more amperes but pays less per ampere. DC Market Insights puts AI server analog IC content at USD 188.5 per kilowatt of accelerator board power in 2025, falling to USD 123.8 in 2030 and USD 94.8 in 2035, because stages carry more current per package, controllers handle more phases, and integrated voltage regulators move part of the conversion into the processor package. The silicon share of board-level conversion value falls from 55% to 50% over the same period.
Market Opportunities: Where Is the New AI Server Analog Chip Revenue?
Two AI server analog IC opportunities stand out by 2035, both linked to higher rack voltage.
High-Ratio Converter Controllers and Drivers: USD 670.33 Million by 2035
Controllers and gate drivers for 48 V and 800 V tray converters grow 28.57% a year, the fastest product line in the AI server analog IC market, as 800 VDC racks start shipping in 2027. MPS said in July 2026 that it had begun sampling high-voltage AC-DC products for 800 V data center architectures, according to its results filing.
Tray Power Conversion Stage: From 8% to 17% of Value
By board location, the tray power conversion stage is the fastest slice of the AI server analog IC market, reaching USD 949.64 million by 2035 at 24.21% a year. Infineon puts its own content at about USD 15,000 per 125 kW rack today and above USD 100,000 per rack above 1 MW from 2029, according to its November 2025 power roadshow, which shows how much silicon moves onto the tray as racks scale.
Pricing Analysis: How Much Analog Silicon Goes into Each AI Accelerator?
AI server analog IC content averaged USD 118.3 per accelerator in 2025 and rises to USD 191.3 by 2035, while content per kilowatt of board power falls by half (DC Market Insights estimate).
| Year | AI accelerators shipped (million) | Accelerator board power shipped (MW) | Analog IC content per accelerator (USD) | Analog IC content per kW of board power (USD) |
|---|---|---|---|---|
| 2020 | 1.10 | 294 | 73.7 | 275.3 |
| 2025 | 11.48 | 7,204 | 118.3 | 188.5 |
| 2030 | 24.00 | 36,476 | 188.2 | 123.8 |
| 2035 | 29.20 | 58,908 | 191.3 | 94.8 |
Public anchors bracket these figures. onsemi puts its semiconductor content at about USD 15,000 per 120 kW rack today and about USD 115,000 per 600 kW to 1 MW rack in 2030, according to its August 2026 investor presentation, and Infineon gives about USD 15,000 per 125 kW rack. Those supplier figures cover the whole power tree from 800 V to 0.8 V; the board-level analog content of an NVL72-class rack in this model is about USD 12,000.
Standards and Regulation: Which Rules Shape AI Server Analog Chips?
Seven standards and rules shape the AI server analog IC market, from memory PMIC specifications to tariffs and chip subsidies.
- JEDEC JESD301-2 (PMIC5100) and JESD301-3 (PMIC5200): DDR5 memory module PMIC standards (Source: JEDEC).
- JEDEC JESD328: SOCAMM2 common standard for LPDDR5 and LPDDR5X server modules (Source: JEDEC).
- OCP Mt Diablo plus-or-minus 400 VDC rack power, announced with Meta and Microsoft in April 2025 to scale racks from 100 kW to 1 MW (Source: Google Cloud).
- US Section 232 proclamation of 14 January 2026: a 25% duty on certain advanced computing chips that does not apply to imports for US data centers (Source: The White House).
- MOFCOM Announcement No. 27 of 2025: anti-dumping investigation into US-origin interface and gate-driver analog chips (Source: MOFCOM).
- CHIPS and Science Act award of December 2024: up to USD 1.6 billion for Texas Instruments’ SM1, SM2 and LFAB2 fabs (Source: Texas Instruments).
- EU State aid decision of February 2025: EUR 920 million for Infineon’s EUR 3.5 billion Dresden fab for power and analog mixed-signal chips (Source: European Commission).
Market Segmentation: Which AI Server Analog IC Segments Are Largest?
Multiphase controllers and smart power stages hold 60% of the AI Server Analog IC Market in 2025, GPU-based servers hold 77%, and hyperscale cloud providers buy 61.7% (DC Market Insights estimates).
By Product Type
Power conversion silicon dominates the AI server analog IC market, while high-ratio converter controllers and drivers grow fastest at 28.57% a year.
| Product type | 2025 (USD million) | Share 2025 | 2035 (USD million) | CAGR 2025-2035 |
|---|---|---|---|---|
| Multiphase Controllers and Smart Power Stages | 814.77 | 60% | 2,904.77 | 13.56% |
| Protection and Hot-Swap ICs | 108.64 | 8% | 502.75 | 16.56% |
| Memory PMICs | 81.48 | 6% | 391.03 | 16.98% |
| Timing and Clock ICs | 135.79 | 10% | 474.82 | 13.34% |
| Signal Integrity and Interface ICs | 95.06 | 7% | 363.10 | 14.34% |
| Sensing and Power Monitoring ICs | 67.90 | 5% | 279.31 | 15.19% |
| High-Ratio Converter Controllers and Drivers | 54.32 | 4% | 670.33 | 28.57% |
By Accelerator Platform
Custom ASIC servers grow 19.78% a year against 13.43% for GPU-based servers, as in-house chips from Google, Amazon Web Services and Meta take a larger share of AI server analog IC demand.
| Accelerator platform | 2025 (USD million) | Share 2025 | 2035 (USD million) | CAGR 2025-2035 |
|---|---|---|---|---|
| GPU-Based AI Servers | 1,045.62 | 77% | 3,686.83 | 13.43% |
| Custom ASIC AI Servers | 312.33 | 23% | 1,899.27 | 19.78% |
By Board Location
The accelerator module and baseboard carry 68% of AI server analog IC value in 2025, falling to 60% as tray converters gain share.
| Board location | 2025 (USD million) | Share 2025 | 2035 (USD million) | CAGR 2025-2035 |
|---|---|---|---|---|
| Accelerator Module and Baseboard | 923.41 | 68% | 3,351.66 | 13.76% |
| Host CPU and Memory Board | 190.11 | 14% | 670.33 | 13.43% |
| Switch and NIC Trays | 135.79 | 10% | 614.47 | 16.3% |
| Tray Power Conversion Stage | 108.64 | 8% | 949.64 | 24.21% |
By End User
Enterprises are the fastest buyers of AI server analog ICs at 17.33% a year, though hyperscale cloud providers still buy 58% of value in 2035.
| End user | 2025 (USD million) | Share 2025 | 2035 (USD million) | CAGR 2025-2035 |
|---|---|---|---|---|
| Hyperscale Cloud Providers | 837.86 | 61.7% | 3,239.94 | 14.48% |
| GPU Cloud and Neocloud Providers | 200.98 | 14.8% | 809.98 | 14.96% |
| Enterprises | 175.18 | 12.9% | 865.85 | 17.33% |
| Government Sovereign AI and Research | 143.94 | 10.6% | 670.33 | 16.63% |
DC Exclusive: AI Server Analog Chip Supplier Map, 9 Vendors by Socket
Nine named vendors hold about 81% of the AI Server Analog IC Market in 2025, according to the DC Market Insights supplier map, a DC Market Insights estimate built on 12 inputs from company filings, results statements and the board-level model.
The map assigns each supplier to the sockets it wins on AI server boards and estimates its share of 2025 value. Shares come from each company’s disclosed data center or AI power revenue, cut to the board-level analog portion, so a supplier whose AI revenue sits mostly in power supply units, such as Infineon, ranks lower here than in rack power. Monolithic Power Systems leads with about 27% because its Enterprise Data line (USD 701.8 million in 2025, according to MPS) is mostly accelerator power stages and controllers.
| Supplier | AI server analog sockets | Share of 2025 value (DC Market Insights estimate) |
|---|---|---|
| Monolithic Power Systems | Multiphase controllers, smart power stages, eFuses | 27% |
| Infineon Technologies | Smart power stages, controllers, 48 V converter controllers | 14% |
| Texas Instruments | eFuses and hot-swap, power stages, redrivers, sensors | 10% |
| Renesas Electronics | Multiphase controllers, memory interface and PMICs | 7% |
| Analog Devices | Power monitors, regulators, integrated voltage regulators | 7% |
| onsemi | Smart power stages, eFuses, controllers | 6% |
| Alpha and Omega Semiconductor | Smart power stages | 4% |
| SiTime | Clock generators, buffers, oscillators | 4% |
| Rambus | DDR5 and SOCAMM2 PMICs | 2% |
| Others | Microchip, STMicroelectronics, Richtek, Navitas, Vishay and others | 19% |
Buyers can read the map two ways. Power stage and controller sockets are contested by six suppliers, so price per ampere falls fastest there. Timing and memory PMIC sockets have two or three qualified vendors each, which is why those lines hold their content per accelerator through 2035.
Regional Insights: Where Are AI Server Analog ICs Installed?
North America leads the AI Server Analog IC Market with USD 806.62 million, or 59.4% of 2025 value, and the Middle East and Africa grows fastest at 19.03% a year.
North America
North America takes 59.4% of AI server analog IC value in 2025 and 14.31% growth a year to 2035. The US Section 232 duty of January 2026 exempts advanced chips imported for US data centers, according to the White House, which keeps AI server builds in the United States free of that tariff.
Asia Pacific
Asia Pacific holds 24.6% of the AI server analog IC market in 2025 and grows 15.65% a year. China is the largest country in the region, and its open MOFCOM case on US analog chips is the main local risk for US suppliers.
Europe
Europe takes 9.2% of AI server analog IC value in 2025 and grows 16.16% a year. Supply is also local: the European Commission approved EUR 920 million of aid for Infineon’s Dresden fab in February 2025.
Middle East and Africa
The Middle East and Africa is the fastest region in the AI server analog IC market at 19.03% a year, led by sovereign AI campuses in Saudi Arabia and the United Arab Emirates, which rank seventh and tenth among countries.
Latin America
Latin America is the smallest region at 1.9% of AI server analog IC value in 2025 but grows 18.86% a year as AI capacity spreads beyond North America.
Country Analysis: Which Countries Buy the Most AI Server Analog ICs?
The United States accounts for 54.8% of the AI Server Analog IC Market in 2025, and India is the fastest large country at 22.76% a year (DC Market Insights estimates).
| Rank | Country | Region | 2025 (USD million) | 2035 (USD million) | CAGR 2025-2035 |
|---|---|---|---|---|---|
| 1 | United States | North America | 744.16 | 2,815.39 | 14.23% |
| 2 | China | Asia Pacific | 150.73 | 502.75 | 12.8% |
| 3 | Canada | North America | 62.47 | 256.96 | 15.19% |
| 4 | Japan | Asia Pacific | 47.53 | 189.93 | 14.86% |
| 5 | South Korea | Asia Pacific | 31.23 | 139.65 | 16.16% |
| 6 | United Kingdom | Europe | 31.23 | 128.48 | 15.19% |
| 7 | Saudi Arabia | Middle East and Africa | 24.44 | 145.24 | 19.51% |
| 8 | Germany | Europe | 24.44 | 106.14 | 15.82% |
| 9 | India | Asia Pacific | 24.44 | 189.93 | 22.76% |
| 10 | United Arab Emirates | Middle East and Africa | 21.73 | 128.48 | 19.45% |
| 11 | Australia | Asia Pacific | 20.37 | 89.38 | 15.94% |
| 12 | France | Europe | 17.65 | 83.79 | 16.85% |
India moves from ninth to joint fourth by 2035 in the AI server analog IC market, as government-backed GPU clusters and hyperscale regions add accelerators from a small base.
Forecast Scenarios: How Large Could the AI Server Analog IC Market Be by 2035?
The AI Server Analog IC Market reaches USD 5.59 billion by 2035 in the base case, with a range of USD 4.02 billion to USD 7.04 billion (DC Market Insights scenarios).
| Scenario | 2035 (USD million) | CAGR 2025-2035 | Assumption |
|---|---|---|---|
| Low | 4,021.99 | 11.47% | Accelerator shipments stall near 2028 levels and integrated voltage regulators take a larger share |
| Base | 5,586.10 | 15.19% | Shipments near 29 million in 2035, 800 VDC racks from 2027 |
| High | 7,038.48 | 17.89% | Faster 1 MW rack adoption and slower price erosion per ampere |
Key Players and Market Share: Who Leads the AI Server Analog IC Market?
The top five suppliers hold about 65% of the AI Server Analog IC Market in 2025 (DC Market Insights estimate, based on disclosed data center and AI power revenue cut to the board-level analog portion).
- Monolithic Power Systems: Enterprise Data revenue USD 701.8 million in 2025 and USD 380.6 million in the second quarter of 2026 (Source: MPS).
- Infineon Technologies: AI data center power revenue almost tripled to more than EUR 700 million in fiscal 2025, with a fiscal 2026 target above EUR 1.6 billion (Source: Infineon).
- Texas Instruments: Analog segment revenue USD 14.01 billion in 2025; data center revenue up about 95% year on year in the third quarter of 2026 (Source: Texas Instruments).
- Renesas Electronics: multiphase digital power and memory interface products ‘performing strongly’ in the second quarter of 2026 (Source: Renesas).
- Analog Devices: data center is 80% of communications revenue, with power up more than 100% year on year in fiscal third-quarter 2026 (Source: Analog Devices).
- onsemi: expects AI data center revenue to more than double in 2026 (Source: onsemi).
- Alpha and Omega Semiconductor: computing was about half of June-quarter 2026 revenue of USD 170.4 million (Source: AOS).
- SiTime: 2025 revenue USD 326.7 million, up 61%, and owner of the former Renesas timing business since 1 July 2026 (Source: SiTime).
- Rambus: record 2025 product revenue of USD 347.8 million, up 41%, led by DDR5 memory interface chips and PMICs (Source: Rambus).
- Microchip Technology: clocks, power monitors and controllers for server boards.
- STMicroelectronics: power stages and controllers for server and accelerator rails.
- Richtek Technology: multiphase controllers and power stages for Asian server design houses.
- Navitas Semiconductor: gallium nitride drivers and power ICs for 800 V tray conversion.
- Vishay Intertechnology: smart power stages and current-sense parts.
Concentration is highest in power stages and controllers, where MPS and Infineon together hold about 41% of the AI server analog IC market. Analog Devices told analysts in August 2026 that each gigawatt of data center capacity creates a USD 1 billion to USD 1.5 billion analog serviceable addressable market, according to its earnings call, a figure that includes facility and optical content outside this estimate.
Recent Developments: What Changed in AI Server Analog Chips in 2026?
Six AI server analog IC developments between July and October 2026 moved revenue, ownership or demand.
- In October 2026, Rambus reported record third-quarter product revenue of USD 114.3 million, up 22% year on year (Source: Rambus).
- In October 2026, Texas Instruments said data center revenue grew about 95% year on year and reached about 13% of company revenue (Source: Texas Instruments third-quarter 2026 remarks).
- In October 2026, Meta reported third-quarter capital expenditure of USD 34.91 billion and narrowed 2026 guidance to USD 135 billion to USD 145 billion (Source: Meta).
- In August 2026, Infineon raised its fiscal 2026 AI power revenue target to more than EUR 1.6 billion and said it would raise its fiscal 2027 projection (Source: Infineon third-quarter fiscal 2026 statement).
- In August 2026, onsemi said AI data center revenue would more than double in 2026 (Source: onsemi).
- In July 2026, SiTime completed its acquisition of the Renesas timing business, adding more than 550 clocking products (Source: SiTime).
Key Takeaways: What Should Buyers of AI Server Analog ICs Know?
- The AI server analog IC market reaches USD 2.45 billion in 2026 because Blackwell and MI355X boards pass 1,000 W and need 14 to 19 power stages each.
- High-ratio converter controllers and drivers grow 28.57% a year because 800 VDC racks add a 64:1 converter to every tray from 2027.
- Content per kilowatt halves to USD 94.8 by 2035 because each stage carries more current and controllers handle more phases.
- MPS leads with about 27% because its Enterprise Data line is mostly accelerator power stages and controllers.
Research Methodology: How DC Market Insights Sized AI Server Analog ICs
DC Market Insights sized the AI Server Analog IC Market bottom-up at USD 1.36 billion in 2025: board-level conversion value of AI servers of USD 1.80 billion times a 55% silicon share gives USD 990.59 million, and 11.48 million accelerators times USD 32 of timing, interface, sensing and memory PMIC content gives USD 367.36 million. Every year from 2020 to 2035 is modelled the same way, with the silicon share falling to 50% and non-power content rising to USD 40 by 2035. Three bound checks were run:
- Ceiling 1: Analog Devices’ USD 1.0 billion to USD 1.5 billion analog serviceable market per gigawatt times about 4.2 GW of new AI IT capacity in 2025 gives USD 4.2 billion to USD 6.3 billion of all analog content in AI data centers; this estimate is 22% to 32% of that.
- Ceiling 2: the board-level analog content of an NVL72-class rack in this model is about USD 12,000, below the about USD 30,000 of power-tree content that Infineon and onsemi together claim per rack today (about USD 15,000 each).
- Floor: 70% of MPS Enterprise Data revenue (USD 491 million), 30% of SiTime revenue (USD 98 million) and 25% of Rambus product revenue (USD 87 million) add up to USD 676 million, about half of the 2025 estimate.
Regions and countries follow AI accelerator installation shares from the DC Market Insights accelerator model, and server totals reconcile with the AI Server Market. Sources are company filings, results statements, government notices and standards bodies. Full method: DC Market Insights research methodology.
Table of contents
- 01Introduction
- 1.1Report Description
- 1.2Key Market Statistics, 2025, 2026, 2030 and 2035
- 02Executive Summary
- 2.1Market Snapshot, 2025, 2026 and 2035
- 2.2Market Size Chart, 2020-2035
- 03Market Scope
- 3.1Included
- 3.2Excluded
- 3.3How the Segments Fit Together
- 04Why AI Server Analog IC Market Estimates Differ
- 4.1Scope Table: In and Out of This Estimate
- 05Market Drivers
- 5.11,400 W Accelerator Boards Need About 19 Smart Power Stages Each
- 5.2MPS Enterprise Data Revenue Rose 164.3% in the Second Quarter of 2026
- 5.3Hyperscaler Capex Guides of USD 135 Billion to USD 205 Billion for 2026
- 06Market Trends
- 6.1800 V DC Racks from 2027 Create a 64:1 Converter Socket on Every Tray
- 6.2SiTime Closes Its USD 1.5 Billion Purchase of the Renesas Timing Business
- 6.3SOCAMM2 and DDR5 Modules Put More PMICs Next to the Processor
- 07Market Challenges and Restraints
- 7.1China's Anti-Dumping Case on US Analog Chips and the 10 November 2026 Truce Date
- 7.2Analog Content per Kilowatt Falls from USD 188.5 to USD 94.8 by 2035
- 08Market Opportunities
- 8.1High-Ratio Converter Controllers and Drivers: USD 670.33 Million by 2035
- 8.2Tray Power Conversion Stage: From 8% to 17% of Value
- 09Pricing Analysis
- 9.1Analog IC Content per Accelerator and per kW, 2020-2035
- 9.2Supplier Content Anchors per Rack
- 10Standards and Regulation
- 10.1JEDEC JESD301-2 and JESD301-3 (DDR5 PMIC)
- 10.2JEDEC JESD328 (SOCAMM2)
- 10.3OCP Mt Diablo 400 VDC Rack Power
- 10.4US Section 232 Proclamation, January 2026
- 10.5MOFCOM Announcement No. 27 of 2025
- 10.6CHIPS and Science Act Award to Texas Instruments
- 10.7EU State Aid for Infineon Dresden
- 11Market Segmentation
- 11.1By Product Type
- 11.2Multiphase Controllers and Smart Power Stages
- 11.3Protection and Hot-Swap ICs
- 11.4Memory PMICs
- 11.5Timing and Clock ICs
- 11.6Signal Integrity and Interface ICs
- 11.7Sensing and Power Monitoring ICs
- 11.8High-Ratio Converter Controllers and Drivers
- 11.9By Accelerator Platform
- 11.10GPU-Based AI Servers
- 11.11Custom ASIC AI Servers
- 11.12By Board Location
- 11.13Accelerator Module and Baseboard
- 11.14Host CPU and Memory Board
- 11.15Switch and NIC Trays
- 11.16Tray Power Conversion Stage
- 11.17By End User
- 11.18Hyperscale Cloud Providers
- 11.19GPU Cloud and Neocloud Providers
- 11.20Enterprises
- 11.21Government Sovereign AI and Research
- 12DC Exclusive: AI Server Analog Chip Supplier Map, 9 Vendors by Socket
- 12.1Monolithic Power Systems
- 12.2Infineon Technologies
- 12.3Texas Instruments
- 12.4Renesas Electronics
- 12.5Analog Devices
- 12.6onsemi
- 12.7Alpha and Omega Semiconductor
- 12.8SiTime
- 12.9Rambus
- 12.10Others
- 13Regional Insights
- 13.1North America
- 13.2Asia Pacific
- 13.3Europe
- 13.4Middle East and Africa
- 13.5Latin America
- 14Country Analysis
- 14.1United States
- 14.2China
- 14.3Canada
- 14.4Japan
- 14.5South Korea
- 14.6United Kingdom
- 14.7Saudi Arabia
- 14.8Germany
- 14.9India
- 14.10United Arab Emirates
- 14.11Australia
- 14.12France
- 15Forecast Scenarios, 2035
- 15.1Low Scenario
- 15.2Base Scenario
- 15.3High Scenario
- 16Key Players and Market Share
- 16.1Monolithic Power Systems
- 16.2Infineon Technologies
- 16.3Texas Instruments
- 16.4Renesas Electronics
- 16.5Analog Devices
- 16.6onsemi
- 16.7Alpha and Omega Semiconductor
- 16.8SiTime
- 16.9Rambus
- 16.10Microchip Technology
- 16.11STMicroelectronics
- 16.12Richtek Technology
- 16.13Navitas Semiconductor
- 16.14Vishay Intertechnology
- 17Recent Developments
- 17.1Rambus Third-Quarter 2026 Results, October 2026
- 17.2Texas Instruments Data Center Growth, October 2026
- 17.3Meta 2026 Capex Guidance, October 2026
- 17.4Infineon AI Power Target, August 2026
- 17.5onsemi AI Data Center Outlook, August 2026
- 17.6SiTime Completes Renesas Timing Purchase, July 2026
- 18Key Takeaways
- 18.12026 Market Size
- 18.2High-Ratio Converter Controllers and Drivers
- 18.3Content per Kilowatt by 2035
- 18.4Market Leader
- 19Research Methodology
- 19.1Model Inputs
- 19.2Bound Checks
- Fig. 1AI Server Analog IC Market Size, 2020-2035 (USD million)
- Table 1Market Snapshot, 2025, 2026 and 2035
- Table 2Scope Table: In and Out of This Estimate
- Table 3Analog IC Content per Accelerator and per kW, 2020-2035
- Table 4Market by Product Type, 2025 and 2035
- Table 5Market by Accelerator Platform, 2025 and 2035
- Table 6Market by Board Location, 2025 and 2035
- Table 7Market by End User, 2025 and 2035
- Table 8AI Server Analog Chip Supplier Map
- Table 9Top 12 Countries, 2025 and 2035
- Table 102035 Forecast Scenarios
About this report
Written by Amit Jain and reviewed by Deepti Agrawal, Senior Editor, Research. Figures are built top-down and bottom-up and reconciled before publication, with 2025 as the base year.
Read our methodologyHow we built this
- Historical period2020-2024
- Base year2025
- Forecast period2026-2035
- Sizing approachTop-down + bottom-up
Need more than the report?
Advisory on this market
Due diligence, site selection and market entry work, by the analysts who wrote this report.
See consulting servicesFrequently asked questions
USD 2.45 billion in 2026, up 80.7% from USD 1.36 billion in 2025, according to DC Market Insights estimates. The market is projected to reach USD 5.59 billion by 2035, a CAGR of 15.19% from 2025.
15.19% a year from 2025 to 2035, after 75.73% a year from 2020 to 2025, because accelerator shipments flatten after 2028 and analog content per kilowatt of board power falls from USD 188.5 to USD 94.8.
Seven chip families, led by multiphase controllers and smart power stages at 60% of 2025 value. The rest are eFuses and hot-swap ICs, memory PMICs, clocks, redrivers, sensors and power monitors, and 48 V or 800 V converter controllers on the server boards.
About USD 166 per GPU and USD 60 per custom ASIC in 2025 (DC Market Insights estimate). The fleet average rises from USD 118.3 per accelerator in 2025 to USD 191.3 by 2035.
High-ratio converter controllers and drivers, at 28.57% a year, rising from 4% to 12% of value by 2035, because 800 V DC racks add a 64:1 converter to every tray from 2027.
North America, with USD 806.62 million or 59.4% of 2025 value. The Middle East and Africa grows fastest at 19.03% a year, and India is the fastest large country at 22.76%.
Monolithic Power Systems holds about 27% of 2025 value, Infineon Technologies about 14% and Texas Instruments about 10%; the top five hold about 65% (DC Market Insights estimate). MPS Enterprise Data revenue was USD 380.6 million in the second quarter of 2026.
11.1% of 2025 value sits in China, where MOFCOM opened an anti-dumping case on US-made interface and gate-driver analog chips on 13 September 2025. A US-China suspension of certain measures runs until 10 November 2026.
17% of value by 2035 sits in the tray power conversion stage, up from 8% in 2025 (DC Market Insights estimate), because NVIDIA plans 800 V DC power for 1 MW racks from 2027.
USD 2.45 billion in 2026 is the DC Market Insights value of board-level analog and mixed-signal chips in AI servers only. Estimates that add power shelf semiconductors, optical analog front ends, retimers or analog chips in all servers come out larger.
Get this report
How do I get the full report?
Request a quote; we reply by email within one business day.
How and when will I receive the report?
By email, within 24–48 business hours of payment.
How can I pay?
Once you accept the quote, we email you a secure payment link.
Can I see a sample first?
Yes. Request a free sample and we will email it to you.
Can the report be tailored to my needs?
Yes. We can add countries, segments or data cuts. Talk to an analyst about the scope you need.
Can I get an invoice or pay against a purchase order?
Write to sales@dcmarketinsights.com and our team will help.