
AI Server Power Modules Market Size, Share & Forecast to 2035
Market at a glance
The AI Server Power Modules market was worth USD 1,800.0 million in 2025 and is forecast to reach USD 8,840.0 million by 2035, growing at a 17.24% CAGR.
 By Amit Jain, Senior Consultant, ICT & Emerging Technologies
 Reviewed by Deepti Agrawal
Last updated 22 Oct 2026
Base year 2025 PDF + Excel
Key findings
Board Power Rising from 700 W (H100) to 1,400 W (MI355X)
800 V Racks from 2027 Remove the 54 V Shelf
VPD Modules: USD 3.36 billion by 2035
What is inside the report
- 01Introduction
- 02Executive Summary
- 03Market Scope
- 04Why Market Estimates Differ
- 05Market Drivers
- 06Market Trends
- 07Market Challenges and Restraints
- 08Market Opportunities
- 09Pricing Analysis
- 10Standards and Regulation
- 19chapters
- 2020-2024Historical period
- 2026-2035Forecast period
- —Companies profiled
Segmentation
Full analysis
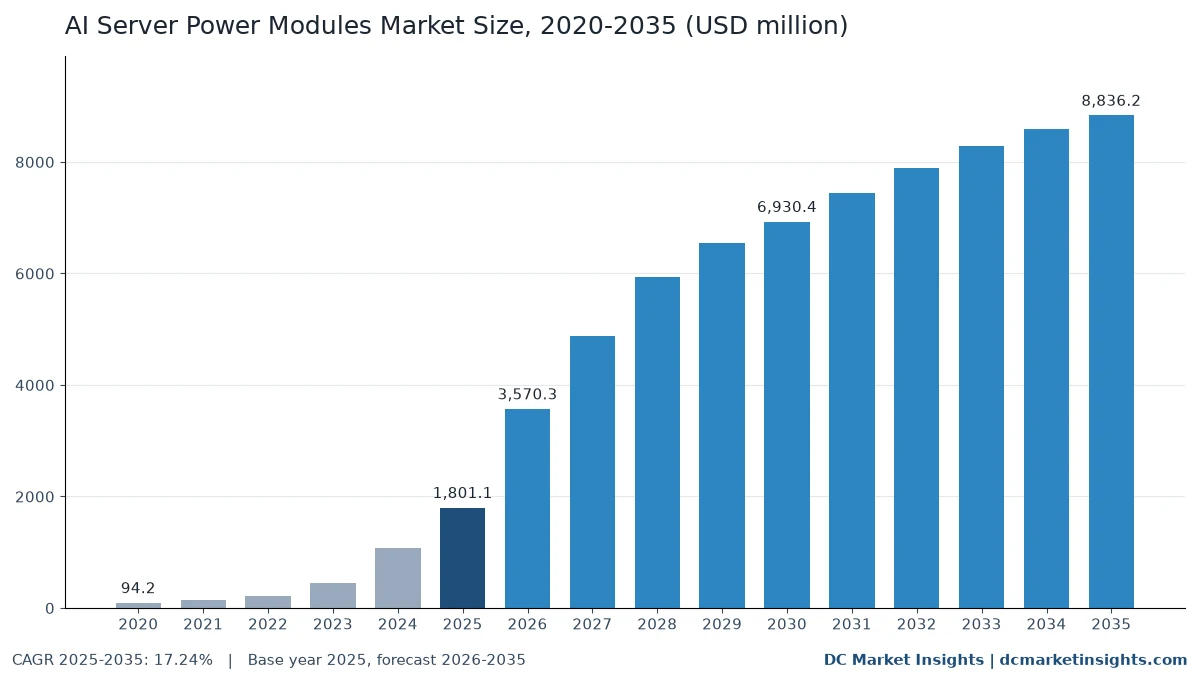
The AI Server Power Modules Market is valued at USD 3.57 billion in 2026 and is projected to reach USD 8.84 billion by 2035, up from USD 1.80 billion in 2025, a CAGR of 17.24% from 2025 to 2035 (DC Market Insights estimate). Current, not unit count, sets the money here: a 1,000 watt (W) accelerator running its core near 0.8 volts (V) draws about 1,000 amperes (A), so every jump in board power adds power stages, phases and converter bricks to the tray. Monolithic Power Systems (MPS) shows how fast this moved: its Enterprise Data revenue reached USD 380.6 million in the second quarter of 2026, up 164.3% on a year earlier, on sales of power management for AI and server applications (MPS second-quarter 2026 results, July 2026). DC Market Insights builds the 2025 figure from 11.48 million AI accelerators shipped, about USD 212 of board-level conversion content per graphics processing unit (GPU) and USD 89 per custom accelerator, giving USD 1.80 billion. Vertical power delivery modules grow fastest, at 51.13% a year, and the Middle East and Africa is the fastest region at 21.15% a year as Saudi Arabia and the United Arab Emirates (UAE) fill new AI campuses.
Key Market Statistics: How Big Is the AI Server Power Modules Market in 2026?
DC Market Insights values the AI Server Power Modules Market at USD 3.57 billion in 2026, 98.23% above 2025, because accelerator shipments rise from 11.48 million to 16.20 million while average GPU board power climbs from about 850 W to 1,150 W.
- Market size 2025: USD 1.80 billion; 2026: USD 3.57 billion; 2030: USD 6.93 billion; 2035: USD 8.84 billion.
- CAGR 2025-2035: 17.24% in the base case; the 2035 range runs from USD 6.36 billion (low, 13.45%) to USD 11.13 billion (high, 19.98%).
- Content per accelerator: about USD 157 on average in 2025, rising to USD 248 by 2035 (DC Market Insights estimate).
- Largest product type: multiphase voltage regulator (VR) power stages and controllers, USD 1.04 billion or 58.0% of 2025 value.
- Fastest product type: vertical power delivery (VPD) modules, from USD 54.03 million in 2025 to USD 3.36 billion by 2035.
- Fastest input class: 48 V to 54 V input, 20.50% a year; 800 V direct input reaches USD 1.94 billion by 2035 from zero in 2025.
- Custom application-specific integrated circuit (ASIC) servers grow 20.44% a year, against 15.93% for GPU servers.
- Leading region: North America, USD 1.07 billion (59.4%) in 2025; fastest region: Middle East and Africa, 21.15% a year.
- Largest country: United States, USD 986.99 million in 2025; fastest large country: India, 24.94% a year.
- Market leaders: MPS and Infineon Technologies, each with about a quarter of 2025 value; the top five suppliers hold about 74% (DC Market Insights estimate).
Executive Summary: How Fast Is Spending on AI Server Power Modules Growing?
The Global AI Server Power Modules Market size was valued at USD 94.20 million in 2020, reached USD 1.80 billion in 2025, and is anticipated to reach USD 8.84 billion by 2035, at a CAGR of 17.24% during the forecast period.
| Attribute | Value |
|---|---|
| Historical period | 2020-2024 |
| Base year | 2025 |
| Forecast period | 2026-2035 |
| Market size 2025 | USD 1.80 billion |
| Market size 2026 | USD 3.57 billion |
| CAGR 2025-2035 | 17.24% |
| Market size 2035 | USD 8.84 billion |
Spending grew 80.42% a year from 2020 to 2025 because AI accelerator shipments rose from about 0.9 million to 11.48 million and board power per GPU more than doubled, from about 400 W for the A100 generation to 1,000 W for a B200 in a DGX B200 system. Growth slows to 17.24% a year to 2035: unit shipments flatten after 2028, and the price per watt of conversion falls from USD 0.250 to USD 0.150 as power stages integrate into modules. The 2026 step of 98.23% is the steepest of the decade; Infineon Technologies said on 5 August 2026 that it expects more than EUR 1.6 billion of dedicated AI power revenue in its fiscal year 2026 and that it is in allocation (Infineon third-quarter FY2026 analyst call, August 2026).
What Counts as an AI Server Power Module?
AI server power modules were a USD 1.80 billion market in 2025, counting only board-level conversion inside AI servers.
The market covers direct current to direct current (DC-DC) conversion bought for AI accelerator trays, AI server host boards and AI switch trays, valued at the module or component maker’s selling price.
Included: multiphase VR controllers and smart power stages (driver plus MOSFET in one package) for GPU, ASIC, high bandwidth memory (HBM) and input-output rails; vertical and dual-phase power modules mounted under or beside the processor; 48 V to 12 V and 48 V to 6 V intermediate bus converters (IBCs); 800 V to 12 V or 6 V on-board converters from 2027; point-of-load (PoL) modules for central processing unit (CPU), network interface and switch rails.
Excluded: alternating current to direct current power supply units and rack power shelves, which DC Market Insights covers in the Data Center Power Supply Unit Market; 800 V rack power and sidecars, covered in the Data Center High-Voltage Direct Current (HVDC) Market; battery backup units, uninterruptible power supplies, power distribution units, busbars, and power devices sold for general servers without accelerators.
How the segments fit together: every dollar sits once in each dimension: product type (USD 1.04 billion VR, USD 432.26 million IBC, USD 270.16 million PoL and USD 54.03 million VPD in 2025), input voltage, accelerator platform and device technology; regions and countries follow where the AI servers are installed.
Why Do AI Server Power Module Market Estimates Differ?
AI server power module estimates differ by boundary; DC Market Insights puts the market at USD 3.57 billion in 2026.
Broader definitions add the AC-DC power supplies and 54 V power shelves at the top of the rack, discrete power semiconductors sold for any server, telecom and industrial DC-DC bricks, or all data center power electronics, and those totals can be several times larger. Narrower definitions count only vertical power modules or only GPU core regulators and land well under USD 1 billion for 2025. DC Market Insights counts the conversion chain from the 48 V or 54 V tray input, and from 2027 the 800 V input, down to the processor rail, including the controller and the power stages even when they are sold as separate chips rather than as one module. Enterprise and smaller AI buyers, such as neoclouds and university clusters, are in scope through the servers they buy.
| Element | In this report | Why |
|---|---|---|
| VR controllers and smart power stages | Yes, USD 1.04 billion in 2025 | They are the core-rail power stage on every accelerator board |
| Vertical power delivery modules | Yes, USD 54.03 million in 2025 | Same function, mounted under the processor |
| 48 V and 800 V intermediate bus converters on the tray | Yes, USD 432.26 million in 2025 | First board-level conversion step |
| AC-DC power supplies and power shelves | No | Rack-level product, covered in a separate report |
| Battery backup units and UPS | No | Energy storage, not conversion to the processor |
| General server and telecom DC-DC | No | No AI accelerator on the board |
Market Drivers: Why Do AI Chips Need More Power Conversion Every Year?
Three forces add USD 7.04 billion to the market between 2025 and 2035: rising amps per accelerator, the move of conversion closer to the die, and the 800 V rack.
Board Power Rising from 700 W (H100) to 1,400 W (MI355X)
NVIDIA lists the H100 SXM at up to 700 W; NVIDIA’s DGX B200 user guide gives 1,000 W per GPU, and AMD’s datasheet gives the Instinct MI355X a maximum board power of 1,400 W. At about 0.8 V, a 1,400 W part needs about 1,400 A on its core rail, or about 20 smart power stages rated at 90 A running at 80% load, against about 10 for an H100. DC Market Insights estimates average GPU board power for units shipped at 850 W in 2025 and 1,900 W by 2030, which lifts conversion content per GPU from USD 212 to USD 361.
Allocation at Infineon and a 164% Jump at MPS in 2026
Supply is the binding constraint in 2026. Infineon said in August 2026 that it has signed capacity reservation agreements worth a high single-digit EUR billion amount over several years with prepayments, and that it will raise its EUR 2.5 billion fiscal 2027 AI data center target in November 2026. MPS guided third-quarter 2026 revenue to USD 1.14 billion to USD 1.16 billion after Enterprise Data revenue of USD 262.8 million in the first quarter and USD 380.6 million in the second. Those two suppliers alone show why DC Market Insights puts 2026 growth at 98.23%.
Vertical Power Delivery Moving Under the Processor
Lateral power stages beside the package lose power in the board copper as currents pass 1,000 A, so module makers are moving the stage under the processor. Vicor reported third-quarter 2026 revenue of USD 197.1 million and a USD 406 million backlog, and said it granted its first VPD licence to an AI original equipment manufacturer (OEM) at Stage-2 unit royalty rates (Vicor third-quarter 2026 results, October 2026). DC Market Insights expects Vertical Power Delivery Modules to take 38.0% of the market by 2035, against 3.0% in 2025.
Market Trends: Which Design Shifts Reshape AI Server Power Modules?
Three trends move about USD 5.66 billion of 2035 AI server power module value into product classes that barely existed in 2025.
800 V Racks from 2027 Remove the 54 V Shelf
NVIDIA wrote on 20 May 2025 that 54 V in-rack power hits its limits above 200 kilowatt (kW) racks and that 800 V direct current (VDC) power for 1 megawatt racks starts in 2027, with DC-DC conversion in the compute rack down to 12 V for the GPUs (NVIDIA technical blog, May 2025). NVIDIA also said the change cuts copper by up to 45% and lifts end-to-end efficiency by up to 5%. For this market it means a new high-ratio converter on each tray: DC Market Insights models 800 V Direct Input at 1% of value in 2027, 10% in 2030 and 22.0% in 2035.
Gallium Nitride in the First Conversion Stage
Infineon told analysts in August 2026 that it pairs gallium nitride (GaN) for dense, high-frequency intermediate stages with silicon at the processor. Renesas Electronics began sampling a 650 V GaN field-effect transistor in a dual-side-cooled 8 x 8 millimetre package for 800 V intermediate stages on 30 September 2026. DC Market Insights puts Gallium Nitride Devices at USD 72.04 million in 2025 and USD 1.77 billion by 2035, 37.71% a year.
Integrated Voltage Regulators Change Who Captures the Value
Analog Devices said on 19 May 2026 that it agreed to buy Empower Semiconductor, a maker of integrated voltage regulators for AI processors, for USD 1.5 billion in cash, and onsemi completed the purchase of Vcore power technology rights from Aura Semiconductor on 27 October 2025. DC Market Insights puts Integrated Voltage Regulators and Other at 22.0% of 2035 value, against 10.0% in 2025.
Market Challenges and Restraints: What Slows AI Server Power Module Spending?
Price erosion and patent risk could take about USD 2.47 billion off the 2035 base case, the gap between the base and low scenarios.
Price per Watt Falling 40% in Ten Years
DC Market Insights models conversion content falling from USD 0.250 per W in 2025 to USD 0.150 in 2035 as dual-phase and quad-phase modules replace discrete stages and Chinese suppliers qualify. A 90 A smart power stage such as Infineon’s TDA21490 lists at about EUR 2.34 on a 5,000-unit reel at a European distributor, so a 20-stage GPU rail costs under EUR 50 in stages before the controller and inductors.
Vertical Power Patent Dispute at the US International Trade Commission
According to the US International Trade Commission, it instituted investigation 337-TA-1526 into vertical power delivery systems on 9 October 2026 on a complaint by Vicor, which named module makers and server assemblers including Delta Electronics, Infineon, MPS, Flex and Luxshare. An exclusion order would hit USD 512.91 million of 2027 VPD spending modelled by DC Market Insights, and the low scenario assumes a two-year delay in VPD adoption.
Market Opportunities: Which AI Server Power Module Classes Add the Most Value?
The two largest AI server power module openings are worth USD 5.30 billion together by 2035.
VPD Modules: USD 3.36 billion by 2035
Vertical Power Delivery Modules grow from USD 54.03 million in 2025 to USD 3.36 billion by 2035 in the DC Market Insights base case. Infineon’s TDM24745T quad-phase module puts four power stages, a trans-inductor voltage regulator (TLVR) inductor and capacitors in 9 x 10 millimetres; suppliers that pair such modules with a licence position under the Vicor patents win this segment.
800 V Tray Converters: USD 1.94 billion by 2035
800 V Direct Input reaches USD 1.94 billion by 2035. Navitas Semiconductor showed an 800 V to 6 V power delivery board at NVIDIA GTC in March 2026 that removes the 48 V intermediate stage, and Texas Instruments’ LMM104RM0 1.6 kW 48 V to 12 V regulated converter shows the density level the 800 V parts must beat.
Pricing Analysis: How Much Does Power Conversion Cost per AI Accelerator?
AI server power modules cost about USD 212 per GPU in 2025 (DC Market Insights estimate).
That compares with USD 89 per custom ASIC and an average USD 0.250 per W of board power.
| Year | GPU board power (fleet average) | Content per W | Content per GPU | Content per custom ASIC |
|---|---|---|---|---|
| 2020 | 400 W | USD 0.320 | USD 128 | USD 68 |
| 2025 | 850 W | USD 0.250 | USD 212 | USD 89 |
| 2026 | 1,150 W | USD 0.270 | USD 310 | USD 118 |
| 2030 | 1,900 W | USD 0.190 | USD 361 | USD 145 |
| 2035 | 2,400 W | USD 0.150 | USD 360 | USD 153 |
Public price anchors are thin because hyperscalers and server makers buy under contract. The best public anchor is distributor pricing for a 90 A stage: about EUR 4.30 for a single Infineon TDA21490 and EUR 2.34 on a 5,000-unit reel. Content per W rose in 2026, to USD 0.270, because Infineon and MPS were supply-limited and because 2026 boards mix early VPD modules with lateral stages; DC Market Insights expects the decline to resume from 2027.
Which Specifications, Efficiency Laws and Tariffs Govern AI Server Power Modules?
Six named rules shape AI server power modules, a USD 3.57 billion market in 2026.
They cover rack voltage, the power management bus, server efficiency law and US and Chinese trade measures.
The Open Compute Project (OCP) Open Rack V3 specification defines the 48 V busbar that feeds most AI trays today, and the GB200 NVL72 busbar NVIDIA contributed to OCP carries 1,400 A. GPU VR controllers such as the MPS MP2891 report telemetry over the Power Management Bus (PMBus) 1.3. European Union Ecodesign Regulation (EU) 2019/424 sets server power supply efficiency of 96% at 50% load from January 2023, which pushes losses down the chain to the board converters. ENERGY STAR Computer Servers Version 4.0 applies to servers made from 12 January 2024. In trade, the US Department of Commerce opened a Section 232 investigation into semiconductors on 1 April 2025, and a proclamation of 14 January 2026 set a 25% duty on certain advanced computing chips with exemptions that include chips for US data centers (White House proclamation, January 2026). China’s Ministry of Commerce (MOFCOM) Announcement No. 46 of December 2024 restricted gallium exports to the United States; the ban is suspended until 27 November 2026, a risk for GaN stages.
Market Segmentation: Which AI Server Power Module Types Take the Most Spend?
Multiphase VR Power Stages and Controllers lead AI server power modules with USD 1.04 billion in 2025.
By Product Type
VR stages and controllers hold 58.0% in 2025 but grow only 6.88% a year as VPD modules, at 51.13%, take the core rail. IBCs grow 18.63% a year as every tray gains converters.
| Product type | 2025 (USD million) | Share 2025 | 2035 (USD million) | CAGR 2025-2035 |
|---|---|---|---|---|
| Multiphase VR Power Stages and Controllers | USD 1,044.62 million | 58.0% | USD 2,032.33 million | 6.88% |
| Vertical Power Delivery Modules | USD 54.03 million | 3.0% | USD 3,357.76 million | 51.13% |
| Intermediate Bus Converters | USD 432.26 million | 24.0% | USD 2,385.77 million | 18.63% |
| Point-of-Load and Auxiliary Rail Modules | USD 270.16 million | 15.0% | USD 1,060.34 million | 14.65% |
By Input Voltage
12 V input parts still carry 62.0% of 2025 value; 48 V to 54 V input grows 20.50% a year and 800 V direct input appears in 2027.
| Input voltage | 2025 (USD million) | Share 2025 | 2035 (USD million) | CAGR 2025-2035 |
|---|---|---|---|---|
| 12 V Input | USD 1,116.67 million | 62.0% | USD 2,474.14 million | 8.28% |
| 48 V to 54 V Input | USD 684.40 million | 38.0% | USD 4,418.10 million | 20.50% |
| 800 V Direct Input | USD 0.00 million | 0.0% | USD 1,943.96 million | new from 2027 |
By Accelerator Platform
GPU servers account for 74.3% of 2025 value; custom ASIC servers grow faster, 20.44% a year, as Google, Amazon Web Services and Meta add their own accelerators.
| Accelerator platform | 2025 (USD million) | Share 2025 | 2035 (USD million) | CAGR 2025-2035 |
|---|---|---|---|---|
| GPU-Based AI Servers | USD 1,338.76 million | 74.3% | USD 5,868.00 million | 15.93% |
| Custom ASIC AI Servers | USD 462.31 million | 25.7% | USD 2,968.20 million | 20.44% |
By Device Technology
Silicon MOSFET stages hold 86.0% of 2025 value; GaN devices grow 37.71% a year, mostly in 48 V and 800 V converters.
| Device technology | 2025 (USD million) | Share 2025 | 2035 (USD million) | CAGR 2025-2035 |
|---|---|---|---|---|
| Silicon MOSFET Power Stages | USD 1,548.92 million | 86.0% | USD 5,125.00 million | 12.71% |
| Gallium Nitride Devices | USD 72.04 million | 4.0% | USD 1,767.24 million | 37.71% |
| Integrated Voltage Regulators and Other | USD 180.11 million | 10.0% | USD 1,943.96 million | 26.86% |
DC Exclusive: Amps-per-Accelerator Teardown, About 20 Power Stages for a 1,400 W Chip
AI server power modules per GPU rise from about USD 128 (A100 class) to USD 360 (2035 fleet).
The Amps-per-Accelerator Teardown is a DC Market Insights model built on 7 inputs: vendor board power, core voltage, stage rating, load factor and the content per W series.
| Accelerator class | Board power | Core-rail current (approx.) | 90 A stages at 80% load | Content per W | Conversion content per accelerator |
|---|---|---|---|---|---|
| NVIDIA A100 SXM class (2020) | 400 W | 400 A | 6 | USD 0.320 | USD 128 |
| NVIDIA H100 SXM (2023) | 700 W | 700 A | 10 | USD 0.305 | USD 214 |
| AMD Instinct MI300X (2024) | 750 W | 750 A | 10 | USD 0.300 | USD 225 |
| NVIDIA B200 in DGX B200 (2025) | 1,000 W | 1,000 A | 14 | USD 0.250 | USD 250 |
| AMD Instinct MI355X (2025) | 1,400 W | 1,400 A | 19 | USD 0.250 | USD 350 |
| Fleet average, units shipped 2030 | 1,900 W | 1,900 A | 26 | USD 0.190 | USD 361 |
| Fleet average, units shipped 2035 | 2,400 W | 2,400 A | 33 | USD 0.150 | USD 360 |
The teardown assumes about 80% of board power sits on the core rail at about 0.8 V and that each 90 A stage runs at 80% of its rating; HBM, input-output and host rails take the rest. Two readings follow. First, stage count roughly tracks board power, so the 2,400 W fleet average of 2035 needs about 33 stage-equivalents, three times an H100. Second, content per accelerator rises far less than current, from about USD 212 to about USD 360 between 2025 and 2035, because integration lowers the price per W by 40%.
Regional Insights: Where Are AI Server Power Modules Installed?
North America leads with USD 1.07 billion, 59.4% of 2025 value by place of installation, and the Middle East and Africa grows fastest at 21.15% a year.
North America
North America grows from USD 1.07 billion in 2025 to USD 4.86 billion by 2035, 16.34% a year, as the large US cloud operators install most GB200 and GB300 racks; the United States alone is USD 986.99 million in 2025.
Asia Pacific
Asia Pacific grows from USD 443.06 million to USD 2.26 billion, 17.71% a year. Most modules are assembled into trays in Taiwan and mainland China, but DC Market Insights counts value where servers are installed: China at USD 199.92 million and India, the fastest large country, at 24.94% a year.
Europe
Europe grows from USD 165.70 million to USD 883.62 million, 18.22% a year, led by the United Kingdom at USD 41.42 million and Germany at USD 32.42 million in 2025.
Middle East and Africa
The Middle East and Africa rises from USD 88.25 million to USD 600.86 million, 21.15% a year, the fastest of the five regions, with Saudi Arabia at 21.63% and the UAE at 21.57% a year.
Latin America
Latin America is the smallest region, USD 34.22 million in 2025, and grows 20.98% a year to USD 229.74 million by 2035 as Brazil and Mexico add AI halls.
Which Countries Spend Most on AI Server Power Modules?
The United States leads AI server power module spending with USD 986.99 million in 2025, 54.8% of the market, and India is the fastest large country at 24.94% a year.
| Rank | Country | Region | 2025 (USD million) | 2035 (USD million) | CAGR 2025-2035 |
|---|---|---|---|---|---|
| 1 | United States | North America | USD 986.99 million | USD 4,453.45 million | 16.26% |
| 2 | China | Asia Pacific | USD 199.92 million | USD 795.26 million | 14.81% |
| 3 | Canada | North America | USD 82.85 million | USD 406.46 million | 17.24% |
| 4 | Japan | Asia Pacific | USD 63.04 million | USD 300.43 million | 16.90% |
| 5 | South Korea | Asia Pacific | USD 41.42 million | USD 220.91 million | 18.22% |
| 6 | United Kingdom | Europe | USD 41.42 million | USD 203.23 million | 17.24% |
| 7 | India | Asia Pacific | USD 32.42 million | USD 300.43 million | 24.94% |
| 8 | Saudi Arabia | Middle East and Africa | USD 32.42 million | USD 229.74 million | 21.63% |
| 9 | Germany | Europe | USD 32.42 million | USD 167.89 million | 17.87% |
| 10 | United Arab Emirates | Middle East and Africa | USD 28.82 million | USD 203.23 million | 21.57% |
| 11 | Australia | Asia Pacific | USD 27.02 million | USD 141.38 million | 18.00% |
| 12 | France | Europe | USD 23.41 million | USD 132.54 million | 18.93% |
China’s 14.81% a year is below the global rate because US export rules limit the highest-power accelerators it can buy; its domestic accelerators run at lower board power, which means less conversion content per chip.
Forecast Scenarios: How Large Could AI Server Power Modules Be by 2035?
DC Market Insights puts AI server power modules in 2035 between USD 6.36 billion and USD 11.13 billion, with USD 8.84 billion as the base case.
| Scenario | 2035 (USD million) | CAGR 2025-2035 | Main assumption |
|---|---|---|---|
| Low | USD 6,362.06 million | 13.45% | Accelerator units flat after 2028 and VPD adoption delayed two years |
| Base | USD 8,836.20 million | 17.24% | 35.7 million accelerators in 2035 at 2,400 W per GPU |
| High | USD 11,133.61 million | 19.98% | Board power reaches 3,000 W per GPU and 800 V trays take 35% of value |
Who Are the Leading AI Server Power Module Suppliers?
MPS and Infineon each hold about 25% of 2025 value, and the top five suppliers about 74% (DC Market Insights estimate based on company disclosures).
- Monolithic Power Systems
- Infineon Technologies
- Vicor
- Renesas Electronics
- Delta Electronics
- Texas Instruments
- Analog Devices
- onsemi
- Alpha and Omega Semiconductor
- Flex
- Murata Manufacturing
- Navitas Semiconductor
- Luxshare Precision
- Empower Semiconductor
MPS reported 2025 revenue of USD 2.8 billion, up 26.4%, with Enterprise Data at USD 701.8 million; DC Market Insights attributes about USD 450 million of that, 25% of this market, to AI accelerator boards. Infineon gives the largest disclosed AI power figure, more than EUR 1.6 billion in fiscal 2026, but that includes power supplies and silicon carbide, so DC Market Insights counts only its board-level share, about 24% of 2025 value. Vicor’s 2025 revenue was USD 452.7 million, including a USD 45 million patent settlement, and its royalties grow with VPD. Renesas and Delta Electronics complete the top five at about 7% and 6%. Texas Instruments, Analog Devices and onsemi are building positions through new modules and acquisitions, and Murata showed its MYC0409 48 V divide-by-four module for AI hardware at PCIM in May 2026. The AI Server Market report covers the server makers that buy these parts, and the Data Center Accelerator Market report gives the unit base used here.
What Has Happened Recently in AI Server Power Modules?
Six dated AI server power module events since October 2025 point to tighter supply and a fight over vertical power.
- In October 2026, Vicor reported third-quarter revenue of USD 197.1 million, a USD 406 million backlog and its first VPD licence to an AI OEM, and bought two more sites for ChiP fabs (Source: Vicor).
- In October 2026, the US International Trade Commission instituted investigation 337-TA-1526 into vertical power delivery systems (Source: US International Trade Commission).
- In September 2026, Renesas Electronics began sampling a 650 V GaN transistor for 800 V intermediate bus converters (Source: Renesas Electronics).
- In August 2026, Infineon raised its fiscal 2026 AI power revenue outlook to more than EUR 1.6 billion and reported multi-year capacity reservation deals (Source: Infineon Technologies).
- In May 2026, Analog Devices agreed to buy Empower Semiconductor for USD 1.5 billion in cash (Source: Analog Devices).
- In October 2025, onsemi completed its purchase of Vcore power technology from Aura Semiconductor (Source: onsemi).
Key Takeaways
Four AI server power module findings matter most, starting from a USD 3.57 billion market in 2026.
- 2026 market size: USD 3.57 billion, up 98.23%, because accelerator units rise 41% and GPU board power rises 35% in the same year.
- Vertical Power Delivery Modules reach USD 3.36 billion by 2035, because lateral stages lose too much power in board copper above 1,000 A.
- 800 V Direct Input reaches USD 1.94 billion by 2035, because NVIDIA’s 800 VDC racks from 2027 need a new converter on every tray.
- Content per W falls 40% to USD 0.150 by 2035, because power stages integrate into dual-phase and quad-phase modules.
Research Methodology: How Did DC Market Insights Size the AI Server Power Modules Market?
DC Market Insights sized AI server power modules bottom-up at USD 1.80 billion for 2025.
The receipt: 11.48 million accelerators, 6.30 million GPUs at 850 W and 5.18 million custom ASICs at 420 W, times USD 0.250 of conversion content per W (15% lower for ASIC boards). Unit shipments come from the DC Market Insights accelerator model. GPUs: 6.30 million x 850 W x USD 0.250 = USD 1,338.76 million; custom ASICs: 5.18 million x 420 W x USD 0.2125 = USD 462.31 million; total USD 1,801.07 million.
Three bound checks hold. First ceiling: USD 1.80 billion is 0.93% of NVIDIA’s USD 193.7 billion data center revenue for fiscal 2026, against a bill-of-materials share of about 1% for board power in published teardowns of GPU servers. Second ceiling: the sum of MPS Enterprise Data (USD 701.8 million), Vicor (USD 452.7 million) and Infineon’s board-level AI share stays within twice the 2025 estimate, even though part of each figure is non-AI. Floor: MPS’s AI share and Vicor’s product revenue alone give about USD 0.80 billion in 2025, so the market cannot be under USD 0.8 billion. Full method notes are on the research methodology page.
Table of contents
- 01Introduction
- 1.1Report Description
- 1.2Key Market Statistics, 2025, 2026, 2030 and 2035
- 02Executive Summary
- 2.1Market Snapshot, 2025, 2026 and 2035
- 2.2Market Size Chart, 2020-2035
- 03Market Scope
- 3.1Included
- 3.2Excluded
- 3.3How the Segments Fit Together
- 04Why Market Estimates Differ
- 4.1Scope Table: In and Out of This Estimate
- 05Market Drivers
- 5.1Board Power Rising from 700 W (H100) to 1,400 W (MI355X)
- 5.2Allocation at Infineon and a 164% Jump at MPS in 2026
- 5.3Vertical Power Delivery Moving Under the Processor
- 06Market Trends
- 6.1800 V Racks from 2027 Remove the 54 V Shelf
- 6.2Gallium Nitride in the First Conversion Stage
- 6.3Integrated Voltage Regulators Change Who Captures the Value
- 07Market Challenges and Restraints
- 7.1Price per Watt Falling 40% in Ten Years
- 7.2Vertical Power Patent Dispute at the US International Trade Commission
- 08Market Opportunities
- 8.1VPD Modules: USD 3.36 billion by 2035
- 8.2800 V Tray Converters: USD 1.94 billion by 2035
- 09Pricing Analysis
- 9.1Conversion Content per Accelerator, 2020-2035
- 9.2Power Stage Price Anchors
- 10Standards and Regulation
- 10.1OCP Open Rack V3
- 10.2PMBus 1.3
- 10.3Ecodesign Regulation (EU) 2019/424
- 10.4ENERGY STAR Computer Servers Version 4.0
- 10.5Section 232 Semiconductors Proclamation, January 2026
- 10.6MOFCOM Announcement No. 46 (Gallium)
- 11Market Segmentation
- 11.1By Product Type
- 11.2Multiphase VR Power Stages and Controllers
- 11.3Vertical Power Delivery Modules
- 11.4Intermediate Bus Converters
- 11.5Point-of-Load and Auxiliary Rail Modules
- 11.6By Input Voltage
- 11.712 V Input
- 11.848 V to 54 V Input
- 11.9800 V Direct Input
- 11.10By Accelerator Platform
- 11.11GPU-Based AI Servers
- 11.12Custom ASIC AI Servers
- 11.13By Device Technology
- 11.14Silicon MOSFET Power Stages
- 11.15Gallium Nitride Devices
- 11.16Integrated Voltage Regulators and Other
- 12DC Exclusive: Amps-per-Accelerator Teardown
- 12.1NVIDIA A100 SXM class (2020)
- 12.2NVIDIA H100 SXM (2023)
- 12.3AMD Instinct MI300X (2024)
- 12.4NVIDIA B200 in DGX B200 (2025)
- 12.5AMD Instinct MI355X (2025)
- 12.6Fleet average, units shipped 2030
- 12.7Fleet average, units shipped 2035
- 13Regional Insights
- 13.1North America
- 13.2Asia Pacific
- 13.3Europe
- 13.4Middle East and Africa
- 13.5Latin America
- 14Country Analysis
- 14.1United States
- 14.2China
- 14.3Canada
- 14.4Japan
- 14.5South Korea
- 14.6United Kingdom
- 14.7India
- 14.8Saudi Arabia
- 14.9Germany
- 14.10United Arab Emirates
- 14.11Australia
- 14.12France
- 15Forecast Scenarios, 2035
- 15.1Low Scenario
- 15.2Base Scenario
- 15.3High Scenario
- 16Competitive Insights
- 16.1Monolithic Power Systems
- 16.2Infineon Technologies
- 16.3Vicor
- 16.4Renesas Electronics
- 16.5Delta Electronics
- 16.6Texas Instruments
- 16.7Analog Devices
- 16.8onsemi
- 16.9Alpha and Omega Semiconductor
- 16.10Flex
- 16.11Murata Manufacturing
- 16.12Navitas Semiconductor
- 16.13Luxshare Precision
- 16.14Empower Semiconductor
- 17Recent Developments
- 17.1Vicor Third-Quarter Results and First VPD Licence, October 2026
- 17.2USITC Investigation 337-TA-1526, October 2026
- 17.3Renesas 650 V GaN Sampling, September 2026
- 17.4Infineon AI Power Outlook, August 2026
- 17.5Analog Devices to Acquire Empower Semiconductor, May 2026
- 17.6onsemi Vcore Technology Purchase, October 2025
- 18Key Takeaways
- 18.12026 Market Size
- 18.2Vertical Power Delivery Modules by 2035
- 18.3800 V Direct Input by 2035
- 18.4Content per W by 2035
- 19Research Methodology
- 19.1Model Inputs
- 19.2Bound Checks
- Fig. 1AI Server Power Modules Market Size, 2020-2035 (USD million)
- Table 1Market Snapshot, 2025, 2026 and 2035
- Table 2Scope Table: In and Out of This Estimate
- Table 3Conversion Content per Accelerator, 2020-2035
- Table 4Market by Product Type, 2025 and 2035
- Table 5Market by Input Voltage, 2025 and 2035
- Table 6Market by Accelerator Platform, 2025 and 2035
- Table 7Market by Device Technology, 2025 and 2035
- Table 8Amps-per-Accelerator Teardown
- Table 9Top 12 Countries, 2025 and 2035
- Table 102035 Forecast Scenarios
About this report
Written by Amit Jain and reviewed by Deepti Agrawal, Senior Editor, Research. Figures are built top-down and bottom-up and reconciled before publication, with 2025 as the base year.
Read our methodologyHow we built this
- Historical period2020-2024
- Base year2025
- Forecast period2026-2035
- Sizing approachTop-down + bottom-up
Need more than the report?
Advisory on this market
Due diligence, site selection and market entry work, by the analysts who wrote this report.
See consulting servicesFrequently asked questions
USD 3.57 billion in 2026, up 98.23% from USD 1.80 billion in 2025, according to DC Market Insights estimates. The market is projected to reach USD 8.84 billion by 2035, a CAGR of 17.24% from 2025.
17.24% a year from 2025 to 2035, after 80.42% a year from 2020 to 2025, because accelerator shipments flatten after 2028 and the price per watt of conversion falls from USD 0.250 to USD 0.150.
It is a board-level DC-DC converter or power stage that steps 48 V, 54 V or, from 2027, 800 V tray power down to the 0.8 V core rail of an AI accelerator. Multiphase VR stages and controllers were 58.0% of 2025 value.
About USD 212 per GPU and USD 89 per custom ASIC in 2025 (DC Market Insights estimate), rising to about USD 360 per GPU by 2035 as board power climbs toward 2,400 W.
About 14 smart power stages of 90 A running at 80% load for a 1,000 A core rail, and about 20 for a 1,400 W part such as the AMD Instinct MI355X, before HBM and input-output rails (DC Market Insights teardown).
Vertical power delivery modules, from USD 54.03 million in 2025 to USD 3.36 billion by 2035, 51.13% a year, because mounting the stage under the processor cuts board losses above 1,000 A.
NVIDIA plans 800 V DC racks from 2027, which adds an 800 V to 12 V or 6 V converter on each tray. DC Market Insights puts 800 V direct-input modules at USD 1.94 billion by 2035.
North America, with USD 1.07 billion or 59.4% of 2025 value by installation. The Middle East and Africa grows fastest at 21.15% a year, and India is the fastest large country at 24.94%.
Monolithic Power Systems and Infineon Technologies each hold about 25% of 2025 value; with Vicor, Renesas Electronics and Delta Electronics the top five hold about 74% (DC Market Insights estimate). MPS Enterprise Data revenue was USD 380.6 million in the second quarter of 2026.
USD 3.57 billion in 2026 is the DC Market Insights value of board-level conversion in AI servers only. Estimates that add AC-DC power supplies, power shelves or all server power semiconductors come out larger.
Licences, delivery and payment
Which licence should I choose?
Single User is a view-only PDF for one person. Multi User adds a printable PDF and the Excel data for unlimited users at one location. Enterprise covers your whole company and includes 100 free analyst hours.
How and when will I receive the report?
By email, within 24–48 business hours of payment, in the formats of your licence.
How can I pay?
Securely through PayPal: with a PayPal account, a debit or credit card, or PayPal Pay Later where available. Prices are in US dollars.
Can I see a sample first?
Yes. Request a free sample and we will email it to you.
Can the report be tailored to my needs?
Yes. We can add countries, segments or data cuts. Talk to an analyst about the scope you need.
Can I get an invoice or pay against a purchase order?
Write to sales@dcmarketinsights.com and our team will help.