
Egypt Data Center Market Size, Share & Forecast to 2035
Market at a glance
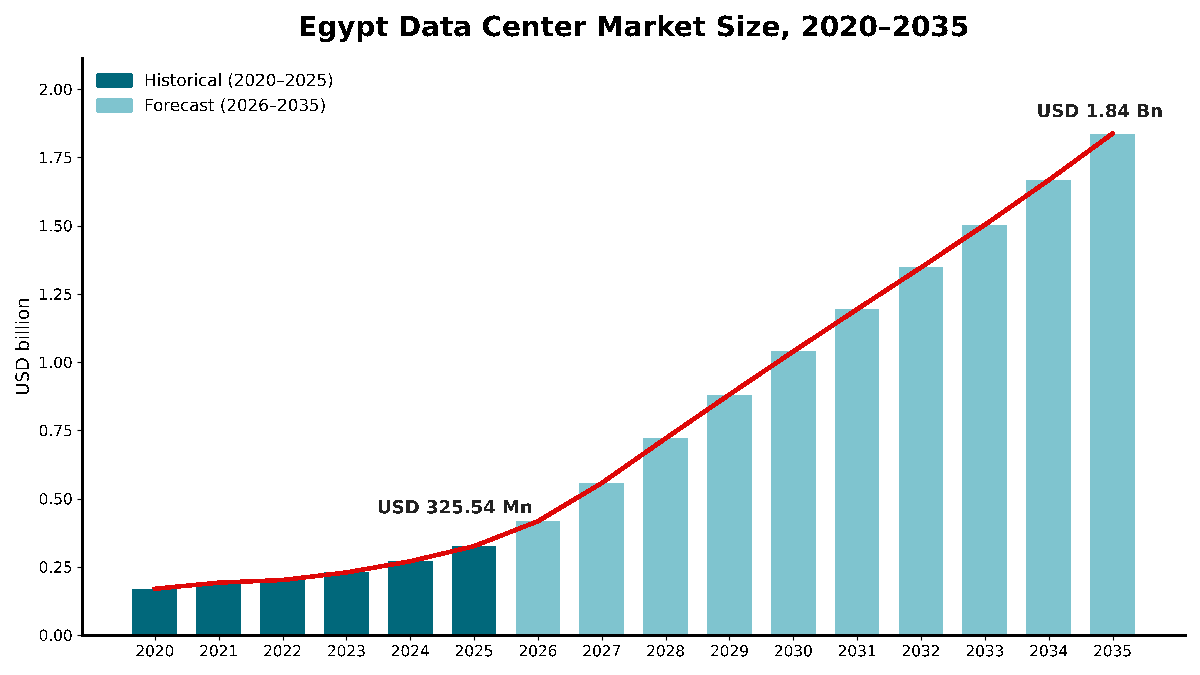
The Egypt Data Center market was worth USD 325.5 million in 2025 and is forecast to reach USD 1,840.0 million by 2035, growing at a 18.89% CAGR. Greater Cairo accounts for 74.2% of the market.
 By Priyanka Mor, Senior Consultant
 Reviewed by Deepti Agrawal
Last updated 7 Oct 2026
Base year 2025 PDF + Excel
Source: DC Market Insights analysis
Key findings
Ten NTRA Licences and a Pipeline Above 650 MW Turn Plans into Construction
GPU-as-a-Service and a Sovereign AI Factory Bring AI Halls to Egypt
Renewable Capacity Trails Its Target by 1,028 MW
Data Center Construction in Cairo Keeps the Lead
What is inside the report
- 01Introduction
- 02Research Methodology
- 03Executive Summary
- 04Market Dynamics
- 05Pricing Analysis
- 06Standards and Regulation
- 07Supply Chain and Ecosystem
- 08Egypt Data Center Market Size and Forecast
- 09Egypt Data Center Market, by Component
- 10Egypt Data Center Market, by Data Center Type
- 21chapters
- 2020-2024Historical period
- 2026-2035Forecast period
- 16Companies profiled
Regional insights
- Greater Cairo74.2%
- Suez Canal Economic Zone and Red Sea10.6%
- Alexandria and North Coast10.1%
- Rest of Egypt5.1%
Segmentation
Companies profiled
- Telecom Egypt
- Raya Data Center
- GPX Global Systems
- Vodafone Business
- Elsewedy Electric
- Cassava Technologies
- Gulf Data Hub
- Khazna Data Centers
- Benya Group
- Intro Group
- Oman Data Park
- Hassan Allam Digital Infrastructure
- Huawei Cloud
- Orange
- Africa50
- Administrative Capital for Urban Development
Recent developments
SEA-ME-WE 6 completed its two Egyptian landings, at Port Said and Ras Ghareb (Source: Telecom Egypt press release).
Egypt issued the executive regulations of the Personal Data Protection Law as Ministerial Decree No. 816 of 2025 (Source: Al Tamimi legal briefing).
the NTRA licensed Hassan Allam Digital Infrastructure for a USD 400 million data center investment (Source: Data Center Dynamics report).
Telecom Egypt decided not to sell a 75-80% stake in its data center unit to Helios Investments and will carve it into a wholly owned subsidiary (Source: Telecom Egypt press release).
Vodafone Business, Elsewedy Electric and Cassava Technologies announced ADC Egypt, starting with 20 MW and planned to scale to 200 MW (Source: Ahram Online report).
the communications minister reviewed Intro Group's plans for the 80 MW Kemet Data Centre in the SCZONE, with USD 270 million in the first phase (Source: Daily News Egypt report).
Full analysis
The Egypt Data Center Market covers spending on data center capacity in Egypt: the IT infrastructure installed in data halls (servers, storage and network equipment), power solutions, cooling systems and general construction for enterprise, government, colocation, hyperscale and cloud facilities. DC Market Insights values the Egypt Data Center Market at USD 325.54 million in 2025 and forecasts USD 1.84 billion by 2035, a CAGR of 18.89%. The 2025 value is built from capacity: about 11 MW of IT load completed in 2025 and 15 MW completing in 2026, at USD 7.40 million of facility cost per MW in conventional halls and USD 10.20 million per MW in AI halls, gives USD 99.42 million of power, cooling and construction spend; IT fit-out of the new halls adds USD 45.32 million and IT refresh on an installed base of about 103 MW adds USD 180.81 million. Hyperscale and cloud data centers are the fastest-growing segment at 27.26% a year as AI and GPU-as-a-Service campuses arrive, and the Suez Canal Economic Zone and Red Sea is the fastest-growing region at 30.69% a year because new campuses sit next to the cable landings at Port Said and Ras Ghareb.
Executive Summary
The Egypt Data Center Market size was valued at USD 169.39 million in 2020, reached USD 325.54 million in 2025, and is anticipated to reach USD 1.84 billion by 2035, at a CAGR of 18.89% during the forecast period.
| Report attribute | Details |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Egypt Data Center Market Size 2025 | USD 325.54 Million |
| Egypt Data Center Market, CAGR | 18.89% |
| Egypt Data Center Market Size 2035 | USD 1.84 Billion |
The Egypt Data Center Market grew at 13.96% a year between 2020 and 2025, and 2025 added 20.5% over 2024 as Telecom Egypt’s second Regional Data Hub phase, due by the end of 2025, and new enterprise rooms were built. Growth peaks in 2026 and 2027, at 28.0% and 33.6%, as licensed campuses move into construction.
Egypt’s data center base is still small. Knight Frank, cited by W.Media in January 2024, put Egypt’s live IT capacity at 13 MW, and Vodafone Egypt’s chief executive has said Africa holds less than 1% of global data center capacity. DC Market Insights counts a wider base that includes government, bank and telecom data halls, about 103 MW of IT load at the end of 2025, and forecasts 382 MW of completions between 2026 and 2035, taking the installed base to about 485 MW.
Market Scope: What Does the Egypt Data Center Market Cover?
The Egypt Data Center Market is the annual spend on building, equipping and refreshing data centers located in Egypt, valued in current US dollars, with 2025 as the base year and forecasts to 2035. DC Market Insights sizes it at USD 325.54 million in 2025.
Included. IT infrastructure installed in data halls (servers, storage and network equipment, bought for new halls or as refresh), power solutions (switchgear, transformers, uninterruptible power supply (UPS) systems, batteries, generators and power distribution), cooling systems (chillers, computer room air handlers, liquid cooling and piping) and general construction (shell, fit-out, fire protection and physical security). All facility types are counted, including modular units.
Excluded. Land, utility-side grid and renewable generation assets, subsea cables and landing stations, software licences, colocation and cloud service revenues, electricity and operating costs.
How the segments fit together. The component, data center type, end-user, tier and build-type splits each re-cut the same USD 325.54 million total, and the regional split allocates it across four Egyptian sub-markets.
Market Drivers: What Drives the Egypt Data Center Market?
The largest announced campuses, with budgets of USD 250 million to USD 2.1 billion, drive the Egypt Data Center Market. Egypt’s subsea cable position and a state digital investment plan of up to USD 860 million a year support demand for new capacity.
Ten NTRA Licences and a Pipeline Above 650 MW Turn Plans into Construction
Egypt’s National Telecommunications Regulatory Authority (NTRA) has issued ten data centre licences over the past two years. The largest announced projects are Gulf Data Hub and Elsewedy’s three campuses of 192 MW, expanding to 300 MW, for USD 2.1 billion; Africa Data Centres Egypt (ADC Egypt) of Vodafone Business, Elsewedy Electric and Cassava Technologies, with 20 MW in its first three years, up to 200 MW in total and up to USD 1 billion of investment; Intro Group’s 80 MW Kemet Data Centre in the Suez Canal Economic Zone (SCZONE); and Khazna Data Centers and Benya Group’s 25 MW Maadi campus, expandable to 50 MW, for USD 250 million. In June 2026 the NTRA licensed Hassan Allam Digital Infrastructure for a USD 400 million data center investment. DC Market Insights does not assume the whole pipeline is built: the model completes 137 MW between 2026 and 2030.
Fourteen Subsea Cables Make Egypt a Transit Hub
The Center for Strategic and International Studies (CSIS) counts 14 active cable systems in Egypt, with plans for more than 21 within three years, and estimates that Egypt carries about 17% of global internet traffic and over 90% of Europe-Asia communications. SEA-ME-WE 6, a 21,700 km system, completed two Egyptian landings in 2025, at Port Said on the Mediterranean and Ras Ghareb on the Red Sea. Telecom Egypt’s Regional Data Hub (RDH) at Smart Village connects to all 10 Mediterranean and Red Sea landing stations, and its first phase reached full use within one year. Colocation holds 36.9% of 2025 value in the DC Market Insights model and grows 20.21% a year as cable-adjacent interconnection demand rises.
State Digital Spending of up to USD 860 Million a Year Raises Demand
An official Ministry of Communications and Information Technology (MCIT) document reviewed by Asharq Bloomberg plans annual investment of USD 500 million to USD 860 million in data centres, cloud computing and artificial intelligence (AI) infrastructure from the 2026/27 fiscal year through 2030. Egypt’s information and communications technology (ICT) sector grew 13.76% in real terms in fiscal year 2024/25, according to the Information and Decision Support Center (IDSC), digital exports reached USD 7.4 billion in 2025, and public ICT investment rose to about EGP 27.69 billion in fiscal year 2024/25. Government and public sector users account for USD 80.73 million of 2025 data center spending in the DC Market Insights model, 24.8% of the total.
Market Trends: How Are Data Centers in Egypt Changing?
AI halls, coastal campuses and factory-built modules are reshaping the Egypt Data Center Market: DC Market Insights estimates the AI share of new capacity rises from 5% in 2025 to 36% in 2035.
GPU-as-a-Service and a Sovereign AI Factory Bring AI Halls to Egypt
Vodafone Business and Cassava Technologies, in a separate sovereign AI partnership alongside ADC Egypt, will give businesses and government entities access to NVIDIA technologies and GPU-as-a-Service locally, in what is described as Egypt’s first sovereign AI factory. Egypt’s second National AI Strategy (2025-2030) targets more than 250 AI-driven startups and over 30,000 trained AI specialists. AI-related spending, covering AI hall construction, graphics processing unit (GPU) fit-out and refresh, rises from 5.7% of the market in 2025 to 39.6% in 2035, by DC Market Insights estimates.
New Campuses Move to the Suez Canal Economic Zone and the Red Sea
Kemet Data Centre will be built in the Integrated Sokhna Industrial Zone, covers 80,000 sqm, will be developed in two phases and is expected to be partially powered by solar energy. The SCZONE has also proposed a USD 60 million, 5-7 MW data center with private-sector partners, and in March 2026 the government said it was in talks with Renergy Group on USD 1 billion of investment for a renewable-powered hyperscale data center in Sinai. The Suez Canal Economic Zone and Red Sea region rises from 10.6% of the market in 2025 to 27.3% in 2035 in the DC Market Insights model.
Modular Data Centers Rise to 27.1% of Spend
Telecom Egypt designed its Smart Village RDH as 4 colocation modular facilities with room for up to 2,000 racks. Modular and prefabricated data centers hold 18.4% of 2025 value and grow 23.59% a year to 27.1% in 2035, by DC Market Insights estimates.
Market Challenges: What Holds the Egypt Data Center Market Back?
Installed renewable capacity was 1,028 MW short of target at the end of 2024, and that power gap, foreign-currency funding and slow conversion of announcements into builds are the main constraints DC Market Insights sees on the Egypt Data Center Market.
Renewable Capacity Trails Its Target by 1,028 MW
Egypt targets 42% of electricity from renewable sources by 2030 and more than 60% by 2040, but installed renewable capacity reached 7,750 MW at the end of 2024 against a projected 8,778 MW, according to the US International Trade Administration (ITA) Egypt Country Commercial Guide. The shift towards green power matters because hyperscale tenants depend on that build-out, although the latest solar tariff of 1.8 US cents per kWh keeps new renewable supply cheap.
Large Projects Depend on Foreign Capital and Shrink Between Phases
Kemet’s first-phase budget of USD 270 million compares with a 2024 memorandum with Oman Data Park valued at USD 450 million. In July 2026 Telecom Egypt decided not to sell a 75-80% stake in its data center unit to Helios Investments, which had valued the unit at USD 230 million, potentially up to USD 260 million, and will instead carve the business into a wholly owned subsidiary. DC Market Insights treats deal delays as the main downside risk in its low scenario.
The Pipeline Could Lift Live Capacity Ten-Fold
Knight Frank, cited by W.Media, described a pipeline able to increase Egypt’s live IT capacity ten-fold, and the UAE Ministry of Investment and MCIT signed a memorandum for up to 1 GW of data center capacity in December 2023, starting with a first phase of 100 MW. DC Market Insights completes only 137 MW in 2026-2030 because power and tenants, not announcements, set the pace.
Market Opportunities: Where Are the New Revenue Pools in the Egypt Data Center Market?
Hyperscale and cloud data centers, growing 27.26% a year, and data center construction in Cairo, worth USD 71.04 million in 2025 for power, cooling and construction, are the largest new revenue pools in the Egypt Data Center Market.
Data Center Construction in Cairo Keeps the Lead
Greater Cairo, including the New Administrative Capital and Smart Village, accounts for USD 241.55 million of 2025 spending, of which power, cooling and construction make up USD 71.04 million in the DC Market Insights matrix. GPX Global Systems announced in May 2023 an EGP 2.7 billion expansion of its Cairo data center adding 12 MW of power and 9,000 m² of space, with phase one then targeted to be customer-ready in late Q3 2026. Raya Data Center raised USD 25 million, USD 15 million from Africa50 for a 42.9% stake and USD 10 million from Raya Information Technology, for a Tier III data center whose construction was slated to begin in early 2025.
Hyperscale and Cloud Grows 27.26% a Year
Investment in hyperscale facilities follows the expansion of cloud regions such as Huawei Cloud’s Cairo Region, launched in 2024 as the company’s 33rd cloud region and serving 28 African countries. Hyperscale and cloud data centers hold 15.8% of 2025 value and 31.2% in 2035 by DC Market Insights estimates, the fastest rate of any data center type.
Pricing: How Much Does a Data Center Cost per MW in Egypt?
A conventional data center hall in Egypt costs about USD 7.40 million of power, cooling and construction per MW of IT load in 2025, and an AI hall about USD 10.20 million per MW. These are DC Market Insights estimates, excluding land and IT equipment.
| Spend per MW (USD million) | 2025 | 2030 | 2035 |
|---|---|---|---|
| Facility, conventional hall | 7.40 | 7.85 | 8.34 |
| Facility, AI hall | 10.20 | 9.80 | 9.41 |
| IT fit-out, conventional hall | 3.60 | 3.69 | 3.78 |
| IT fit-out, AI hall | 14.00 | 13.31 | 12.66 |
| AI share of new capacity | 5% | 29% | 36% |
Announced project budgets give a cross-check: ADC Egypt’s phase one implies about USD 10.0 million per MW (USD 200 million for 20 MW), Khazna’s Cairo campus about USD 10.0 million per MW (USD 250 million for 25 MW), Gulf Data Hub and Elsewedy about USD 10.9 million per MW (USD 2.1 billion for 192 MW) and the SCZONE project USD 8.6-12.0 million per MW (USD 60 million for 5-7 MW), all DC Market Insights calculations from the announced figures, which can include IT and land. Helios’s USD 230 million valuation of Telecom Egypt’s data center unit, set against the 7.1 MW of RDH 1 and RDH 2, implies about USD 32.4 million per MW, a valuation multiple rather than a build cost.
Standards and Regulation: Which Rules Shape Data Centers in Egypt?
Four sets of rules shape data centers in Egypt: NTRA licensing, the Personal Data Protection Law, Uptime Institute tier certification and the national renewable energy targets.
NTRA licensing. The NTRA approved a regulatory framework to establish data centers and provide cloud computing services in August 2021. The US ITA describes the framework for Public Data Center Providers (PDCP) as offering 15-year licences that allow direct submarine cable connectivity. In June 2026 Middle East AI News reported that three ministers had agreed to prepare a national data centre and cloud strategy and an investment map of proposed sites.
Personal Data Protection Law. Law No. 151 of 2020 is implemented through executive regulations issued as Ministerial Decree No. 816 of 2025 on 1 November 2025. Controllers and processors must report a personal data breach within 72 hours, and transfers abroad need a licence and an adequate level of protection in the receiving country.
Uptime Institute tiers. The Administrative Capital for Urban Development (ACUD) data center in the New Administrative Capital holds Uptime Institute Tier III certifications for design documents and constructed facility, Telecom Egypt’s RDH 2 received Tier III design certification, Kemet aims to be the first Tier III project in the SCZONE, and Gulf Data Hub targets Tier III and LEED certifications.
Renewable energy targets. Egypt targets 42% renewable electricity by 2030, and the Integrated Sustainable Energy Strategy, cited at the June 2026 ministerial meeting on data centres, targets 45% within two years.
Market Segmentation: Which Segment Leads the Egypt Data Center Market?
IT infrastructure leads the Egypt Data Center Market with 69.5% of 2025 value, enterprise and government facilities lead data center types with 47.3%, and Tier III leads tiers with 64.9%. Hyperscale and cloud is the fastest-growing segment at 27.26% a year, against 20.21% for colocation, because AI and GPU-as-a-Service campuses are planned at a scale no Egyptian enterprise builds.
By Component: IT Infrastructure Leads with 69.5%
| Component | 2025 (USD million) | Share 2025 | 2035 (USD billion) | CAGR 2025-2035 |
|---|---|---|---|---|
| IT Infrastructure | 226.12 | 69.5% | 1.34 | 19.50% |
| Power Solutions | 43.55 | 13.4% | 0.21 | 17.24% |
| General Construction | 31.14 | 9.6% | 0.14 | 16.60% |
| Cooling Systems | 24.73 | 7.6% | 0.14 | 18.59% |
IT infrastructure grows fastest among components because AI halls carry about USD 14.00 million of GPU and network fit-out per MW.
By Data Center Type: Enterprise and Government Leads with 47.3%
| Data center type | 2025 (USD million) | Share 2025 | 2035 (USD billion) | CAGR 2025-2035 |
|---|---|---|---|---|
| Enterprise and Government | 153.98 | 47.3% | 0.51 | 12.66% |
| Colocation | 120.12 | 36.9% | 0.76 | 20.21% |
| Hyperscale and Cloud | 51.44 | 15.8% | 0.57 | 27.26% |
Enterprise and government halls, including the state data and cloud computing center opened in April 2024, account for USD 153.98 million in 2025. Colocation overtakes them before 2030 and reaches 41.2% in 2035, by DC Market Insights estimates.
By End User: IT and Telecom Leads with 33.6%
| End user | 2025 (USD million) | Share 2025 | 2035 (USD billion) | CAGR 2025-2035 |
|---|---|---|---|---|
| IT and Telecom | 109.39 | 33.6% | 0.57 | 17.90% |
| Government and Public Sector | 80.73 | 24.8% | 0.41 | 17.53% |
| BFSI | 70.64 | 21.7% | 0.34 | 16.95% |
| Healthcare | 17.25 | 5.3% | 0.11 | 20.78% |
| Others | 47.53 | 14.6% | 0.41 | 24.09% |
Banking, financial services and insurance (BFSI) users spend USD 70.64 million in 2025. Others, including AI developers, energy and utilities, manufacturing and retail, grows fastest at 24.09% a year.
By Tier Standard: Tier III Leads with 64.9%
Tier III facilities are worth USD 211.28 million in 2025 and USD 1.28 billion by 2035 (19.71% a year). Tier IV, at USD 41.34 million (12.7%), grows fastest at 22.70% a year, while Tier I and II rooms, at USD 72.92 million (22.4%), grow 12.68% a year as small server rooms move into colocation.
By Build Type: Traditional Build Leads with 81.6%
Traditional builds account for USD 265.64 million in 2025 and USD 1.34 billion in 2035, growing 17.56% a year. Modular and prefabricated data centers grow 23.59% a year from USD 59.90 million as banks and staged campuses add capacity in blocks.
Modular Data Centers in Egypt: Who Provides Them and What Are They Worth?
Modular and prefabricated data centers are worth USD 59.90 million in Egypt in 2025, 18.4% of the Egypt Data Center Market, by DC Market Insights estimates. Buyers looking for a modular data center for sale in Egypt can choose between containerized all-in-one units and prefabricated rooms built off site.
Providers with Egyptian projects. Huawei deployed its FusionDC1000A prefabricated all-in-one data center for Mountain View, which Huawei describes as one of Egypt’s top three real estate developers; the system integrates power, cooling, cabinets, management and fire suppression in 20-foot or 40-foot ISO containers and can be installed on site in one day. RZ-Products, a DCG Data Center Group subsidiary, and Sterling and Wilson delivered a prefabricated data center to Faisal Islamic Bank of Egypt in Cairo in 2021.
What modular capacity costs. DC Market Insights prices modular builds at the conventional rate of USD 7.40 million of facility cost per MW in 2025; the saving is in schedule, not equipment.
DC Exclusive: The Cairo vs Suez Canal Build-Cost Matrix
At USD 170.51 million in 2025, IT infrastructure in Greater Cairo is the single largest cell of the matrix and 52.4% of all Egyptian data center spending.
| 2025, USD million | IT Infrastructure | Power Solutions | Cooling Systems | General Construction | Total |
|---|---|---|---|---|---|
| Greater Cairo | 170.51 | 31.67 | 17.68 | 21.69 | 241.55 |
| Suez Canal Economic Zone and Red Sea | 19.85 | 5.56 | 3.60 | 5.50 | 34.51 |
| Alexandria and North Coast | 23.54 | 4.31 | 2.41 | 2.62 | 32.88 |
| Rest of Egypt | 12.22 | 2.01 | 1.04 | 1.33 | 16.60 |
| Total | 226.12 | 43.55 | 24.73 | 31.14 | 325.54 |
Greater Cairo spends 70.6% of its data center budget on IT infrastructure because its halls are full and refresh is the main spend. The Suez Canal Economic Zone and Red Sea spends 42.5% on power, cooling and construction, against 29.4% in Cairo, because its campuses are greenfield builds on industrial land.
The matrix is a DC Market Insights model, not a project count. It is built from 69 inputs: 36 capacity cohort values (18 years of completions and AI shares), 6 cost and refresh curves, 6 facility-mix weights, 16 regional component weights, 1 starting installed base and 4 project cost ratios used as a cross-check. The method is explained on our research methodology page.
Regional Insights: Which Region Leads the Egypt Data Center Market?
Greater Cairo leads with 74.2% of 2025 value, and capacity follows a Greater Cairo, Alexandria, Suez Canal corridor. In the Egypt Data Center Market, the Suez Canal Economic Zone and Red Sea is the fastest-growing region at 30.69% a year because new campuses need land, power and direct access to the cable landings.
Greater Cairo Leads with 74.2% Share
Greater Cairo is worth USD 241.55 million in 2025 and USD 1.02 billion by 2035, a CAGR of 15.51%. Data Center Map lists 10 of Egypt’s 14 data centers in Cairo.
Suez Canal Economic Zone and Red Sea Holds 10.6% Share
The Suez Canal Economic Zone and Red Sea, covering Ain Sokhna, Port Said and Ras Ghareb, is worth USD 34.51 million in 2025 and USD 501.63 million by 2035, growing 30.69% a year and reaching 27.3% of the market as Kemet and the SCZONE project are built.
Alexandria and North Coast Holds 10.1% Share
Alexandria and the North Coast are worth USD 32.88 million in 2025 and USD 191.10 million by 2035, a CAGR of 19.24%, supported by Telecom Egypt’s data centers in the city.
Rest of Egypt Holds 5.1% Share
The rest of Egypt, including the Nile Delta, Upper Egypt and Sinai, is worth USD 16.60 million in 2025 and USD 123.11 million by 2035, a CAGR of 22.19%, with upside if the renewable-powered Sinai hyperscale project proceeds.
Forecast Scenarios: How Could the 2035 Forecast Change?
The Egypt Data Center Market reaches USD 1.84 billion by 2035 in the base case, with a range of USD 1.31 billion to USD 2.20 billion across the low and high scenarios.
| Scenario | Assumption from 2026 | 2035 (USD billion) | CAGR 2025-2035 |
|---|---|---|---|
| Low | Completions 30% below base; AI share of new capacity 20% lower | 1.31 | 14.92% |
| Base | Completions rise to 55 MW a year by 2035; AI share reaches 36% | 1.84 | 18.89% |
| High | Completions 20% above base; AI share 12% higher | 2.20 | 21.08% |
The low case reflects delayed foreign funding; the high case assumes ADC Egypt and the licensed campuses keep their announced schedules.
Competitive Insights: Which Data Center Companies in Egypt Lead the Egypt Data Center Market?
- Telecom Egypt
- Raya Data Center
- GPX Global Systems
- Vodafone Business
- Elsewedy Electric
- Cassava Technologies
- Gulf Data Hub
- Khazna Data Centers
- Benya Group
- Intro Group
- Oman Data Park
- Hassan Allam Digital Infrastructure
- Huawei Cloud
- Orange
- Africa50
- Administrative Capital for Urban Development
The announced pipeline is concentrated: Gulf Data Hub and Elsewedy (300 MW), ADC Egypt (200 MW) and Kemet (80 MW) account for 88.1% of the 658.3 MW announced by the six largest named projects, which also include Khazna (50 MW), Telecom Egypt’s RDH (up to 16.3 MW across all phases) and GPX (12 MW) (DC Market Insights calculation from announced capacities). In operating colocation, Telecom Egypt reported 6 commercial data centers in Greater Cairo and Alexandria in 2020, before adding the Smart Village RDH, Raya Data Center operates two Cairo facilities, and Orange was set in 2021 to build a USD 135 million data center in the New Administrative Capital.
Recent Developments
- In July 2025, SEA-ME-WE 6 completed its two Egyptian landings, at Port Said and Ras Ghareb (Source: Telecom Egypt press release).
- In November 2025, Egypt issued the executive regulations of the Personal Data Protection Law as Ministerial Decree No. 816 of 2025 (Source: Al Tamimi legal briefing).
- In June 2026, the NTRA licensed Hassan Allam Digital Infrastructure for a USD 400 million data center investment (Source: Data Center Dynamics report).
- In July 2026, Telecom Egypt decided not to sell a 75-80% stake in its data center unit to Helios Investments and will carve it into a wholly owned subsidiary (Source: Telecom Egypt press release).
- In September 2026, Vodafone Business, Elsewedy Electric and Cassava Technologies announced ADC Egypt, starting with 20 MW and planned to scale to 200 MW (Source: Ahram Online report).
- In September 2026, the communications minister reviewed Intro Group’s plans for the 80 MW Kemet Data Centre in the SCZONE, with USD 270 million in the first phase (Source: Daily News Egypt report).
We follow these licences, launches and financings as they happen in our data center industry updates. Related reports: Egypt Data Center Colocation Market and Egypt Data Center Infrastructure Market.
Methodology: How We Built the Egypt Data Center Market Model
DC Market Insights built the Egypt Data Center Market bottom-up from 18 annual completion cohorts (2019 to 2036), each split into conventional and AI halls, starting from an installed base of 58 MW of IT load at the end of 2019 and reaching about 103 MW at the end of 2025. Facility spend (USD 7.40 million per MW conventional, USD 10.20 million AI, in 2025) is recognized half in the year before completion and half in the completion year. IT spend adds fit-out of new halls (USD 3.60 million per MW conventional, USD 14.00 million per MW AI) and refresh of USD 1.85 million per MW a year on the conventional base and USD 2.80 million on the AI base. The total was split by 4 components, 3 data center types, 5 end-user groups, 3 tier groups, 2 build types and 4 regions, and every split sums to the market total. The result was checked top-down against announced project costs of USD 8.6-12.0 million per MW and against the MCIT plan of USD 500 million to USD 860 million a year for data centres, cloud and AI from 2026/27 (the model’s 2027 value is USD 557.00 million).
Table of contents
- 01Introduction
- 1.1Market Definition and Scope
- 1.2Report Coverage and Units
- 1.3Key Questions Answered
- 02Research Methodology
- 2.1Bottom-Up Capacity Cohort Model
- 2.2Top-Down Checks Against Project Budgets and the MCIT Plan
- 2.3Data Sources and Fact Verification
- 03Executive Summary
- 3.1Egypt Data Center Market Snapshot, 2025 and 2035
- 3.2Key Findings
- 04Market Dynamics
- 4.1Market Drivers
- 4.2Market Trends
- 4.3Market Challenges
- 4.4Market Opportunities
- 05Pricing Analysis
- 5.1Facility Spend per MW, Conventional and AI Halls
- 5.2IT Fit-Out and Refresh per MW
- 5.3Announced Project Cost per MW
- 06Standards and Regulation
- 6.1NTRA Data Center Licensing Framework
- 6.2Personal Data Protection Law and Executive Regulations
- 6.3Uptime Institute Tier Certification
- 6.4Renewable Energy Targets
- 07Supply Chain and Ecosystem
- 7.1Subsea Cables and Landing Stations
- 7.2Power and Renewable Supply
- 7.3Equipment Suppliers and Contractors
- 08Egypt Data Center Market Size and Forecast
- 8.1Market Size, 2020-2035
- 8.2Installed IT Capacity and Completions, 2019-2036
- 8.3AI Share of New Capacity
- 09Egypt Data Center Market, by Component
- 9.1IT Infrastructure
- 9.2Power Solutions
- 9.3Cooling Systems
- 9.4General Construction
- 10Egypt Data Center Market, by Data Center Type
- 10.1Enterprise and Government
- 10.2Colocation
- 10.3Hyperscale and Cloud
- 11Egypt Data Center Market, by End User
- 11.1IT and Telecom
- 11.2Government and Public Sector
- 11.3BFSI
- 11.4Healthcare
- 11.5Others
- 12Egypt Data Center Market, by Tier Standard
- 12.1Tier I and II
- 12.2Tier III
- 12.3Tier IV
- 13Egypt Data Center Market, by Build Type
- 13.1Traditional Build
- 13.2Modular and Prefabricated
- 14Modular Data Centers in Egypt
- 14.1Providers and Projects
- 14.2Modular Spend, 2025 and 2035
- 15DC Exclusive: Cairo vs Suez Canal Build-Cost Matrix
- 15.1Matrix by Region and Component, 2025
- 15.2Model Inputs
- 16Egypt Data Center Market, by Region
- 16.1Greater Cairo
- 16.2Suez Canal Economic Zone and Red Sea
- 16.3Alexandria and North Coast
- 16.4Rest of Egypt
- 17Regional Cross-Sections
- 17.1Region by Component, 2025
- 17.2Region Share, 2025 and 2035
- 18Forecast Scenarios
- 18.1Low Scenario
- 18.2Base Scenario
- 18.3High Scenario
- 19Competitive Landscape
- 19.1Announced Pipeline Concentration
- 19.2Operating Colocation Providers
- 19.3Recent Developments
- 20Company Profiles
- 20.1Telecom Egypt
- 20.2Raya Data Center
- 20.3GPX Global Systems
- 20.4Vodafone Business
- 20.5Elsewedy Electric
- 20.6Cassava Technologies
- 20.7Gulf Data Hub
- 20.8Khazna Data Centers
- 20.9Benya Group
- 20.10Intro Group
- 20.11Oman Data Park
- 20.12Hassan Allam Digital Infrastructure
- 20.13Huawei Cloud
- 20.14Orange
- 20.15Africa50
- 20.16Administrative Capital for Urban Development
- 21Analyst Recommendations
- 21.1For Colocation Developers
- 21.2For Enterprises and Government Buyers
- 21.3For Equipment Suppliers and Investors
- Fig. 1Egypt Data Center Market Size, 2020-2035
- Fig. 2Egypt Data Center Market Share by Component, 2025
- Fig. 3Egypt Data Center Market Share by Data Center Type, 2025 and 2035
- Fig. 4Egypt Data Center Market Share by Region, 2025 and 2035
- Fig. 5Installed IT Capacity in Egypt, 2019-2036
- Fig. 6Forecast Scenarios, 2035
- Table 1Egypt Data Center Market Report Attributes
- Table 2Spend per MW, 2025, 2030 and 2035
- Table 3Announced Project Cost per MW
- Table 4Egypt Data Center Market by Component, 2025 and 2035
- Table 5Egypt Data Center Market by Data Center Type, 2025 and 2035
- Table 6Egypt Data Center Market by End User, 2025 and 2035
- Table 7Egypt Data Center Market by Tier Standard, 2025 and 2035
- Table 8Egypt Data Center Market by Build Type, 2025 and 2035
- Table 9Cairo vs Suez Canal Build-Cost Matrix, 2025
- Table 10Egypt Data Center Market by Region, 2025 and 2035
- Table 11Forecast Scenarios, 2035
- Table 12Announced Data Center Pipeline by Project
About this report
Written by Priyanka Mor and reviewed by Deepti Agrawal, Senior Editor, Research. Figures are built top-down and bottom-up and reconciled before publication, with 2025 as the base year.
Read our methodologyHow we built this
- Historical period2020-2024
- Base year2025
- Forecast period2026-2035
- Sizing approachTop-down + bottom-up
Need more than the report?
Advisory on this market
Due diligence, site selection and market entry work, by the analysts who wrote this report.
See consulting servicesFrequently asked questions
USD 325.54 million in 2025, rising to USD 1.84 billion by 2035, according to DC Market Insights. The 2025 value comes from about 11 MW completed in 2025 and 15 MW completing in 2026, priced per MW, plus IT refresh on an installed base of about 103 MW.
18.89% a year from 2025 to 2035, after 13.96% a year from 2020 to 2025. Growth peaks in 2026 and 2027 as licensed campuses move into construction, and the AI share of new capacity rises from 5% to 36%.
14 data centers are listed in Egypt by Data Center Map, 10 of them in Cairo. DC Market Insights estimates about 103 MW of installed IT load at the end of 2025, including government, bank and telecom data halls.
USD 59.90 million of 2025 spending goes to modular and prefabricated data centers, by DC Market Insights estimates. Huawei supplied a FusionDC1000A prefabricated data center to Mountain View, and RZ-Products and Sterling and Wilson delivered one to Faisal Islamic Bank of Egypt.
88.1% of the 658.3 MW announced by the six largest named projects comes from Gulf Data Hub and Elsewedy, ADC Egypt and Kemet. Telecom Egypt, Raya Data Center and GPX Global Systems are established colocation operators in Cairo.
USD 7.40 million of power, cooling and construction per MW for a conventional hall and USD 10.20 million per MW for an AI hall in 2025, by DC Market Insights estimates. Greater Cairo spends USD 71.04 million on these components in 2025.
13.76% real growth in Egypt’s ICT sector in fiscal year 2024/25, reported by the IDSC, and an MCIT plan of USD 500 million to USD 860 million a year for data centres, cloud and AI from 2026/27 support demand for new capacity.
30.69% a year in the Suez Canal Economic Zone and Red Sea, which grows from USD 34.51 million in 2025 to USD 501.63 million by 2035. Greater Cairo leads in 2025 with 74.2% of value.
Get this report
How do I get the full report?
Request a quote; we reply by email within one business day.
How and when will I receive the report?
By email, within 24–48 business hours of payment.
How can I pay?
Once you accept the quote, we email you a secure payment link.
Can I see a sample first?
Yes. Request a free sample and we will email it to you.
Can the report be tailored to my needs?
Yes. We can add countries, segments or data cuts. Talk to an analyst about the scope you need.
Can I get an invoice or pay against a purchase order?
Write to sales@dcmarketinsights.com and our team will help.