
AI Chip Market Size, Share & Forecast to 2035
Market at a glance
The AI Chip market was worth USD 185.26 billion in 2025 and is forecast to reach USD 840.89 billion by 2035, growing at a 16.33% CAGR. North America accounts for 56.4% of the market.
 By Amit Jain, Senior Consultant, ICT & Emerging Technologies
 Reviewed by Deepti Agrawal
Last updated 21 Oct 2026
Base year 2025 PDF + Excel
Source: DC Market Insights analysis
Key findings
NVIDIA Data Center Revenue Rose 117% in the Quarter to July 2026
Custom Silicon Rises from 17.6% to 29.6% of Spending
Export Controls Shut Leading GPUs Out of China
Inference Accelerators Open the Data Center to New Suppliers
What is inside the report
- 01Introduction
- 02Executive Summary
- 03Market Dynamics
- 04Pricing Analysis
- 05Standards and Regulation
- 06AI Chip Market, by Chip Type
- 07AI Chip Market, by Deployment
- 08AI Chip Market, by Function
- 09AI Chip Market, by End Use
- 10DC Exclusive: AI Chip Value Map, 4 Deployments by 5 Chip Types
- 16chapters
- 2020-2024Historical period
- 2026-2035Forecast period
- 16Companies profiled
Regional insights
- North America56.4%
- Asia Pacific26.8%
- Europe10%
- Middle East and Africa4.8%
- Latin America2.1%
Segmentation
Companies profiled
- NVIDIA
- Advanced Micro Devices (AMD)
- Broadcom
- Google (TPU)
- Amazon Web Services (Trainium)
- Microsoft (Maia)
- Intel
- Qualcomm
- Huawei (Ascend)
- Mobileye
- Horizon Robotics
- Marvell Technology
- Cambricon Technologies
- Cerebras Systems
- SambaNova Systems
- Hailo
Recent developments
AMD and OpenAI announced a 6 GW agreement for AMD GPUs, starting with 1 GW of Instinct MI450 in the second half of 2026 (Source: AMD press release).
OpenAI and Broadcom agreed to deploy 10 GW of OpenAI-designed custom AI accelerators, targeted to start in the second half of 2026 and complete by the end of 2029 (Source: OpenAI announcement).
Microsoft introduced its Maia 200 inference accelerator on TSMC's 3-nanometer process with 216 GB of HBM3e (Source: Microsoft announcement).
NVIDIA reported first-quarter fiscal 2027 data center revenue of USD 75.20 billion, of which compute was USD 60.40 billion (Source: NVIDIA investor relations).
NVIDIA reported second-quarter fiscal 2027 data center revenue of USD 89.00 billion, up 117%, and said Vera Rubin was in full production (Source: NVIDIA earnings release).
Broadcom reported third-quarter fiscal 2026 AI semiconductor revenue of USD 16.70 billion, up 221%, and guided USD 21.70 billion for the fourth quarter (Source: Broadcom Form 8-K).
Full analysis
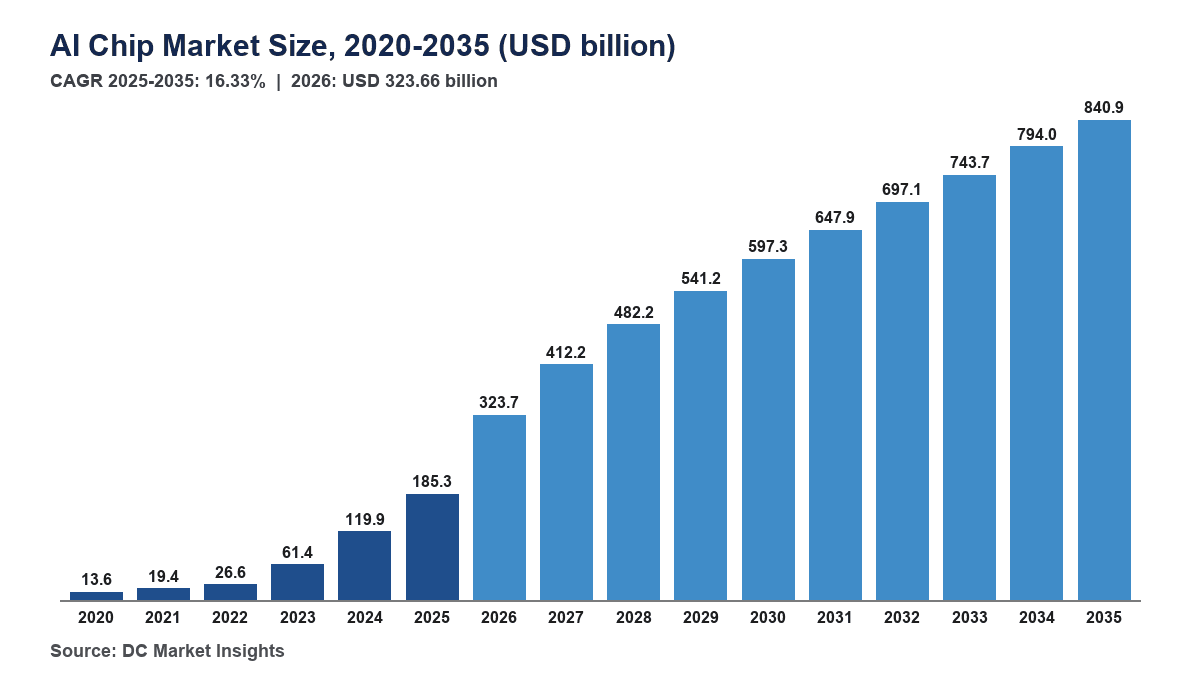
The AI Chip Market is valued at USD 323.66 billion in 2026 and is projected to reach USD 840.89 billion by 2035, up from USD 185.26 billion in 2025, a CAGR of 16.33% from 2025 to 2035 (DC Market Insights estimate). The 74.7% jump in 2026 comes almost entirely from data center accelerators: NVIDIA Corporation (NVIDIA) reported data center revenue of USD 75.20 billion in the quarter to April 2026 and USD 89.00 billion in the quarter to July 2026, and Broadcom’s AI semiconductor revenue reached USD 16.70 billion in its quarter to August 2026, up 221%. Data center chips therefore reach USD 305.59 billion in 2026, 1.8 times their 2025 value, while edge and device chips for vehicles, personal computers (PCs), phones and machines add USD 18.07 billion. The 2025 base is a units-times-price build: 6.30 million data center graphics processing units (GPUs) x USD 22,060 = USD 138.98 billion, 5.18 million custom data center application-specific integrated circuits (ASICs) x USD 5,120 = USD 26.52 billion and 20.7 million automotive AI systems-on-chip (SoCs) x USD 310 = USD 6.42 billion, plus field-programmable gate arrays (FPGAs), other accelerators, client neural processing units (NPUs) and robotics chips. AI ASICs and SoCs are the fastest-growing chip type at 22.51% a year, because Google, Amazon Web Services, Microsoft and OpenAI now commission their own inference silicon, and the Middle East and Africa is the fastest-growing region at 20.23% a year as Gulf AI programs install accelerators from a small base. AI chips are the largest value block in the Data Center Chip Market.
Key Market Statistics: How Big Is the AI Chip Market in 2026?
The AI Chip Market is worth USD 323.66 billion in 2026, a rise of 74.7% on 2025, according to DC Market Insights estimates.
- Market size 2025: USD 185.26 billion
- Market size 2026: USD 323.66 billion
- Market size 2030: USD 597.28 billion
- Market size 2035: USD 840.89 billion
- CAGR 2025-2035: 16.33% base, 12.96% low scenario, 18.56% high scenario
- Largest chip type: GPUs, 76.9% of 2025 value
- Fastest-growing chip type: AI ASICs and SoCs, 22.51% a year
- Fastest-growing buyer type: enterprises and government, 18.15% a year
- Leading region: North America, 56.4% of 2025 value
- Fastest-growing region: Middle East and Africa, 20.23% a year
- Largest country: United States, USD 96.30 billion or 52.0% of 2025 value
- Market leader: NVIDIA, about 72% of 2025 value (DC Market Insights assessment)
Executive Summary
The Global AI Chip Market size was valued at USD 13.57 billion in 2020, reached USD 185.26 billion in 2025, and is anticipated to reach USD 840.89 billion by 2035, at a CAGR of 16.33% during the forecast period.
| Report attribute | Details |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| AI Chip Market Size 2025 | USD 185.26 Billion |
| AI Chip Market Size 2026 | USD 323.66 Billion |
| AI Chip Market, CAGR | 16.33% |
| AI Chip Market Size 2035 | USD 840.89 Billion |
The AI Chip Market grew at 68.67% a year between 2020 and 2025 as Blackwell-generation systems and custom accelerators moved into volume. NVIDIA, the largest supplier, reported fiscal 2026 data center revenue of USD 193.70 billion, up 68%, for the year ended January 25, 2026 (Source: NVIDIA filing with the US Securities and Exchange Commission). After the 2026 step-up, growth settles at 16.33% a year because custom ASICs take share at lower prices per chip and the base is 23.9 times its 2020 size by 2026. Edge and device chips hold 8.4% of value in 2025 and 8.6% in 2035.
Market Scope: What Is an AI Chip and What Does the AI Chip Market Cover?
An AI chip is a processor whose main job is artificial intelligence computation, and this market values every such chip at first sale in current US dollars, USD 185.26 billion in the 2025 base year.
Included. Data center GPUs, custom AI ASICs, data center FPGAs used for AI and other data center accelerators, valued as packaged modules with their on-package high-bandwidth memory (HBM); automotive AI SoCs for driver assistance and automated driving; edge AI accelerators and vision SoCs for robots, machines, smart cameras and gateways; and the value of the NPU block inside AI-capable PC and smartphone processors.
Excluded. Server central processing units (CPUs), the rest of a PC or smartphone processor outside its NPU, memory sold separately, network switches, complete servers and vehicles, software licenses and cloud rental revenue.
How the segments fit together. The data center part of this market equals the DC Market Insights Data Center Accelerator Market model in every year from 2020 to 2035, USD 305.59 billion in 2026. The chip type, function, deployment and end use splits each re-cut the same total. Regions and countries are allocated by where the chips are installed, not where they are designed or made.
Related segments and technologies. Analog and in-memory compute AI chips sit inside Other AI Chips, 1.5% of 2025 value, because they are not yet sold in volume (DC Market Insights assessment). Wafer-scale and dataflow systems from Cerebras Systems and SambaNova Systems are counted in Other AI Chips as well. Deep learning chips and AI chipsets are other names for the same products: the deep learning chip market and the AI chipset market both map onto this AI Chip Market, because every chip that trains or runs a deep learning model is counted here once, at first sale. HPC and scientific computing on accelerators is counted under HPC and Other, and mixed training and inference fleets are split by the share of chip hours each workload uses.
Why Do AI Chip Market Estimates Differ?
AI Chip Market estimates differ by scope: the DC Market Insights figure of USD 323.66 billion for 2026 counts chips at first sale with on-package memory.
Estimates that count only data center accelerators land near USD 305.59 billion for 2026, and estimates that count whole servers or whole device processors land well above USD 500 billion.
Broader definitions add server boards, CPUs, networking and chassis, the full value of PC and phone processors, or cloud rental revenue that counts the same chip many times. Narrower definitions leave out automotive and robotics chips, which add 5.6% of 2025 value. In-house chips from Google, Amazon Web Services and Microsoft are counted at estimated cost value, because they displace purchased GPUs, and buyers range from hyperscale cloud providers to enterprises, governments and carmakers.
| Element | In this report | Why |
|---|---|---|
| Data center accelerators | Included with on-package HBM, USD 169.77 billion in 2025 | HBM is sold as part of the accelerator package |
| Client devices | Only the NPU block value, USD 5.13 billion in 2025 | Counting the whole PC or phone processor would add CPU and graphics value |
| Servers and systems | Excluded | Boards, CPUs, networking and chassis belong to the server market |
| Cloud rental | Excluded | Rental revenue would count the same chip many times |
| In-house chips | Included at estimated cost value | Google, Amazon Web Services and Microsoft chips displace purchased GPUs |
Market Drivers: Why Did AI Chip Spending Jump in 2026?
Three drivers add USD 655.63 billion of annual AI chip value between 2025 and 2035: data center revenue that more than doubled in mid-2026, gigawatt supply agreements, and inference spreading to vehicles, PCs and machines.
NVIDIA Data Center Revenue Rose 117% in the Quarter to July 2026
Data center AI chip demand accelerated again in 2026. NVIDIA reported second-quarter fiscal 2027 revenue of USD 96.20 billion, up 106%, with data center revenue of USD 89.00 billion, up 117%, and guided third-quarter revenue to USD 108.00 billion, plus or minus 2% (Source: NVIDIA second-quarter fiscal 2027 release). Advanced Micro Devices (AMD) reported Data Center segment revenue of USD 6.70 billion for the second quarter of 2026, up 107% on EPYC and Instinct demand (Source: AMD second-quarter 2026 results). These results lift the 2026 data center segment to USD 305.59 billion in the model, 94.4% of 2026 AI chip value.
Broadcom’s Custom AI Revenue Tripled as Gigawatt Contracts Started Shipping
AI labs now buy chips by the gigawatt (GW). Broadcom reported AI semiconductor revenue of USD 16.70 billion for its quarter ended August 2, 2026, up 221%, and guided USD 21.70 billion for the next quarter (Source: Broadcom Form 8-K). In October 2025, OpenAI and Broadcom agreed to deploy 10 GW of custom AI accelerators from the second half of 2026 to the end of 2029, according to the OpenAI announcement, and AMD and OpenAI agreed a 6 GW deal that starts with 1 GW of Instinct MI450 GPUs in the second half of 2026 (Source: AMD press release). DC Market Insights estimates the accelerator content of one gigawatt of AI capacity at USD 17 billion to USD 22 billion at 2025 prices, so these two programs alone exceed a year of 2025 market value.
Inference Rises from 46.2% to 65.3% of Value
Inference held 46.2% of 2025 value against 46.9% for training, and grows at 20.42% a year to 65.3% of the 2035 market, because every deployed model serves requests for years and every edge chip is an inference chip. NVIDIA states that its Rubin platform, made up of six new chips, will deliver up to a 10x reduction in inference token cost (Source: NVIDIA fiscal 2026 release), which widens the set of workloads worth running on accelerators.
Market Trends: How Are Custom Silicon and On-Device NPUs Changing AI Chips?
AI chips are moving to custom silicon and on-device NPUs, with AI ASICs and SoCs rising from 17.6% of value in 2025 to 29.6% by 2035.
Custom Silicon Rises from 17.6% to 29.6% of Spending
Cloud providers design their own chips to cut the cost of inference at scale. Microsoft’s Maia 200 inference accelerator is built on TSMC’s 3-nanometer process with more than 140 billion transistors and 216 gigabytes (GB) of HBM3e at 7 terabytes per second (TB/s), and runs in Microsoft’s US Central region near Des Moines, Iowa (Source: Microsoft announcement reported by HPCwire). Google TPUs, Amazon Web Services Trainium chips from Amazon.com and Microsoft Maia form most of the custom data center ASIC segment in the DC Market Insights estimate. The AI ASIC and SoC segment grows to 7.6 times its 2025 value by 2035.
NPUs Above 40 TOPS Become Standard in New PCs
Microsoft defines Copilot+ PCs as Windows 11 hardware with an NPU that performs more than 40 trillion operations per second (TOPS) (Source: Microsoft Learn). Intel’s Core Ultra Series 3, its first AI PC platform on the Intel 18A process, offers up to 50 TOPS of NPU performance in more than 200 designs (Source: StorageReview report), and AMD introduced Ryzen AI 400 Series platforms at CES 2026 (Source: AMD investor relations). Client NPUs grow at 14.85% a year in the DC Market Insights model.
Market Challenges: What Holds the AI Chip Market Back?
Export controls and power availability are the two constraints that hold the AI Chip Market below unconstrained demand, with China growing at 15.45% a year, below the Asia Pacific rate of 16.74%.
Export Controls Shut Leading GPUs Out of China
US export rules decide which AI chips can be sold into China, the second-largest country market with 12.4% of 2025 value. AMD’s 2025 results included about USD 440 million of inventory and related charges from US export controls on its Instinct MI308 products (Source: AMD investor relations). In May 2025, the US Department of Commerce rescinded the AI Diffusion Rule and warned industry about using specific Huawei Ascend chips (Source: Bureau of Industry and Security announcement). NVIDIA’s third-quarter fiscal 2027 outlook assumes no data center compute revenue from China (Source: NVIDIA release), so domestic Chinese chips fill most of that demand in the model.
Power Limits Decide Where Accelerators Can Run
Qualcomm’s AI200 rack-scale inference systems draw 160 kilowatts (kW) per rack, according to HPCwire, and gigawatt programs need new grid connections at campus scale. Each gigawatt of AI capacity absorbs about 1.0 million to 1.3 million accelerators at Blackwell-generation power levels, so a delayed grid connection is a delayed chip shipment. Racks at these densities need cold plates, sized in the Direct-to-Chip Liquid Cooling Market. The low scenario models a two-year slip in AI power delivery and ends 25.5% below the base case in 2035.
Market Opportunities: Where Do Inference and Edge Chips Open New Revenue Pools?
The two largest new revenue pools are inference accelerators from new suppliers and edge AI chips for vehicles and machines, which grow at 21.54% and 18.06% a year.
Inference Accelerators Open the Data Center to New Suppliers
Inference rewards memory capacity and cost per token more than peak training throughput. Qualcomm plans AI200 systems for 2026 and AI250 for 2027, with 768 GB of low-power DDR memory per AI200 card, and Saudi AI company Humain plans up to 200 megawatts (MW) of Qualcomm AI systems (Source: HPCwire report). Other AI Chips, the category most new inference suppliers sell into, grow at 21.54% a year in the DC Market Insights model.
Vehicles, Robots and Cameras Carry Edge AI Chip Growth
Driver assistance, robots and smart cameras run AI at the edge, where latency rules out the cloud. Mobileye’s 2025 revenue rose 15% to USD 1.89 billion (Source: Mobileye investor relations), NVIDIA’s automotive revenue rose 39% to USD 2.30 billion in fiscal 2026 (Source: NVIDIA filing), and Horizon Robotics delivered more than four million Journey-series chip sets in 2025, up 39%, according to Gasgoo. Automotive chips grow at 17.04% a year and robotics and industrial edge chips at 18.06%; both are sized in detail in the Edge AI Chip Market.
AI Chip Price: How Much Does an AI Chip Cost in 2025?
A data center GPU sold for about USD 22,060 on average in 2025, a custom data center AI ASIC for about USD 5,120 and an automotive AI SoC for about USD 310 (DC Market Insights estimates).
| AI chip class (2025) | Average selling price or value (USD) | Units (million) | Value (USD billion) |
|---|---|---|---|
| Data center GPUs | 22,060 | 6.30 | 138.98 |
| Data center custom AI ASICs | 5,120 | 5.18 | 26.52 |
| Automotive AI SoCs | 310 | 20.7 | 6.42 |
| Robotics and industrial edge AI chips | 188 | 20.95 | 3.94 |
| NPU value per smartphone | 6.10 | 590 | 3.60 |
| NPU value per PC | 15.30 | 100 | 1.53 |
Prices are blended averages across all models, including on-package memory and excluding the board, server or vehicle around the chip. Data center FPGAs and other accelerators add USD 4.27 billion. Client devices ship most AI chips but carry only 2.8% of value, because a smartphone NPU is worth about 1/3,600 of a data center GPU.
Standards and Regulation: Which Rules Shape AI Chip Design and Sales?
Four rule sets shape AI chips: the JEDEC HBM4 memory standard, the UALink scale-up specification, US export controls and the European Union (EU) AI Act.
JEDEC HBM4 (JESD270-4). The JEDEC Solid State Technology Association (JEDEC) published the JEDEC JESD270-4 HBM4 standard, released in April 2025, supports 4-high to 16-high DRAM stacks and up to 2 TB/s per stack.
UALink 200G 1.0. The UALink 200G 1.0 specification, released in April 2025, enables 200G-per-lane scale-up links for up to 1,024 accelerators in one pod (Source: Ultra Accelerator Link Consortium), which gives chip makers other than NVIDIA an open scale-up fabric.
US export controls. Rules administered by the Bureau of Industry and Security decide which AI chips can ship to China and other controlled destinations; China holds 12.4% of 2025 value in the model.
EU AI Act. Obligations for providers of general-purpose AI models apply from 2 August 2025, and models trained with more than 10^25 floating-point operations are presumed to pose systemic risk, a threshold the European Commission says is under review (Source: European Commission). The rule regulates models, not chips.
Market Segmentation: Which AI Chip Segment Leads and Which Is Fastest Growing?
GPUs lead the AI Chip Market with 76.9% of 2025 value, and AI ASICs and SoCs are the fastest-growing AI chip segment at 22.51% a year, against 14.40% for GPUs, as cloud providers and AI labs adopt their own designs.
By Chip Type: GPUs Lead with 76.9%
| Chip type | 2025 (USD billion) | Share 2025 | 2035 (USD billion) | CAGR 2025-2035 |
|---|---|---|---|---|
| GPUs | 142.38 | 76.9% | 546.71 | 14.40% |
| AI ASICs and SoCs | 32.64 | 17.6% | 248.59 | 22.51% |
| Client NPUs | 5.13 | 2.8% | 20.48 | 14.85% |
| FPGAs | 2.32 | 1.3% | 5.50 | 9.03% |
| Other AI Chips | 2.79 | 1.5% | 19.61 | 21.54% |
GPUs lose 11.9 points of share by 2035 but still grow 3.8 times in value, because their software ecosystem keeps them the default for training. Other AI Chips are the second-fastest chip type at 21.54%.
By Deployment: Data Centers Lead with 91.6%
| Deployment | 2025 (USD billion) | Share 2025 | 2035 (USD billion) | CAGR 2025-2035 |
|---|---|---|---|---|
| Data Center | 169.77 | 91.6% | 768.72 | 16.30% |
| Edge and Device | 15.49 | 8.4% | 72.17 | 16.64% |
Data center chips grow at 16.30% a year and edge and device chips at 16.64%. NVIDIA reported Edge Computing revenue of USD 7.20 billion for its second quarter of fiscal 2027, up 27% (Source: NVIDIA release).
By Function: AI Training Leads with 46.9%
| Function | 2025 (USD billion) | Share 2025 | 2035 (USD billion) | CAGR 2025-2035 |
|---|---|---|---|---|
| AI Training | 86.92 | 46.9% | 257.52 | 11.47% |
| AI Inference | 85.61 | 46.2% | 548.78 | 20.42% |
| HPC and Other | 12.73 | 6.9% | 34.59 | 10.51% |
Inference passes training within the forecast period, while high-performance computing (HPC) and scientific computing fall to 4.1% of value by 2035.
By End Use: Hyperscale Cloud Providers Lead with 56.5%
| End use | 2025 (USD billion) | Share 2025 | 2035 (USD billion) | CAGR 2025-2035 |
|---|---|---|---|---|
| Hyperscale Cloud Providers | 104.75 | 56.5% | 445.86 | 15.59% |
| Enterprises and Government | 39.90 | 21.5% | 211.40 | 18.15% |
| GPU Cloud and Neocloud Providers | 25.13 | 13.6% | 111.46 | 16.07% |
| Automotive | 6.42 | 3.5% | 30.96 | 17.04% |
| Consumer Devices | 5.13 | 2.8% | 20.48 | 14.85% |
| Robotics and Industrial Edge | 3.94 | 2.1% | 20.73 | 18.06% |
Enterprises and government grow fastest at 18.15% a year as sovereign AI programs and private AI clusters scale, and robotics and industrial edge buyers follow at 18.06% as factories, warehouses and cities add vision and robot control.
DC Exclusive: AI Chip Value Map, 4 Deployments by 5 Chip Types (USD 185.26 Billion, 2025)
Data center GPUs are the largest cell of the value map at 75.0% of all 2025 AI chip value. The map is a DC Market Insights model built from 59 inputs and tested against 3 bound checks.
| 2025, USD billion | GPUs | AI ASICs and SoCs | Client NPUs | FPGAs | Other AI Chips | Total | 2035 total |
|---|---|---|---|---|---|---|---|
| Data Center | 138.97 | 26.52 | 0.00 | 2.00 | 2.27 | 169.77 | 768.72 |
| Automotive | 1.99 | 4.43 | 0.00 | 0.00 | 0.00 | 6.42 | 30.96 |
| Consumer Devices | 0.00 | 0.00 | 5.13 | 0.00 | 0.00 | 5.13 | 20.48 |
| Robotics and Industrial Edge | 1.42 | 1.69 | 0.00 | 0.32 | 0.51 | 3.94 | 20.73 |
| Total | 142.38 | 32.64 | 5.13 | 2.32 | 2.79 | 185.26 | 840.89 |
ASICs already hold 69.0% of automotive AI chip value, against 15.6% in the data center, because carmakers standardized on dedicated driving SoCs years before cloud providers built their own accelerators. Robotics and industrial edge buyers use the most varied mix, with no chip type above 43.0% of the row.
Regional Insights: Which Region Leads the AI Chip Market?
North America leads the AI Chip Market with 56.4% of 2025 value. The Middle East and Africa is the fastest-growing region for AI chips at 20.23% a year, because Gulf AI programs install accelerators from a small base.
| Region | 2025 (USD billion) | Share 2025 | 2035 (USD billion) | CAGR 2025-2035 |
|---|---|---|---|---|
| North America | 104.42 | 56.4% | 438.67 | 15.43% |
| Asia Pacific | 49.69 | 26.8% | 233.60 | 16.74% |
| Europe | 18.47 | 10.0% | 89.86 | 17.14% |
| Middle East and Africa | 8.80 | 4.8% | 55.52 | 20.23% |
| Latin America | 3.88 | 2.1% | 23.23 | 19.60% |
North America Leads with 56.4% Share
North America grows at 15.43% a year in the DC Market Insights model. The 10 GW Broadcom and 6 GW AMD programs with OpenAI both begin deliveries in the second half of 2026, and the region loses 4.2 points of share by 2035 as other regions build their own AI capacity.
Asia Pacific Holds 26.8% Share
Asia Pacific grows at 16.74% a year. The region holds about half of edge and device AI chip value, because most smartphones, PCs and vehicles with AI processors are built and sold there.
Europe Holds 10.0% Share
Europe grows at 17.14% a year. The United Kingdom is the largest European market with 2.3% of global 2025 value, ahead of Germany, where automotive AI chips and industrial automation add edge demand.
Middle East and Africa Holds 4.8% Share
The Middle East and Africa grows at 20.23% a year, the fastest of the five regions. Saudi Arabia and the United Arab Emirates account for most of the region, and Humain’s plan for up to 200 MW of Qualcomm AI systems adds inference capacity in Saudi Arabia (Source: HPCwire report).
Latin America Holds 2.1% Share
Latin America grows at 19.60% a year, led by Brazil and Mexico, where cloud regions add accelerator capacity from a small base.
Country Analysis: How Big Is the United States Artificial Intelligence Chip Market?
The United States artificial intelligence chip market holds 52.0% of 2025 global value, the largest of any country (DC Market Insights estimate).
United States: 52.0% of Global AI Chip Value and 15.26% a Year to 2035
DC Market Insights puts the United States at about 51.5% of the 2026 AI Chip Market, and its value grows at 15.26% a year to 2035, with the absolute figures in the country table below. The United States leads because the largest cloud providers and AI labs install most of their accelerators there: Microsoft runs Maia 200 accelerators in its US Central region in Iowa, and the first gigawatt of the AMD and OpenAI program lands in the second half of 2026. US share falls from 52.0% to 47.4% by 2035 as India, the Gulf and Europe build capacity. China follows with 12.4% of 2025 value and Canada with 4.3%; the 12 largest countries hold 86.8% of value.
| Rank | Country | Region | 2025 (USD billion) | Share 2025 | 2035 (USD billion) | CAGR 2025-2035 |
|---|---|---|---|---|---|---|
| 1 | United States | North America | 96.30 | 52.0% | 398.52 | 15.26% |
| 2 | China | Asia Pacific | 22.94 | 12.4% | 96.50 | 15.45% |
| 3 | Canada | North America | 8.01 | 4.3% | 39.52 | 17.31% |
| 4 | Japan | Asia Pacific | 6.99 | 3.8% | 29.37 | 15.44% |
| 5 | South Korea | Asia Pacific | 4.67 | 2.5% | 22.46 | 17.00% |
| 6 | United Kingdom | Europe | 4.34 | 2.3% | 19.06 | 15.95% |
| 7 | Germany | Europe | 3.82 | 2.1% | 17.75 | 16.62% |
| 8 | India | Asia Pacific | 3.60 | 1.9% | 27.47 | 22.54% |
| 9 | Saudi Arabia | Middle East and Africa | 3.18 | 1.7% | 21.55 | 21.08% |
| 10 | United Arab Emirates | Middle East and Africa | 2.71 | 1.5% | 18.00 | 20.84% |
| 11 | France | Europe | 2.65 | 1.4% | 13.46 | 17.64% |
| 12 | Taiwan | Asia Pacific | 1.64 | 0.9% | 7.65 | 16.69% |
India is the fastest-growing large country market at 22.54% a year, as hyperscale operators and domestic cloud providers build AI capacity from a small base. Italy, Spain and the Netherlands sit in the rest of Europe, which holds 4.1% of 2025 value outside the United Kingdom, Germany and France. The country figures are a DC Market Insights allocation of the regional totals, weighted by each country’s estimated share of AI data center capacity and of AI device and vehicle sales.
Forecast Scenarios: What Could Change the 2035 AI Chip Forecast?
The AI Chip Market reaches USD 840.89 billion by 2035 in the base case, with a range of USD 626.59 billion to USD 1,016.76 billion across the low and high scenarios.
| Scenario | Assumption from 2026 | 2035 (USD billion) | CAGR 2025-2035 |
|---|---|---|---|
| Low | Two-year slip in AI power delivery; AI capital spending flat in real terms after 2028; edge and device value 20% below base | 626.59 | 12.96% |
| Base | Announced gigawatt programs delivered by 2030; AI ASICs and SoCs reach 29.6% of value | 840.89 | 16.33% |
| High | Grid and HBM supply keep pace with announced plans; edge and device value 20% above base | 1,016.76 | 18.56% |
A faster move to custom ASICs lowers the average price per chip by about three-quarters for each GPU it replaces, at USD 5,120 against USD 22,060, but raises unit volumes.
Competitive Insights: Who Leads the AI Chip Market?
NVIDIA leads the AI Chip Market with about 72% of 2025 value, and NVIDIA, Broadcom and AMD together hold more than 75% (DC Market Insights estimate).
- NVIDIA
- Advanced Micro Devices (AMD)
- Broadcom
- Google (TPU)
- Amazon Web Services (Trainium)
- Microsoft (Maia)
- Intel
- Qualcomm
- Huawei (Ascend)
- Mobileye
- Horizon Robotics
- Marvell Technology
- Cambricon Technologies
- Cerebras Systems
- SambaNova Systems
- Hailo
NVIDIA’s fiscal 2026 revenue reached USD 215.90 billion, up 65% (Source: NVIDIA filing), and its advantage is the CUDA software stack plus full rack systems. Broadcom is the largest custom AI ASIC partner, with USD 16.70 billion of AI semiconductor revenue in one quarter and the 10 GW OpenAI program. AMD sells Instinct GPUs with open software and wins large inference contracts. Intel carries its NPU strategy in Core Ultra Series 3. Qualcomm’s fiscal 2025 chip revenue was USD 38.37 billion (Source: Qualcomm earnings release), and it enters the data center with AI200 and AI250. In vehicles, Mobileye and Horizon Robotics compete with NVIDIA.
Recent Developments: Which AI Chip Deals and Results Moved the Market?
Six dated events between October 2025 and September 2026, each taken from a company release or filing, set the 2026 base of USD 323.66 billion (DC Market Insights estimate).
- In October 2025, AMD and OpenAI announced a 6 GW agreement for AMD GPUs, starting with 1 GW of Instinct MI450 in the second half of 2026 (Source: AMD press release).
- In October 2025, OpenAI and Broadcom agreed to deploy 10 GW of OpenAI-designed custom AI accelerators, targeted to start in the second half of 2026 and complete by the end of 2029 (Source: OpenAI announcement).
- In January 2026, Microsoft introduced its Maia 200 inference accelerator on TSMC’s 3-nanometer process with 216 GB of HBM3e (Source: Microsoft announcement).
- In May 2026, NVIDIA reported first-quarter fiscal 2027 data center revenue of USD 75.20 billion, of which compute was USD 60.40 billion (Source: NVIDIA investor relations).
- In August 2026, NVIDIA reported second-quarter fiscal 2027 data center revenue of USD 89.00 billion, up 117%, and said Vera Rubin was in full production (Source: NVIDIA earnings release).
- In September 2026, Broadcom reported third-quarter fiscal 2026 AI semiconductor revenue of USD 16.70 billion, up 221%, and guided USD 21.70 billion for the fourth quarter (Source: Broadcom Form 8-K).
Methodology: How We Built the AI Chip Market Model
DC Market Insights built this market bottom-up from units and prices in four deployment segments, with 59 inputs. The data center segment reuses the DC Market Insights Data Center Accelerator Market model: about 6.30 million GPUs at USD 22,060 and 5.18 million custom AI ASICs at USD 5,120 in 2025, plus FPGAs and other accelerators, re-based for 2026 on NVIDIA, AMD and Broadcom results to August 2026. The edge and device segments are DC Market Insights estimates built from the unit and price table above. Three bound checks frame the result. A floor: the disclosed 2025 automotive revenue of Mobileye, NVIDIA and Horizon Robotics product and solutions sums to about USD 4.42 billion, below the USD 6.42 billion automotive segment, which also covers other suppliers and in-house chips. A ceiling: client NPU value equals about 8.6% of the USD 59.99 billion that Qualcomm’s handset chips and Intel’s Client Computing Group sold in their latest fiscal years. A top-down check: NVIDIA’s fiscal 2026 data center revenue of USD 193.70 billion, which also includes networking, CPUs and systems, exceeds the USD 169.77 billion data center segment, and TSMC reported that AI accelerators made up a high-teens percentage of its 2025 revenue (Source: TSMC earnings call). The total was split by 5 chip types, 2 deployments, 3 functions, 6 end uses, 5 regions and 12 countries, and every split sums to the market total. The full approach is on our research methodology page. The analyst named on this page built the model, and the reviewer checked the arithmetic, the sources and the dates before publication.
Table of contents
- 01Introduction
- 1.1Market Definition: What Is an AI Chip
- 1.2Chips Included and Excluded
- 1.3How the Segments Fit Together
- 1.4Why AI Chip Market Estimates Differ
- 02Executive Summary
- 2.1Market Snapshot, 2025, 2026 and 2035
- 2.2Key Market Statistics, 2026
- 2.3Market Size, 2020-2035
- 03Market Dynamics
- 3.1NVIDIA Data Center Revenue Rose 117% in the Quarter to July 2026
- 3.2Broadcom's Custom AI Revenue Tripled as Gigawatt Contracts Started Shipping
- 3.3Inference Rises from 46.2% to 65.3% of Value
- 3.4Custom Silicon Rises from 17.6% to 29.6% of Spending
- 3.5NPUs Above 40 TOPS Become Standard in New PCs
- 3.6Export Controls Shut Leading GPUs Out of China
- 3.7Power Limits Decide Where Accelerators Can Run
- 3.8Inference Accelerators Open the Data Center to New Suppliers
- 3.9Vehicles, Robots and Cameras Carry Edge AI Chip Growth
- 04Pricing Analysis
- 4.1Average Selling Price and Units by Chip Class, 2025
- 05Standards and Regulation
- 5.1JEDEC HBM4 (JESD270-4)
- 5.2UALink 200G 1.0
- 5.3US Export Controls
- 5.4EU AI Act
- 06AI Chip Market, by Chip Type
- 6.1GPUs
- 6.2AI ASICs and SoCs
- 6.3Client NPUs
- 6.4FPGAs
- 6.5Other AI Chips
- 07AI Chip Market, by Deployment
- 7.1Data Center
- 7.2Edge and Device
- 08AI Chip Market, by Function
- 8.1AI Training
- 8.2AI Inference
- 8.3HPC and Other
- 09AI Chip Market, by End Use
- 9.1Hyperscale Cloud Providers
- 9.2Enterprises and Government
- 9.3GPU Cloud and Neocloud Providers
- 9.4Automotive
- 9.5Consumer Devices
- 9.6Robotics and Industrial Edge
- 10DC Exclusive: AI Chip Value Map, 4 Deployments by 5 Chip Types
- 10.1Value Map, 2025, with 2035 Totals
- 11AI Chip Market, by Region
- 11.1North America
- 11.2Asia Pacific
- 11.3Europe
- 11.4Middle East and Africa
- 11.5Latin America
- 12Country Analysis
- 12.1United States Artificial Intelligence Chip Market, 2025, 2026 and 2035
- 12.2China
- 12.3Canada
- 12.4Japan
- 12.5South Korea
- 12.6United Kingdom
- 12.7Germany
- 12.8India
- 12.9Saudi Arabia
- 12.10United Arab Emirates
- 12.11France
- 12.12Taiwan
- 13Forecast Scenarios
- 13.1Low Scenario
- 13.2Base Scenario
- 13.3High Scenario
- 14Competitive Landscape
- 14.1NVIDIA
- 14.2Advanced Micro Devices (AMD)
- 14.3Broadcom
- 14.4Google (TPU)
- 14.5Amazon Web Services (Trainium)
- 14.6Microsoft (Maia)
- 14.7Intel
- 14.8Qualcomm
- 14.9Huawei (Ascend)
- 14.10Mobileye
- 14.11Horizon Robotics
- 14.12Marvell Technology
- 14.13Cambricon Technologies
- 14.14Cerebras Systems
- 14.15SambaNova Systems
- 14.16Hailo
- 15Recent Developments
- 15.1Deals and Results, October 2025 to September 2026
- 16Research Methodology
- 16.1Units and Price Build
- 16.2Bound Checks
- Fig. 1AI Chip Market Size, 2020-2035 (USD billion)
- Table 1AI Chip Market Snapshot, 2025, 2026 and 2035
- Table 2Scope Comparison: What This Market Includes
- Table 3Average Selling Price and Units by Chip Class, 2025
- Table 4AI Chip Market by Chip Type, 2025 and 2035 (USD billion)
- Table 5AI Chip Market by Deployment, 2025 and 2035 (USD billion)
- Table 6AI Chip Market by Function, 2025 and 2035 (USD billion)
- Table 7AI Chip Market by End Use, 2025 and 2035 (USD billion)
- Table 8AI Chip Value Map, 2025 (USD billion)
- Table 9AI Chip Market by Region, 2025 and 2035 (USD billion)
- Table 10Top 12 Countries, 2025 and 2035 (USD billion)
- Table 11Forecast Scenarios, 2035 (USD billion)
About this report
Written by Amit Jain and reviewed by Deepti Agrawal, Senior Editor, Research. Figures are built top-down and bottom-up and reconciled before publication, with 2025 as the base year.
Read our methodologyHow we built this
- Historical period2020-2024
- Base year2025
- Forecast period2026-2035
- Sizing approachTop-down + bottom-up
Need more than the report?
Advisory on this market
Due diligence, site selection and market entry work, by the analysts who wrote this report.
See consulting servicesFrequently asked questions
USD 323.66 billion in 2026, up 74.7% from USD 185.26 billion in 2025, according to DC Market Insights estimates. The market is projected to reach USD 840.89 billion by 2035, a CAGR of 16.33% from 2025 to 2035.
16.33% a year from 2025 to 2035. Growth was faster, at 68.67% a year, between 2020 and 2025, and 2026 adds 74.7% as NVIDIA data center revenue rose 117% in the quarter to July 2026.
76.9% of AI chip value in 2025 came from GPUs. An AI chip is a processor whose main job is AI computation: data center GPUs, custom AI ASICs and SoCs, NPUs inside PCs and phones, FPGAs used for AI and other accelerators.
22.51% a year for AI ASICs and SoCs from 2025 to 2035, the fastest chip type, as cloud providers and AI labs design their own inference chips. Their share rises from 17.6% to 29.6% of value.
76.9% of 2025 value comes from GPUs, the leading chip type. GPUs grow at 14.40% a year and reach 3.8 times their 2025 value by 2035.
About USD 22,060 for a data center GPU in 2025, USD 5,120 for a custom data center AI ASIC and USD 310 for an automotive AI SoC, according to DC Market Insights estimates.
52.0% of global AI chip value in 2025, the largest of any country, and about 51.5% in 2026 (DC Market Insights estimate). The United States grows at 15.26% a year to 2035, when it holds 47.4% of the global market.
56.4% of 2025 value sits in North America, the leading region. The Middle East and Africa grows fastest at 20.23% a year, as Gulf AI programs install accelerators from a small base.
20.23% a year makes the Middle East and Africa the fastest-growing region for vendors, while North America, with 56.4% of 2025 value, remains the largest and most contested region.
USD 323.66 billion in 2026 counts chips at first sale with on-package memory. Estimates that count only data center accelerators land near USD 305.59 billion, and estimates that count whole servers or device processors land far higher.
1.5% of 2025 AI chip value sits in Other AI Chips, the segment that includes analog and in-memory compute chips. DC Market Insights does not size analog AI chips separately because they are not yet sold in volume.
USD 323.66 billion in 2026 covers both, according to DC Market Insights estimates. Deep learning chips and AI chipsets are other names for the AI chips counted in this market, from data center GPUs to client NPUs, each counted once at first sale.
About 72% of 2025 value goes to NVIDIA, the leader (DC Market Insights estimate). AMD, Broadcom, Google, Amazon Web Services, Microsoft, Intel, Qualcomm, Huawei, Mobileye, Horizon Robotics, Marvell Technology, Cambricon Technologies, Cerebras Systems, SambaNova Systems and Hailo also compete.
Get this report
How do I get the full report?
Request a quote; we reply by email within one business day.
How and when will I receive the report?
By email, within 24-48 business hours of payment.
How can I pay?
Once you accept the quote, we email you a secure payment link.
Can I see a sample first?
Yes. Request a free sample and we will email it to you.
Can the report be tailored to my needs?
Yes. We can add countries, segments or data cuts. Talk to an analyst about the scope you need.
Can I get an invoice or pay against a purchase order?
Write to sales@dcmarketinsights.com and our team will help.