
High End AI Server PCB Market Size, Share & Forecast to 2035
Market at a glance
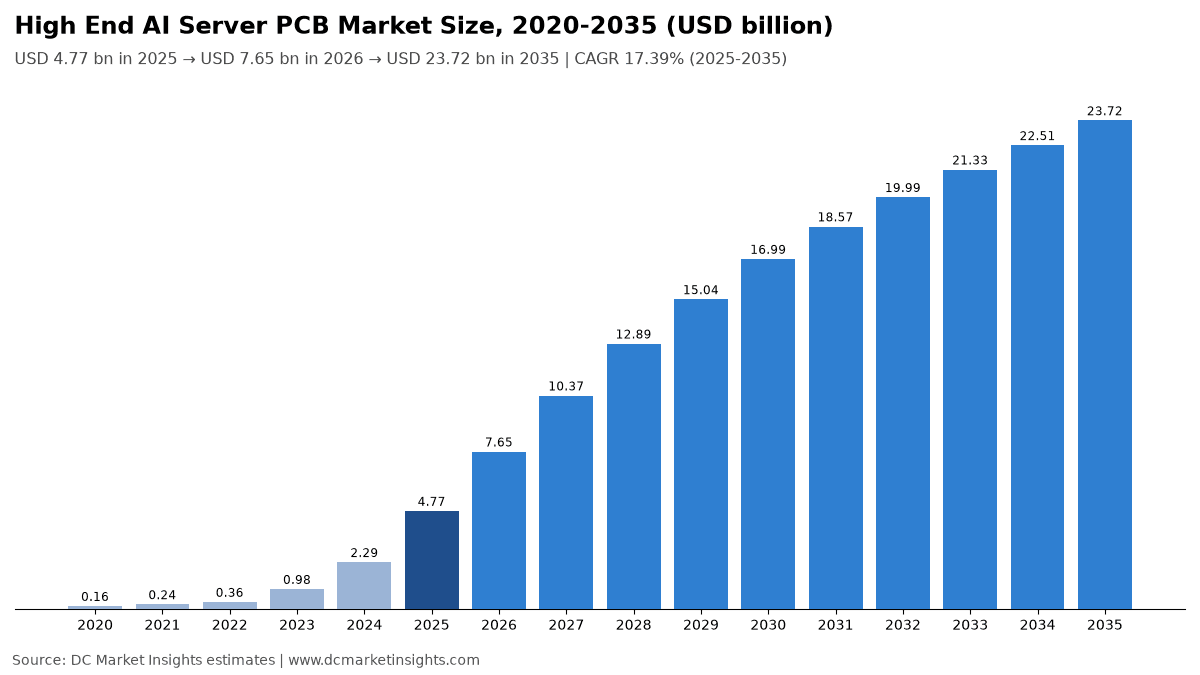
The High End AI Server PCB market was worth USD 4,770.0 million in 2025 and is forecast to reach USD 23.72 billion by 2035, growing at a 17.39% CAGR.
 By Amit Jain, Senior Consultant, ICT & Emerging Technologies
 Reviewed by Deepti Agrawal
Last updated 26 Oct 2026
Base year 2025 PDF + Excel
Key findings
Rack-Scale Systems Turn One Server Board into Four
Thailand Draws More Than THB 200 Billion of PCB Projects
USD 14.23 billion of Extreme Low Loss Boards by 2035
What is inside the report
- 01Introduction
- 02Executive Summary
- 03Market Scope
- 04Why Market Estimates Differ
- 05Market Drivers
- 06Market Trends
- 07Market Challenges and Restraints
- 08Market Opportunities
- 09Pricing Analysis
- 10Standards and Regulation
- 19chapters
- 2020-2024Historical period
- 2026-2035Forecast period
- —Companies profiled
Segmentation
Full analysis
The High End AI Server PCB Market is valued at USD 7.65 billion in 2026 and is projected to reach USD 23.72 billion by 2035, up from USD 4.77 billion in 2025, a CAGR of 17.39% from 2025 to 2035 (DC Market Insights estimate). Board value here follows layer count and laminate loss grade, not server count: a 72-GPU rack shipped in 2025 carried about USD 40,320 of bare printed circuit boards (PCBs) across its accelerator modules, compute trays, switch trays and host boards, against about USD 18,720 for the same 72 GPUs in 2020-era eight-GPU servers. Victory Giant Technology, the largest supplier, booked RMB 8.34 billion of artificial intelligence (AI) and high-performance computing (HPC) revenue in 2025, 43.2% of its sales, and lifted its gross margin to 35.22% on high-order high-density interconnect (HDI) boards (Victory Giant 2025 financial report, March 2026). The next step is a board that did not exist before: NVIDIA’s Kyber rack for Rubin Ultra, shown at its GTC conference in March 2025 for the second half of 2027, swaps cable cartridges for a PCB midplane, so scale-up switch tray boards and midplanes grow fastest at 24.28% a year, while the Middle East and Africa is the fastest deployment region at 21.30%.
Key Market Statistics: How Big Is the High End AI Server PCB Market in 2026?
DC Market Insights values the High End AI Server PCB Market at USD 7.65 billion in 2026, 60.34% above the USD 4.77 billion of 2025, because AI accelerator shipments rise from 11.48 million to 16.00 million and PCB content per graphics processing unit (GPU) climbs from USD 560 to USD 640.
- Market size 2025: USD 4.77 billion; 2026: USD 7.65 billion; 2030: USD 16.99 billion; 2035: USD 23.72 billion.
- CAGR 2025-2035: 17.39% in the base case; the 2035 range runs from USD 18.02 billion (low, 14.21%) to USD 28.93 billion (high, 19.75%).
- PCB content: USD 560 per GPU and USD 240 per custom application-specific integrated circuit (ASIC) in 2025, rising to USD 920 and USD 410 by 2035 (DC Market Insights estimates).
- Largest board type: high-layer multilayer boards of 18 to 30 layers, USD 1.81 billion or 38.0% of 2025 value; fastest: ultra-high-layer boards above 30 layers, 20.20% a year.
- Largest board application: baseboards and compute tray boards, USD 2.00 billion in 2025; fastest: scale-up switch tray boards and midplanes, 24.28% a year.
- Fastest laminate grade: extreme low loss (M8 and M9 class), from USD 954.24 million to USD 14.23 billion, 31.02% a year.
- Custom ASIC servers grow 19.43% a year, against 16.59% for GPU-based AI servers.
- Leading region: North America, USD 2.83 billion (59.4%) in 2025; fastest region: Middle East and Africa, 21.30% a year.
- Largest country: United States, USD 2.61 billion in 2025; fastest large country: India, 25.10% a year.
- Market leader: Victory Giant Technology, with about 18% of 2025 value; the top five suppliers hold about 55% (DC Market Insights estimate).
Executive Summary: How Fast Is Spending on AI Server Circuit Boards Growing?
The Global High End AI Server PCB Market size was valued at USD 159.00 million in 2020, reached USD 4.77 billion in 2025, and is anticipated to reach USD 23.72 billion by 2035, at a CAGR of 17.39% during the forecast period.
| Attribute | Value |
|---|---|
| Historical period | 2020-2024 |
| Base year | 2025 |
| Forecast period | 2026-2035 |
| Market size 2025 | USD 4.77 billion |
| Market size 2026 | USD 7.65 billion |
| CAGR 2025-2035 | 17.39% |
| Market size 2035 | USD 23.72 billion |
Spending grew 97.44% a year from 2020 to 2025 because accelerator shipments rose from about 0.80 million to 11.48 million and the boards under each accelerator moved from 16 to 20 layers on standard low-loss laminate to 26 to 40 layers and 5+N HDI on ultra low loss material. NVIDIA’s data center revenue of USD 193.7 billion in the year to January 2026, up 68%, sets the scale of the systems these boards carry (NVIDIA FY2026 results, February 2026). TTM Technologies, the largest PCB maker based in the United States, drew 24% of its USD 2.91 billion of 2025 sales from data center computing and ended the year with a book-to-bill ratio of 1.35 (TTM Technologies 2025 results, February 2026). Growth slows to 17.39% a year after 2025 because unit shipments flatten after 2028, while value per accelerator keeps rising as M8 and M9 laminates and midplanes spread.
What Counts as a High End AI Server PCB?
The High End AI Server PCB Market covers USD 4.77 billion in 2025 of bare printed circuit boards sold for AI servers and their scale-up switch trays, valued at the board maker’s selling price before components are mounted.
Included: accelerator module boards such as Open Accelerator Module (OAM) and GPU module boards, multi-accelerator baseboards and compute tray boards, scale-up switch tray boards and rack midplanes, and the host, management and power distribution boards inside AI servers, built as high-layer multilayer boards (18 layers and more) or high-order HDI boards on low-loss laminate.
Excluded: integrated circuit (IC) package substrates such as Ajinomoto build-up film (ABF) substrates, boards for scale-out Ethernet and InfiniBand switches, optical transceiver boards, boards in general-purpose central processing unit (CPU) servers without accelerators, printed circuit board assembly (PCBA) value, and copper-clad laminate (CCL) sold as a material.
How the segments fit together: board type, board application, accelerator platform, laminate loss grade and production base each split the same USD 4.77 billion of 2025; regions and countries are counted where the AI servers are deployed, while the production base shows where the boards are made.
Why Do High End AI Server PCB Market Estimates Differ?
Estimates differ mainly by what they add to the USD 7.65 billion of 2026 that DC Market Insights counts for AI server and scale-up switch boards only.
Broader definitions add server PCB demand from general-purpose CPU servers, network switch and router boards for scale-out fabrics, optical module boards, IC substrates for GPUs and high bandwidth memory (HBM), and sometimes the full assembled board value, so a “server PCB” or “AI PCB” total can come out two to three times larger. DC Market Insights keeps IC substrates, PCBA and copper-clad laminate out because different buyers purchase them at different points of the supply chain.
| Element | In this estimate | Why |
|---|---|---|
| Accelerator module, baseboard and compute tray boards | Yes, USD 3.44 billion in 2025 | Core of every AI server |
| Scale-up switch tray boards and midplanes | Yes, USD 620.26 million in 2025 | Shipped inside the AI rack |
| Host, management and power boards in AI servers | Yes, USD 715.68 million in 2025 | Part of the AI server bill of materials |
| Scale-out switch and router boards | No | Bought as networking gear |
| IC substrates (ABF and BT) | No | Bought by chip packagers |
| General-purpose server boards | No | No accelerator in the system |
Buyers inside the scope include original design manufacturers (ODMs) that assemble racks for hyperscalers, server brands such as Dell Technologies, Hewlett Packard Enterprise and Supermicro, accelerator makers that buy module boards directly, and small and mid-sized GPU cloud providers and enterprises that order through these channels.
Market Drivers: What Is Pushing AI Server PCB Spending Up?
Three drivers lift PCB content per GPU from USD 560 in 2025 to USD 850 by 2030, a 52% rise on top of unit growth.
Rack-Scale Systems Turn One Server Board into Four
Rack-scale systems put module boards, compute tray boards, switch tray boards and a host board behind every group of GPUs; DC Market Insights estimates USD 40,320 of bare boards per 72-GPU rack in 2025 against USD 18,720 for the same number of GPUs in 2020 baseboard servers. NVIDIA contributed its Vera Rubin compute tray design, in which a PCB midplane replaces cable connections, to the Open Compute Project (OCP) in October 2025. Scale-up switch tray boards and midplanes rise from USD 620.26 million in 2025 to USD 5.45 billion by 2035.
Kyber Midplane Plan for the Second Half of 2027
NVIDIA’s Kyber rack for Rubin Ultra NVL576, presented at GTC in March 2025 for the second half of 2027 at about 600 kilowatts (kW) per rack, replaces cable cartridges with a midplane board, so ultra-high-layer boards above 30 layers grow from USD 1.43 billion in 2025 to USD 9.01 billion by 2035, 20.20% a year.
Victory Giant’s AI Revenue Rises Nearly Elevenfold
Victory Giant Technology reported RMB 19.29 billion of 2025 revenue, up 79.77%, of which RMB 8.34 billion came from AI and HPC boards and RMB 7.42 billion from HDI boards; its gross margin rose from 22.7% to 35.22% (Victory Giant 2025 annual report, March 2026). Buyers pay for HDI on GPU modules because it shortens signal paths under the accelerator, which is why high-order HDI grows 19.43% a year to USD 9.01 billion by 2035.
Market Trends: Where Are AI Server Boards Made Next?
Production moves out of China fastest to Thailand, which rises from USD 572.54 million of 2025 output to USD 5.22 billion by 2035, 24.73% a year.
Thailand Draws More Than THB 200 Billion of PCB Projects
More than 180 PCB projects worth over THB 200 billion applied for Thailand Board of Investment (BOI) promotion between 2022 and June 2025, according to BOI data, and the BOI approved a 6.15 billion baht prepreg and copper-clad laminate plant for Cheng Yi Technology in Chachoengsao on 1 November 2024, at the same meeting that approved two hyperscale data centers (Thailand BOI press release 151/2567, November 2024). Shennan Circuits started production at its Thailand plant in the second half of 2025.
Vietnam Becomes Victory Giant’s Second Base
Victory Giant Technology’s Vietnam unit reached about USD 470 million of revenue in 2025, up from RMB 1.08 billion in 2024 (company, April 2026), so Vietnam grows 25.82% a year in the production-base split, from USD 190.85 million to USD 1.90 billion.
Extreme Low Loss Laminate Becomes the Default
M8 and M9 class laminates rise from 20% of 2025 board value to 60% by 2035 because 224 gigabits per second (Gbps) serializer-deserializer (SerDes) lanes on the next accelerator generation need lower signal loss; very low loss M6 boards stay near USD 1.34 billion a year, growing 0.63%.
Market Challenges and Restraints: What Could Slow AI Server PCB Supply?
Two material limits sit behind the low case, which ends 2035 at USD 18.02 billion, 24% below the base.
Low-CTE Glass Cloth Stays Short Until FY2027
Nitto Boseki (Nittobo), the main supplier of low coefficient of thermal expansion (CTE) glass cloth, said in November 2025 that its capacity would rise only 10% to 20% in fiscal 2026 and double in fiscal 2027, and hyperscale buyers have booked most of the premium cloth. A board maker that cannot get cloth cannot press 30-layer laminate, so DC Market Insights holds 2026 growth to 60.34% even though accelerator units grow 39%.
Laminate Prices Up at Least 10% in the Second Quarter of 2026
Elite Material, the largest supplier of low-loss laminate, reported NT$94.3 billion of 2025 revenue, up 46.4%, and announced a laminate price rise of at least 10% for the second quarter of 2026, while the World Bank expects copper to average USD 12,000 per tonne in 2026, 20.6% above 2025. Board makers pass most of this on, but it squeezes margins on fixed-price host and power boards, which grow 16.59% a year.
Market Opportunities: Where Is the Money in AI Server PCBs?
The two largest pools of new money are M8 and M9 class boards, worth USD 14.23 billion by 2035, and custom ASIC racks, worth USD 7.34 billion.
USD 14.23 billion of Extreme Low Loss Boards by 2035
Extreme low loss boards grow from USD 954.24 million in 2025 to USD 14.23 billion by 2035; makers qualified on M9 class material and 40-plus layers at volume take most of this value because few lines can hold yield on boards that large.
Custom ASIC Racks Grow 19.43% a Year
Custom ASIC servers rise from USD 1.24 billion to USD 7.34 billion as cloud providers deploy their own accelerators; Meta alone guides USD 130 billion to USD 145 billion of 2026 capital expenditure. Gold Circuit Electronics’ record NT$59.73 billion of 2025 revenue, up 54.02%, came largely from ASIC server boards (Gold Circuit Electronics, January 2026).
How Much PCB Value Does an AI Server Carry?
An average GPU carried USD 560 of bare boards in 2025 and a custom ASIC USD 240, and a 72-GPU rack about USD 40,320 (DC Market Insights estimates).
| Year | PCB content per GPU (USD) | PCB content per custom ASIC (USD) | PCB content per 72-GPU rack (USD) |
|---|---|---|---|
| 2020 | 260 | 120 | 18,720 |
| 2025 | 560 | 240 | 40,320 |
| 2030 | 850 | 362 | 61,200 |
| 2035 | 920 | 410 | 66,240 |
Public price anchors back the climb: Victory Giant’s gross margin rose 12.5 percentage points in 2025 on its HDI mix, Elite Material set a laminate price rise of at least 10% for the second quarter of 2026, and the World Bank’s copper average moves from USD 9,947 per tonne in 2025 to USD 12,000 in 2026. Content per GPU rises 52% from 2025 to 2030, then only 8% to 2035 as layer counts level off.
Which Standards and Rules Apply to AI Server PCBs?
Five named rules shape the USD 4.77 billion of 2025 boards, from qualification classes to hazardous-substance limits.
- IPC-6012 (Qualification and Performance Specification for Rigid Printed Boards): AI baseboards and midplanes are commonly built to Class 3 high-reliability acceptance.
- IPC-4101 (Specification for Base Materials for Rigid and Multilayer Printed Boards): defines the laminate slash sheets that buyers name for M6 to M9 class materials.
- UL 796 (Printed Wiring Boards): the flammability and safety listing that server makers require for every board in the rack.
- EU RoHS Directive 2011/65/EU: limits lead and other hazardous substances in servers sold in the European Union, which sets the lead-free assembly profiles boards must survive.
- OCP Modular Hardware System (MGX): NVIDIA’s October 2025 contribution of Vera Rubin rack designs, including the PCB midplane, to the Open Compute Project.
How Is the High End AI Server PCB Market Segmented?
The market splits by board type, board application, accelerator platform, laminate loss grade and production base; high-layer boards of 18 to 30 layers lead 2025 with 38.0%, while ultra-high-layer and HDI boards lead by 2035 with 38.0% each.
By Board Type
Ultra-high-layer boards above 30 layers grow 20.20% a year, against 12.12% for 18 to 30 layer boards.
| Board type | 2025 (USD million) | Share 2025 | 2035 (USD million) | CAGR 2025-2035 |
|---|---|---|---|---|
| High-Layer Multilayer Boards (18 to 30 Layers) | USD 1.81 billion | 38.0% | USD 5.69 billion | 12.12% |
| Ultra-High-Layer Multilayer Boards (Above 30 Layers) | USD 1.43 billion | 30.0% | USD 9.01 billion | 20.20% |
| High-Order HDI Boards | USD 1.53 billion | 32.0% | USD 9.01 billion | 19.43% |
By Board Application
Baseboards and compute tray boards hold 42.0% of 2025 value; switch tray boards and midplanes gain 10 points of share by 2035.
| Board application | 2025 (USD million) | Share 2025 | 2035 (USD million) | CAGR 2025-2035 |
|---|---|---|---|---|
| Accelerator Module and OAM Boards | USD 1.43 billion | 30.0% | USD 6.40 billion | 16.16% |
| Baseboards and Compute Tray Boards | USD 2.00 billion | 42.0% | USD 8.54 billion | 15.60% |
| Scale-Up Switch Tray Boards and Midplanes | USD 620.26 million | 13.0% | USD 5.45 billion | 24.28% |
| Host Management and Power Boards | USD 715.68 million | 15.0% | USD 3.32 billion | 16.59% |
By Accelerator Platform
GPU-based AI servers hold 73.9% of 2025 value; custom ASIC servers grow faster at 19.43% a year.
| Accelerator platform | 2025 (USD million) | Share 2025 | 2035 (USD million) | CAGR 2025-2035 |
|---|---|---|---|---|
| GPU-Based AI Servers | USD 3.53 billion | 73.9% | USD 16.38 billion | 16.59% |
| Custom ASIC AI Servers | USD 1.24 billion | 26.1% | USD 7.34 billion | 19.43% |
By Laminate Loss Grade
Ultra low loss M7 class boards lead 2025 with 52.0%; extreme low loss M8 and M9 class boards reach 60.0% by 2035.
| Laminate loss grade | 2025 (USD million) | Share 2025 | 2035 (USD million) | CAGR 2025-2035 |
|---|---|---|---|---|
| Very Low Loss (M6 Class) | USD 1.34 billion | 28.0% | USD 1.42 billion | 0.63% |
| Ultra Low Loss (M7 Class) | USD 2.48 billion | 52.0% | USD 8.06 billion | 12.51% |
| Extreme Low Loss (M8 and M9 Class) | USD 954.24 million | 20.0% | USD 14.23 billion | 31.02% |
By Production Base
China makes 52.0% of 2025 board value; Thailand and Vietnam together rise from 16.0% to 30.0% by 2035.
| Production base | 2025 (USD million) | Share 2025 | 2035 (USD million) | CAGR 2025-2035 |
|---|---|---|---|---|
| China | USD 2.48 billion | 52.0% | USD 10.43 billion | 15.45% |
| Taiwan | USD 1.05 billion | 22.0% | USD 3.79 billion | 13.71% |
| Thailand | USD 572.54 million | 12.0% | USD 5.22 billion | 24.73% |
| Vietnam | USD 190.85 million | 4.0% | USD 1.90 billion | 25.82% |
| Japan South Korea and Other | USD 477.13 million | 10.0% | USD 2.37 billion | 17.39% |
DC Exclusive: AI PCB Capacity Map, Eight Named Expansions Behind USD 5.22 billion of Thailand Output by 2035
This DC Market Insights supplier and site map ties eight named capacity disclosures to the production-base model, which moves the 16.0% of 2025 board value made in Thailand and Vietnam to 30.0% by 2035.
| Site | Company | What was disclosed | Date | Model link |
|---|---|---|---|---|
| Thailand, all provinces | More than 180 PCB projects | Over THB 200 billion of BOI promotion applications | 2022 to June 2025 | Thailand USD 572.54 million in 2025 |
| Chachoengsao, Thailand | Cheng Yi Technology | 6.15 billion baht prepreg and laminate plant approved | 1 November 2024 | Local laminate for Thai lines |
| Thailand | Shennan Circuits | Thailand plant in production | Second half of 2025 | Thailand share rises |
| Thailand | Compeq, Multi-Fineline, Gold Circuit Electronics | THB 22.2 billion of expansions approved | 18 May 2026 | Thailand USD 5.22 billion by 2035 |
| Vietnam | Victory Giant Technology | About USD 470 million of 2025 revenue | April 2026 | Vietnam USD 190.85 million in 2025 |
| Nantong, China | Shennan Circuits | Phase 4 plant in production | Second half of 2025 | China USD 2.48 billion in 2025 |
| Huizhou, China | Victory Giant Technology | Hong Kong listing raising about HK$20.1 billion (95.85 million shares at HK$209.88) | 21 April 2026 | China USD 10.43 billion by 2035 |
| Kunshan, China | WUS Printed Circuit | H1 2026 revenue RMB 13.69 billion, up 61.17% | August 2026 | Switch tray boards |
Read across, the map puts Thailand’s share of board value at 12.0% in 2025 and 22.0% by 2035, while Taiwan-based makers keep their lead in ASIC boards through Thai plants rather than new Taiwan lines.
Which Region Buys the Most AI Server PCBs?
North America leads with USD 2.83 billion or 59.4% of 2025 value, counted where AI servers are deployed, and the Middle East and Africa grows fastest at 21.30% a year.
North America
North America spends USD 2.83 billion in 2025 (59.4%) and USD 13.04 billion by 2035, 16.49% a year; the United States alone takes USD 2.61 billion as hyperscalers such as Meta guide USD 130 billion to USD 145 billion of 2026 capital expenditure.
Asia Pacific
Asia Pacific spends USD 1.17 billion in 2025 (24.6%) and USD 6.07 billion by 2035, 17.86% a year; China (USD 529.60 million) and Japan (USD 166.99 million) lead, and India grows fastest at 25.10% as national AI clusters are built.
Europe
Europe spends USD 438.95 million in 2025 (9.2%) and USD 2.37 billion by 2035, 18.38% a year; the United Kingdom (USD 109.74 million) and Germany (USD 85.88 million) lead, with RoHS-compliant boards required for every rack.
Middle East and Africa
Middle East and Africa spends USD 233.79 million in 2025 (4.9%) and USD 1.61 billion by 2035, 21.30% a year; Saudi Arabia (USD 85.88 million) and the United Arab Emirates (USD 76.34 million) build national AI clusters.
Latin America
Latin America spends USD 90.65 million in 2025 (1.9%) and USD 616.59 million by 2035, 21.13% a year; Brazil and Mexico take most of it as cloud regions add GPU capacity.
Which Countries Deploy the Most AI Server PCB Value?
The United States leads with USD 2.61 billion in 2025, 54.8% of the market; India is the fastest large country at 25.10% a year.
| Rank | Country | Region | 2025 (USD million) | 2035 (USD million) | CAGR 2025-2035 |
|---|---|---|---|---|---|
| 1 | United States | North America | USD 2.61 billion | USD 11.95 billion | 16.41% |
| 2 | China | Asia Pacific | USD 529.60 million | USD 2.13 billion | 14.96% |
| 3 | Canada | North America | USD 219.47 million | USD 1.09 billion | 17.39% |
| 4 | Japan | Asia Pacific | USD 166.99 million | USD 806.31 million | 17.05% |
| 5 | South Korea | Asia Pacific | USD 109.74 million | USD 592.88 million | 18.38% |
| 6 | United Kingdom | Europe | USD 109.74 million | USD 545.45 million | 17.39% |
| 7 | Saudi Arabia | Middle East and Africa | USD 85.88 million | USD 616.59 million | 21.79% |
| 8 | Germany | Europe | USD 85.88 million | USD 450.59 million | 18.03% |
| 9 | India | Asia Pacific | USD 85.88 million | USD 806.31 million | 25.10% |
| 10 | United Arab Emirates | Middle East and Africa | USD 76.34 million | USD 545.45 million | 21.73% |
| 11 | Australia | Asia Pacific | USD 71.57 million | USD 379.44 million | 18.15% |
| 12 | France | Europe | USD 62.03 million | USD 355.73 million | 19.08% |
What Are the Forecast Scenarios for 2035?
The 2035 market runs from USD 18.02 billion to USD 28.93 billion around a base of USD 23.72 billion, depending on accelerator shipments and how fast midplanes and M9 laminate spread.
| Scenario | 2035 (USD million) | CAGR 2025-2035 | Assumption |
|---|---|---|---|
| Low | USD 18.02 billion | 14.21% | Accelerator units 15% below base; Kyber-type midplanes slip to 2029; content per GPU tops out near USD 800 |
| Base | USD 23.72 billion | 17.39% | 35.70 million accelerators in 2035; USD 920 per GPU and USD 410 per ASIC |
| High | USD 28.93 billion | 19.75% | Accelerator units 10% above base; midplanes in most racks from 2028; content per GPU above USD 1,000 |
Who Are the Leading High End AI Server PCB Makers?
Victory Giant Technology leads with about 18% of 2025 value, and the top five, Victory Giant Technology, Gold Circuit Electronics, WUS Printed Circuit, TTM Technologies and Shennan Circuits, hold about 55% (DC Market Insights estimate from each firm’s disclosed AI, server or data center revenue).
- Victory Giant Technology
- WUS Printed Circuit
- Gold Circuit Electronics
- TTM Technologies
- Shennan Circuits
- Tripod Technology
- Zhen Ding Technology
- ISU Petasys
- Unimicron Technology
- Kinwong Electronic
- Compeq Manufacturing
- Dynamic Holding
- Meiko Electronics
- Ibiden
- Multi-Fineline Electronix (MFS)
Victory Giant’s RMB 8.34 billion of AI and HPC revenue in 2025 converts to about USD 1.16 billion at the 2025 average rate, part of which is switch and optical module boards outside this scope. Gold Circuit Electronics posted NT$59.73 billion of 2025 revenue, up 54.02%, mostly from server boards; TTM Technologies drew about USD 697 million from data center computing; WUS Printed Circuit grew 2025 revenue about 42% to RMB 18.9 billion, much of it in switch boards; and Shennan Circuits’ PCB revenue rose 36.84% to RMB 14.36 billion, led by AI servers (Shennan Circuits 2025 annual report, March 2026).
What Are the Recent Developments in AI Server PCBs?
Six dated events from January to August 2026 show capacity and capital moving to AI boards.
- In January 2026, Gold Circuit Electronics reported record 2025 revenue of NT$59.73 billion, up 54.02% (Source: Gold Circuit Electronics).
- In February 2026, TTM Technologies reported USD 2.91 billion of 2025 sales and a fourth-quarter book-to-bill of 1.35, and guided 15% to 20% sales growth for 2026 (Source: TTM Technologies).
- In March 2026, Victory Giant Technology reported RMB 19.29 billion of 2025 revenue, up 79.77%, and Shennan Circuits RMB 23.65 billion, up 32.05% (Source: company annual reports).
- In April 2026, Victory Giant Technology listed H shares in Hong Kong at HK$209.88 each, raising about HK$20.1 billion (Source: Hong Kong Exchanges and Clearing filings).
- In May 2026, the Thailand BOI approved THB 22.2 billion of PCB expansions by Compeq, Multi-Fineline and Gold Circuit Electronics (Source: Thailand Board of Investment).
- In August 2026, WUS Printed Circuit reported first-half revenue of RMB 13.69 billion, up 61.17%, on switch, AI server and HPC boards (Source: WUS Printed Circuit).
Key Takeaways
Four numbers sum up the High End AI Server PCB Market for board buyers and suppliers.
- USD 7.65 billion in 2026, up 60.34%, because accelerator units rise 39% and content per GPU 14%.
- USD 40,320 of bare boards per 72-GPU rack in 2025, rising to USD 61,200 by 2030.
- USD 14.23 billion of M8 and M9 class boards by 2035, 60.0% of the market.
- 30.0% of 2035 board value made in Thailand and Vietnam, up from 16.0% in 2025.
Research Methodology: How Did DC Market Insights Size the AI Server PCB Market?
DC Market Insights sized the High End AI Server PCB Market bottom-up: 6.30 million GPUs times USD 560 of PCB content plus 5.18 million custom ASICs times USD 240 gives USD 4.77 billion in 2025, using accelerator units from its accelerator model and content per unit built from board counts per rack.
Three bound checks hold. Ceiling one: USD 4.77 billion is 2.8% of the USD 169.77 billion data center accelerator market of 2025 and 2.5% of NVIDIA’s USD 193.7 billion of data center revenue, in line with bare boards’ small share of system cost. Ceiling two: the five leading makers’ total 2025 revenue (Victory Giant, WUS, Shennan Circuits’ PCB unit, Gold Circuit Electronics and TTM Technologies) is about USD 12.1 billion, well above the market. Floor: Victory Giant’s AI and HPC revenue alone, about USD 1.16 billion, plus TTM Technologies’ USD 697 million of data center computing sales, is below the total. Read more in our research methodology, and see the AI Server Market, the AI Server Copper Foil Market and the Data Center Accelerator Market for the systems and materials around these boards.
Table of contents
- 01Introduction
- 1.1Report Description
- 1.2Key Market Statistics, 2025, 2026, 2030 and 2035
- 02Executive Summary
- 2.1Market Snapshot, 2025, 2026 and 2035
- 2.2Market Size Chart, 2020-2035
- 03Market Scope
- 3.1Included
- 3.2Excluded
- 3.3How the Segments Fit Together
- 04Why Market Estimates Differ
- 4.1Scope Table: In and Out of This Estimate
- 4.2Buyer Groups in Scope
- 05Market Drivers
- 5.1Rack-Scale Systems Turn One Server Board into Four
- 5.2Kyber Midplane Plan for the Second Half of 2027
- 5.3Victory Giant's AI Revenue Rises Nearly Elevenfold
- 06Market Trends
- 6.1Thailand Draws More Than THB 200 Billion of PCB Projects
- 6.2Vietnam Becomes Victory Giant's Second Base
- 6.3Extreme Low Loss Laminate Becomes the Default
- 07Market Challenges and Restraints
- 7.1Low-CTE Glass Cloth Stays Short Until FY2027
- 7.2Laminate Prices Up at Least 10% in the Second Quarter of 2026
- 08Market Opportunities
- 8.1USD 14.23 Billion of Extreme Low Loss Boards by 2035
- 8.2Custom ASIC Racks Grow 19.43% a Year
- 09Pricing Analysis
- 9.1PCB Content per GPU, per Custom ASIC and per 72-GPU Rack, 2020-2035
- 9.2Laminate, Copper and Margin Price Anchors
- 10Standards and Regulation
- 10.1IPC-6012
- 10.2IPC-4101
- 10.3UL 796
- 10.4EU RoHS Directive 2011/65/EU
- 10.5OCP Modular Hardware System (MGX)
- 11Market Segmentation
- 11.1By Board Type
- 11.2High-Layer Multilayer Boards (18 to 30 Layers)
- 11.3Ultra-High-Layer Multilayer Boards (Above 30 Layers)
- 11.4High-Order HDI Boards
- 11.5By Board Application
- 11.6Accelerator Module and OAM Boards
- 11.7Baseboards and Compute Tray Boards
- 11.8Scale-Up Switch Tray Boards and Midplanes
- 11.9Host Management and Power Boards
- 11.10By Accelerator Platform
- 11.11GPU-Based AI Servers
- 11.12Custom ASIC AI Servers
- 11.13By Laminate Loss Grade
- 11.14Very Low Loss (M6 Class)
- 11.15Ultra Low Loss (M7 Class)
- 11.16Extreme Low Loss (M8 and M9 Class)
- 11.17By Production Base
- 11.18China
- 11.19Taiwan
- 11.20Thailand
- 11.21Vietnam
- 11.22Japan South Korea and Other
- 12DC Exclusive: AI PCB Capacity Map
- 12.1Thailand BOI Promotion Applications
- 12.2Cheng Yi Technology Laminate Plant
- 12.3Shennan Circuits Thailand and Nantong Plants
- 12.4Compeq, Multi-Fineline and Gold Circuit Electronics Expansions
- 12.5Victory Giant Vietnam and Hong Kong Listing
- 12.6WUS Printed Circuit Kunshan
- 13Regional Insights
- 13.1North America
- 13.2Asia Pacific
- 13.3Europe
- 13.4Middle East and Africa
- 13.5Latin America
- 14Country Analysis
- 14.1United States
- 14.2China
- 14.3Canada
- 14.4Japan
- 14.5South Korea
- 14.6United Kingdom
- 14.7Saudi Arabia
- 14.8Germany
- 14.9India
- 14.10United Arab Emirates
- 14.11Australia
- 14.12France
- 15Forecast Scenarios, 2035
- 15.1Low Scenario
- 15.2Base Scenario
- 15.3High Scenario
- 16Competitive Insights
- 16.1Victory Giant Technology
- 16.2WUS Printed Circuit
- 16.3Gold Circuit Electronics
- 16.4TTM Technologies
- 16.5Shennan Circuits
- 16.6Tripod Technology
- 16.7Zhen Ding Technology
- 16.8ISU Petasys
- 16.9Unimicron Technology
- 16.10Kinwong Electronic
- 16.11Compeq Manufacturing
- 16.12Dynamic Holding
- 16.13Meiko Electronics
- 16.14Ibiden
- 16.15Multi-Fineline Electronix (MFS)
- 16.16Market Concentration, Top Five Share
- 17Recent Developments
- 17.1January 2026 to August 2026 Events
- 18Key Takeaways
- 18.1Four Numbers for Buyers and Suppliers
- 19Research Methodology
- 19.1Bottom-Up Model
- 19.2Bound Checks
- 19.3Sources
- Fig. 1High End AI Server PCB Market Size, 2020-2035 (USD billion)
- Table 1Market Snapshot, 2025, 2026 and 2035
- Table 2Scope Table, In and Out of This Estimate
- Table 3PCB Content per GPU, per Custom ASIC and per 72-GPU Rack, 2020-2035
- Table 4Market by Board Type, 2025 and 2035
- Table 5Market by Board Application, 2025 and 2035
- Table 6Market by Accelerator Platform, 2025 and 2035
- Table 7Market by Laminate Loss Grade, 2025 and 2035
- Table 8Market by Production Base, 2025 and 2035
- Table 9AI PCB Capacity Map, Eight Named Expansions
- Table 10Top 12 Countries, 2025 and 2035
- Table 11Forecast Scenarios, 2035
About this report
Written by Amit Jain and reviewed by Deepti Agrawal, Senior Editor, Research. Figures are built top-down and bottom-up and reconciled before publication, with 2025 as the base year.
Read our methodologyHow we built this
- Historical period2020-2024
- Base year2025
- Forecast period2026-2035
- Sizing approachTop-down + bottom-up
Need more than the report?
Advisory on this market
Due diligence, site selection and market entry work, by the analysts who wrote this report.
See consulting servicesFrequently asked questions
USD 7.65 billion in 2026, up 60.34% from USD 4.77 billion in 2025, according to DC Market Insights estimates. The market is projected to reach USD 23.72 billion by 2035, a CAGR of 17.39% from 2025.
17.39% a year from 2025 to 2035, after 97.44% a year from 2020 to 2025, because accelerator shipments flatten after 2028 while PCB content per GPU rises from USD 560 to USD 920.
About USD 40,320 of bare boards per 72-GPU rack in 2025, or USD 560 per GPU, rising to USD 61,200 by 2030 as switch trays and midplanes are added (DC Market Insights estimates).
Because 112G and 224G links and dense accelerator modules need short, low-loss signal paths: boards above 30 layers grow 20.20% a year and high-order HDI boards 19.43% a year to 2035.
A large board that replaces cable cartridges between compute and switch trays. NVIDIA plans one for its Kyber rack in the second half of 2027; switch tray boards and midplanes grow 24.28% a year.
Extreme low loss M8 and M9 class laminate, from USD 954.24 million in 2025 to USD 14.23 billion by 2035, 31.02% a year, reaching 60% of board value.
Victory Giant Technology leads with about 18% of 2025 value; with Gold Circuit Electronics, WUS Printed Circuit, TTM Technologies and Shennan Circuits the top five hold about 55% (DC Market Insights estimate).
China made 52.0% of 2025 board value and Taiwan 22.0%; Thailand and Vietnam rise from 16.0% to 30.0% by 2035 as more than 180 PCB projects worth over THB 200 billion seek Thai promotion.
North America, with USD 2.83 billion or 59.4% of 2025 value by deployment. The Middle East and Africa grows fastest at 21.30% a year, and India is the fastest large country at 25.10%.
USD 7.65 billion in 2026 is the DC Market Insights value of bare boards in AI servers and scale-up switch trays only. Estimates that add IC substrates, scale-out switch boards, general servers or assembly come out larger.
Licences, delivery and payment
Which licence should I choose?
Single User is a view-only PDF for one person. Multi User adds a printable PDF and the Excel data for unlimited users at one location. Enterprise covers your whole company and includes 100 free analyst hours.
How and when will I receive the report?
By email, within 24–48 business hours of payment, in the formats of your licence.
How can I pay?
Securely through PayPal: with a PayPal account, a debit or credit card, or PayPal Pay Later where available. Prices are in US dollars.
Can I see a sample first?
Yes. Request a free sample and we will email it to you.
Can the report be tailored to my needs?
Yes. We can add countries, segments or data cuts. Talk to an analyst about the scope you need.
Can I get an invoice or pay against a purchase order?
Write to sales@dcmarketinsights.com and our team will help.