
South Korea Data Center Storage Market Size, Share & Forecast to 2035
Market at a glance
The South Korea Data Center Storage market was worth USD 575.5 million in 2025 and is forecast to reach USD 1,690.0 million by 2035, growing at a 11.34% CAGR.
 By Amit Jain, Senior Consultant, ICT & Emerging Technologies
 Reviewed by Deepti Agrawal
Last updated 2 Nov 2026
Base year 2025 PDF + Excel
Key findings
The NIRS Daejeon fire turned backup into a legal-grade requirement
Server SSD demand from Korean suppliers points to an all-flash primary tier
Grid-impact assessments slow halls in the capital region
AI cluster storage in Jeollanam-do, Ulsan and Gumi
What is inside the report
- 01Introduction
- 02Executive Summary
- 03Market Scope and Estimate Comparison
- 04Market Drivers
- 05Market Trends
- 06Market Challenges
- 07Market Opportunities
- 08Pricing Analysis
- 09Standards and Regulation
- 10Market Segmentation
- 17chapters
- 2020-2024Historical period
- 2026-2035Forecast period
- —Companies profiled
Segmentation
Recent developments
the Ministry of the Interior and Safety set storage-based disaster recovery for grade A1 to A3 government systems by 2027 (Source: Ministry of the Interior and Safety).
Samsung SDS said its 60 MW Gumi AI data center breaks ground in November (Source: Samsung SDS).
NAVER, NVIDIA and Brookfield agreed to expand GAK Sejong from 55 MW to 200 MW (Source: NAVER).
the National Assembly passed the AI Data Center Special Act (Source: Korea Policy Briefing).
MSIT secured 13,000 GPUs with a KRW 1.46 trillion budget (Source: MSIT).
Samsung, SK and OpenAI signed Stargate memoranda, including AI data center sites outside the Seoul Metropolitan Area (Source: OpenAI).
Full analysis
The South Korea Data Center Storage Market is valued at USD 694.58 million in 2026 and is projected to reach USD 1.69 billion by 2035, up from USD 575.51 million in 2025, a CAGR of 11.34% from 2025 to 2035 (DC Market Insights estimate). South Korea Data Center Storage covers the arrays, file and object systems, tape libraries, storage software and storage support bought for data center halls located in South Korea. The fire at the National Information Resources Service (NIRS) Daejeon center on 26 September 2025 changed how Korean buyers think about storage: 709 government systems went down, and the G-Drive document store was judged unrecoverable because it had no backup (Source: Ministry of the Interior and Safety). The 2025 build receipt is 1,266-1,477 MW of installed IT capacity (average 1,371 MW) × USD 0.36 million of storage spend per MW-year = USD 494.55 million, plus 74 MW of new AI capacity × USD 1.10 million = USD 80.96 million. Object storage grows fastest at 17.99% a year, and the Honam Region is the fastest region at 24.27% as Jeollanam-do campuses near Haenam take AI halls that the capital region cannot connect to the grid.
How Much Will Korean Data Centers Spend on Storage in 2026?
Korean data centers will spend USD 694.58 million on storage systems, storage software and storage services in 2026, 20.69% more than the USD 575.51 million of 2025, DC Market Insights estimates.
- Market size 2025: USD 575.51 million
- Market size 2026: USD 694.58 million
- Market size 2030: USD 1.22 billion
- Market size 2035: USD 1.69 billion
- CAGR 2025-2035: 11.34% (low case 8.05%, high case 13.05%)
- Largest storage type: All-Flash Arrays, 50% of 2025 value
- Fastest architecture: Object Storage, 17.99% CAGR
- Leading region: Capital Region, 70% of 2025 value; fastest region: Honam Region, 24.27% CAGR
- Largest province: Gyeonggi-do, USD 201.43 million in 2025
- Market leaders: Dell Technologies, NetApp and Hewlett Packard Enterprise (HPE), about 44% of external array spend together (DC Market Insights estimate)
Key Takeaways: Four Numbers Korean Storage Buyers Should Watch
- All-flash arrays take 50% of 2025 spend and 66% by 2035 because AI clusters built for the government GPU programme need flash throughput to keep graphics processing units (GPUs) busy.
- Government and Public Sector storage grows 12.24% a year because the NIRS fire forced storage-based disaster recovery by 2027 for systems in the three highest criticality grades (A1, A2 and A3).
- The Capital Region falls from 70% to 52% of value by 2035 because grid-impact rules push new halls to Sejong, Ulsan and Jeollanam-do.
- Enterprises and Financial Institutions grow only 6.75% a year because enterprises move workloads into cloud and colocation halls.
Executive Summary: South Korea Data Center Storage Market Size, 2020-2035
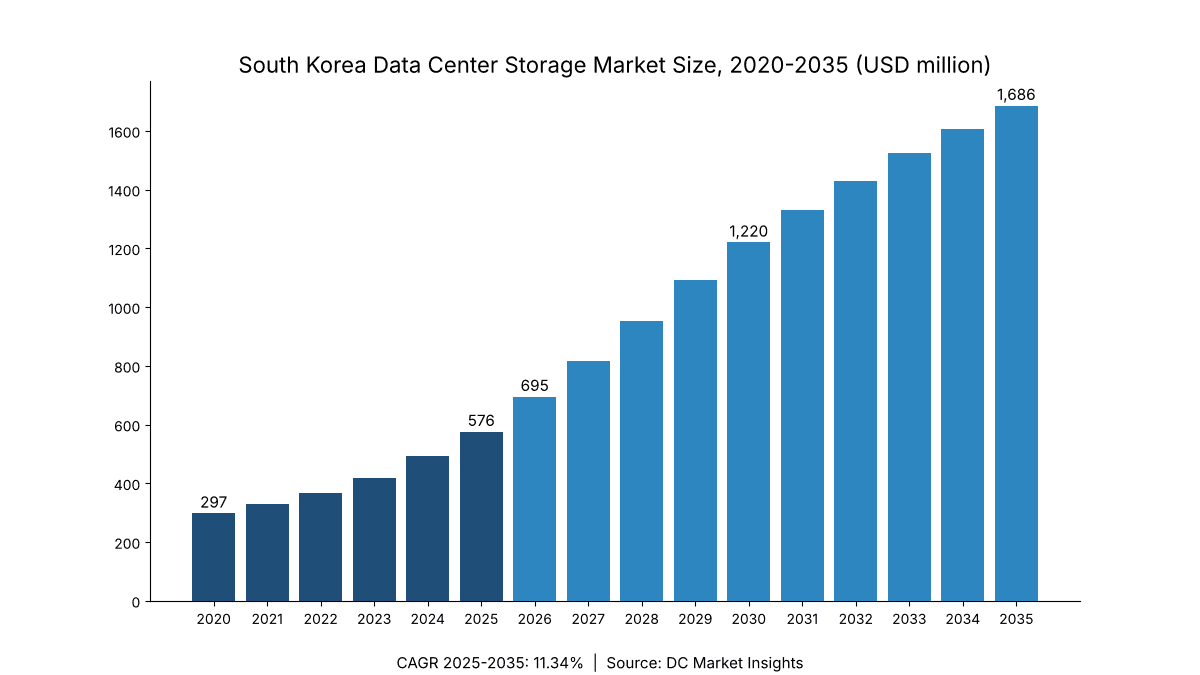
The South Korea Data Center Storage Market size was valued at USD 297.31 million in 2020, reached USD 575.51 million in 2025, and is anticipated to reach USD 1.69 billion by 2035, at a CAGR of 11.34% during the forecast period. Growth from 2020 to 2025 ran at 14.12% a year because installed IT capacity doubled from about 740 MW to 1,477 MW while the first AI halls started buying flash in bulk.
| Attribute | Detail |
|---|---|
| Historical period | 2020-2024 |
| Base year | 2025 |
| Forecast period | 2026-2035 |
| Market size 2025 | USD 575.51 million |
| Market size 2026 | USD 694.58 million |
| CAGR 2025-2035 | 11.34% |
| Market size 2035 | USD 1.69 billion |
DC Market Insights values installed-base storage refresh and expansion at USD 494.55 million in 2025 and AI cluster storage at USD 80.96 million; by 2035 the two lines reach USD 1.39 billion and USD 293.36 million. The per-megawatt storage rate falls from USD 0.42 million in 2020 to USD 0.27 million in 2035 because each new rack carries more compute per terabyte stored and flash prices per terabyte keep falling.
What Counts as Data Center Storage in Korean Halls?
The South Korea Data Center Storage Market covers USD 575.51 million of storage equipment, software and support bought in 2025 for halls run by cloud providers, telecom operators, colocation firms, enterprises and government centers.
Included: all-flash and hybrid arrays, HDD-based systems, tape and archive libraries, Storage Area Network (SAN) and Network-Attached Storage (NAS) systems, scale-out file and object platforms, hyperconverged storage nodes, storage software (replication, snapshots, data protection) and storage support contracts.
Excluded: servers and GPUs, network switches, power and cooling (see the South Korea Data Center Market), public cloud storage subscriptions, and loose solid-state drives (SSDs) or memory chips sold by Samsung Electronics and SK hynix (an SK Group company) to server makers, which are component sales rather than data center storage systems.
How the segments fit together: each of the four segment dimensions and the five regions adds up to the same total in every year; the South Korea Data Center Market report covers the halls themselves, while the storage market counts only the arrays and software inside them; the Data Center Storage Market gives the worldwide view.
Why Do South Korea Data Center Storage Market Estimates Differ?
Published figures for South Korean data center storage run from under USD 0.5 billion to more than USD 1.5 billion for 2025 because they draw the boundary in different places; DC Market Insights puts 2026 at USD 694.58 million.
Broader definitions add the memory and SSD output of Samsung Electronics and SK hynix, enterprise storage outside data center halls, and cloud storage subscription revenue. The earlier DC Market Insights edition of the South Korea Data Center Storage Market used that wider basis and came out about 2.6 times larger; this edition replaces it with a bottom-up figure of USD 575.51 million that counts only systems installed in Korean halls. Small and mid-sized enterprises (SMEs) that rent racks in colocation halls and buy their own arrays are in scope.
| Element | In this report | Why |
|---|---|---|
| Storage arrays, file and object systems | Yes (USD 379.84 million hardware 2025) | Core purchase |
| Storage software and support | Yes (USD 195.67 million in 2025) | Bought with the arrays |
| SSD and memory chip exports | No | Component sales, mostly shipped abroad |
| Cloud storage subscriptions | No | Service revenue, not equipment |
| Servers, network, power, cooling | No | Covered by sibling reports |
Market Drivers: What Drives Data Center Storage Demand in South Korea?
Three dated events add USD 119.07 million of storage spend between 2025 and 2026, DC Market Insights estimates: the NIRS disaster-recovery rebuild, the government GPU programme and the NAVER Corporation (NAVER), NVIDIA Corporation (NVIDIA) and Brookfield campus in Sejong.
The NIRS Daejeon fire turned backup into a legal-grade requirement
The 26 September 2025 battery fire at NIRS Daejeon burned 96 systems completely and took 709 systems offline; all 709 were restored only on 30 December 2025, about 95 days later (Source: Ministry of the Interior and Safety). The one-year NIRS recovery briefing of 2 October 2026 sets storage-based disaster recovery for grade A1 to A3 systems by 2027, a one-hour recovery target for A1 systems from a second center, off-site backup through the Gongju center and storage backup systems for all three government centers by the end of 2027. DC Market Insights estimates this programme lifts Government and Public Sector storage, 12% of 2025 value, by about a quarter across 2026 and 2027.
13,000 government GPUs need flash tiers beside them
The Ministry of Science and ICT (MSIT) secured 13,000 GPUs with a KRW 1.46 trillion supplementary budget, with a first batch of 2,296 H200 and 2,040 B200 units hosted in NAVER Cloud, Kakao and NHN Cloud data centers, according to the Ministry of Science and ICT GPU release of 22 December 2025. MSIT targets 37,000 government GPUs by the end of 2026 and 260,000 GPUs nationally by 2030, about 500 MW of power demand (Source: MSIT 2026 work-plan briefing). At about USD 1.08 million of storage per AI megawatt, the 2026 AI line reaches USD 129.36 million.
NAVER’s Sejong AI factory grows from 55 MW to 200 MW
NAVER, NVIDIA and Brookfield agreed in July 2026 to expand the AI factory at NAVER’s GAK Sejong campus (GAK is NAVER’s name for its hyperscale data center sites) from 55 MW to 200 MW in a USD 10 billion project, according to the NAVER announcement. That single campus adds about 145 MW of AI capacity, worth roughly USD 150 million of storage at today’s per-megawatt rate (DC Market Insights estimate), and is the main reason Sejong grows 15.16% a year to USD 113.27 million by 2035.
Market Trends: How Is Korean Data Center Storage Changing?
All-flash arrays rise from 50% to 66% of Korean data center storage value by 2035 and object storage from 14% to 25%, DC Market Insights estimates, as AI and recovery workloads reshape storage tiers.
Server SSD demand from Korean suppliers points to an all-flash primary tier
Samsung Electronics said in its third-quarter 2026 results that it was meeting growing demand for server SSDs and saw surging quad-level cell (QLC) SSD demand, and SK hynix reported higher sales of 321-layer triple-level cell (TLC) enterprise SSDs (eSSDs) for data centers in the same quarter (Source: company results releases). All-flash arrays grow 14.48% a year from USD 287.75 million in 2025, while HDD-based systems grow 7.44%.
Object storage becomes the capacity and recovery tier
Object Storage grows 17.99% a year from USD 80.57 million in 2025 to USD 421.38 million in 2035 because model checkpoints, immutable backup copies and the off-site copies that NIRS now requires sit on S3-compatible capacity tiers.
Market Challenges: What Slows Storage Spending in Korean Data Centers?
Two limits keep the 2035 base case of USD 1.69 billion about USD 277 million below the high case of USD 1.96 billion, DC Market Insights estimates: grid access for new halls and falling cost per terabyte.
Grid-impact assessments slow halls in the capital region
The Distributed Energy Activation Special Act took effect on 14 June 2024 and requires grid-impact assessments for large loads, steering new data centers away from the Seoul metropolitan area (Source: Ministry of Trade, Industry and Energy). New IT capacity in the model rises from 230 MW in 2025 to 300 MW in 2026; a one-year delay to 100 MW of AI halls would push about USD 100 million of storage spend into later years.
Falling flash prices per terabyte cap spend per megawatt
The installed-base storage rate falls about 3% a year, from USD 0.36 million per MW-year in 2025 to USD 0.27 million in 2035, so spend grows 11.34% a year while installed capacity grows about 13.9% a year.
Market Opportunities: Which Korean Storage Projects Are Still Open to Suppliers?
Two pools worth about USD 640.50 million by 2035 are open to suppliers, DC Market Insights estimates.
AI cluster storage in Jeollanam-do, Ulsan and Gumi
Jeollanam-do grows 27.31% a year to USD 141.58 million by 2035: the Haenam complex plans 25 buildings of 40 MW each by 2037 (Source: Jeollanam-do provincial plan via the Korea Policy Briefing), and SK Telecom signed a memorandum with OpenAI for an AI data center in the southwest in October 2025 (Source: SK Group). Samsung SDS breaks ground on a 60 MW AI data center in Gumi in November 2026, according to its Samsung SDS third-quarter 2026 results.
Sovereign and recovery storage for regulated buyers
Government and Public Sector storage reaches USD 219.12 million by 2035. MSIT and the National Intelligence Service (NIS) will replace the dual public-cloud security certification with one NIS-led scheme from 2027 (Source: MSIT, 20 April 2026), which favours suppliers that can certify replicated storage inside Korea.
What Do Korean Operators Pay for Storage per Megawatt?
Korean data centers spend about USD 0.36 million on storage per installed megawatt a year in 2025, plus about USD 1.10 million one-off per megawatt of new AI capacity, DC Market Insights estimates.
| Year | Storage spend per installed MW-year (USD million) | Storage per new AI MW (USD million) | Installed IT capacity (MW) |
|---|---|---|---|
| 2020 | 0.42 | 1.22 | 740 |
| 2025 | 0.36 | 1.10 | 1,477 |
| 2030 | 0.31 | 0.99 | 3,278 |
| 2035 | 0.27 | 0.90 | 5,452 |
Public price anchors are thin: the Public Procurement Service does not publish storage-array unit prices, so the rates are calibrated on the installed base and on AI cluster designs where storage is about 5% to 8% of cluster cost. The rate per AI megawatt falls 2% a year as flash density rises.
Which Korean Laws and Recovery Rules Govern Data Center Storage?
Five rules decide where Korean storage is installed and how it is replicated, touching an estimated USD 253.22 million of regulated-buyer spend in 2025.
- NIRS disaster-recovery plan (October 2026): storage-based recovery for A1 to A3 systems by 2027, 13 Daejeon systems active-active by March 2027 (Source: Ministry of the Interior and Safety).
- Distributed Energy Activation Special Act (June 2024): grid-impact assessment for large new loads (Source: Ministry of Trade, Industry and Energy).
- AI Data Center Special Act (passed May 2026): a single MSIT permit window and exemption from grid-impact review for AI data centers below a set size outside the capital region (Source: Korea Policy Briefing).
- Cloud Security Assurance Program (CSAP): moves to a single NIS-led certification in 2027 (Source: MSIT).
- Personal Information Protection Act (PIPA): the Personal Information Protection Commission fined Temu KRW 1.369 billion in May 2025, including for overseas-transfer breaches (Source: PIPC).
Which Array Type Carries the Value in South Korea Data Center Storage?
All-flash arrays lead with USD 287.75 million, 50% of 2025 value, and Object Storage is the fastest architecture at 17.99% a year, DC Market Insights estimates.
By Storage Type
All-Flash Arrays rise from 50% to 66% of value because AI clusters and recovery copies need flash.
| Segment | 2025 (USD million) | Share 2025 | 2035 (USD million) | CAGR 2025-2035 |
|---|---|---|---|---|
| All-Flash Arrays | 287.75 | 50% | 1,112.44 | 14.48% |
| Hybrid Flash Arrays | 126.61 | 22% | 235.97 | 6.42% |
| HDD-Based Systems | 115.10 | 20% | 235.97 | 7.44% |
| Tape and Archive Libraries | 46.04 | 8% | 101.13 | 8.19% |
By Architecture
Storage Area Network (SAN) keeps the largest 2025 share at 38% but grows only 8.0% a year.
| Segment | 2025 (USD million) | Share 2025 | 2035 (USD million) | CAGR 2025-2035 |
|---|---|---|---|---|
| Storage Area Network (SAN) | 218.69 | 38% | 471.94 | 8.0% |
| Network-Attached and Scale-Out File | 172.65 | 30% | 522.51 | 11.71% |
| Object Storage | 80.57 | 14% | 421.38 | 17.99% |
| Direct-Attached and Hyperconverged | 103.59 | 18% | 269.68 | 10.04% |
By Component
Storage Software grows fastest at 13.39% a year because replication and snapshot licences rise with recovery rules.
| Segment | 2025 (USD million) | Share 2025 | 2035 (USD million) | CAGR 2025-2035 |
|---|---|---|---|---|
| Hardware | 379.84 | 66% | 1,011.31 | 10.29% |
| Storage Software | 115.10 | 20% | 404.52 | 13.39% |
| Support and Managed Services | 80.57 | 14% | 269.68 | 12.84% |
By End User
Hyperscale and Cloud Providers grow 14.11% a year to 46% of value by 2035.
| Segment | 2025 (USD million) | Share 2025 | 2035 (USD million) | CAGR 2025-2035 |
|---|---|---|---|---|
| Hyperscale and Cloud Providers | 207.18 | 36% | 775.33 | 14.11% |
| Telecom and Colocation Operators | 115.10 | 20% | 337.10 | 11.34% |
| Enterprises and Financial Institutions | 184.16 | 32% | 353.96 | 6.75% |
| Government and Public Sector | 69.06 | 12% | 219.12 | 12.24% |
DC Exclusive: The NIRS Fire-to-Recovery Storage Ledger
The NIRS Fire-to-Recovery Storage Ledger is a DC Market Insights model built on 9 inputs that tracks how the September 2025 fire turns into storage purchases, worth about USD 38 million across 2026 and 2027.
| Date | Event | Storage consequence (DC Market Insights estimate) |
|---|---|---|
| 26 Sep 2025 | Battery fire at NIRS Daejeon; 709 systems offline | Storage hardware damaged by heat and dust |
| 29 Sep 2025 | 96 burned systems to move to the Daegu center | Replacement arrays in Daegu, about USD 6 million |
| 1 Oct 2025 | G-Drive judged unrecoverable for lack of backup | Backup copy policy for document stores |
| 18 Nov 2025 | 696 of 709 systems restored (98.2%) | Storage vendors repair dust-damaged arrays |
| 30 Dec 2025 | All 709 systems restored | Recovery phase closes after 95 days |
| 2 Oct 2026 | Storage-based DR for A1 to A3 by 2027; 1-hour A1 recovery | Replicated arrays at a second center, about USD 20 million |
| Mar 2027 | 13 Daejeon systems active-active | Synchronous replication licences |
| End 2027 | Storage backup systems in all three centers | Backup and object tiers, about USD 12 million |
The ledger assumes 76 grade-1 systems need active-active storage at about USD 0.25 million each and that roughly 15,000 regraded public systems shift part of their backup to the Gongju center (Source: Ministry of the Interior and Safety release of 29 September 2025 and the one-year briefing).
Regional Insights: Which Korean Region Leads Data Center Storage, and Why Is Spend Leaving the Capital Region?
The Capital Region leads with USD 402.86 million, 70% of 2025 value, while the Honam Region grows fastest at 24.27% a year, DC Market Insights estimates.
| Region | 2025 (USD million) | Share 2025 | 2035 (USD million) | CAGR 2025-2035 |
|---|---|---|---|---|
| Capital Region | 402.86 | 70% | 876.47 | 8.08% |
| Chungcheong Region | 69.06 | 12% | 269.68 | 14.59% |
| Gyeongsang Region | 57.55 | 10% | 235.97 | 15.15% |
| Honam Region | 23.02 | 4% | 202.26 | 24.27% |
| Gangwon and Jeju | 23.02 | 4% | 101.13 | 15.95% |
Capital Region
Gyeonggi-do and Seoul hold the cloud regions and colocation campuses, but the region’s share falls to 52% by 2035 as grid-impact assessments slow new halls. Storage spend here rises from USD 402.86 million in 2025 to USD 876.47 million in 2035.
Chungcheong Region
Sejong and Daejeon carry the NAVER GAK campus and the NIRS government center, so AI and recovery storage lift the region to 16% of value. Storage spend here rises from USD 69.06 million in 2025 to USD 269.68 million in 2035.
Gyeongsang Region
The SK Group and Amazon Web Services (AWS) AI data center in Ulsan starts operating from 2027 under a 15-year partnership, and Samsung SDS builds 60 MW in Gumi. Storage spend here rises from USD 57.55 million in 2025 to USD 235.97 million in 2035.
Honam Region
Jeollanam-do’s Haenam plan of 25 buildings of 40 MW each by 2037 makes Honam the fastest storage region. Storage spend here rises from USD 23.02 million in 2025 to USD 202.26 million in 2035.
Gangwon and Jeju
Chuncheon campuses and Jeju sites add cooler-climate capacity and grow about 16% a year. Storage spend here rises from USD 23.02 million in 2025 to USD 101.13 million in 2035.
Which Korean Provinces Buy the Most Data Center Storage?
Gyeonggi-do is the largest location at USD 201.43 million in 2025, and Jeollanam-do is the fastest at 27.31% a year, DC Market Insights estimates.
| Rank | Province or city | Region | 2025 (USD million) | 2035 (USD million) | CAGR 2025-2035 |
|---|---|---|---|---|---|
| 1 | Gyeonggi-do | Capital Region | 201.43 | 455.76 | 8.51% |
| 2 | Seoul | Capital Region | 145.03 | 262.94 | 6.13% |
| 3 | Incheon | Capital Region | 56.40 | 157.76 | 10.83% |
| 4 | Sejong | Chungcheong Region | 27.62 | 113.27 | 15.16% |
| 5 | Busan and Gyeongnam | Gyeongsang Region | 25.90 | 89.67 | 13.22% |
| 6 | Daejeon | Chungcheong Region | 24.17 | 67.42 | 10.8% |
| 7 | Gangwon and Jeju | Gangwon and Jeju | 23.02 | 101.13 | 15.95% |
| 8 | Chungcheong Provinces | Chungcheong Region | 17.27 | 88.99 | 17.82% |
| 9 | Daegu and Gyeongbuk | Gyeongsang Region | 17.26 | 66.07 | 14.37% |
| 10 | Ulsan | Gyeongsang Region | 14.39 | 80.23 | 18.75% |
| 11 | Jeollanam-do | Honam Region | 12.66 | 141.58 | 27.31% |
| 12 | Gwangju and Jeonbuk | Honam Region | 10.36 | 60.68 | 19.34% |
Forecast Scenarios: Where Could Korean Data Center Storage Land in 2035?
The South Korea Data Center Storage Market reaches between USD 1.25 billion and USD 1.96 billion by 2035, with a base case of USD 1.69 billion, DC Market Insights estimates.
| Scenario | 2035 value | CAGR 2025-2035 | What has to happen |
|---|---|---|---|
| Low | USD 1.25 billion | 8.05% | Grid queues delay AI halls by two years; flash prices fall faster |
| Base | USD 1.69 billion | 11.34% | About 5,450 MW installed by 2035; AI share of new capacity 64% |
| High | USD 1.96 billion | 13.05% | 260,000 GPUs by 2030 on schedule; NIRS-style recovery rules spread to finance |
Key Players and Market Share: Which Vendors Hold Korean Data Center Storage?
Dell Technologies, NetApp and Hewlett Packard Enterprise hold about 44% of external array spend in South Korea together, DC Market Insights estimates on the basis of installed systems in Korean cloud, telecom and government halls.
- Dell Technologies
- NetApp
- Hewlett Packard Enterprise (HPE)
- Pure Storage
- IBM
- Hitachi Vantara
- Huawei Technologies
- Lenovo
- Nutanix
- Samsung SDS
- LG CNS
- SK Telecom
- KT Cloud
- NAVER Cloud
- Commvault
Samsung SDS reported cloud revenue of KRW 796.1 billion in the third quarter of 2026, up 18%, and is preferred bidder on a data center project of more than 200 MW (Source: Samsung SDS). KT runs its Secure Public Cloud on Microsoft Cloud for Sovereignty under a five-year partnership signed in September 2024 (Source: Microsoft). Korean memory makers Samsung Electronics and SK hynix supply much of the flash inside the arrays but sell components, not storage systems.
Recent Developments: What Changed for Korean Data Center Storage Since the NIRS Fire?
- In October 2026, the Ministry of the Interior and Safety set storage-based disaster recovery for grade A1 to A3 government systems by 2027 (Source: Ministry of the Interior and Safety).
- In October 2026, Samsung SDS said its 60 MW Gumi AI data center breaks ground in November (Source: Samsung SDS).
- In July 2026, NAVER, NVIDIA and Brookfield agreed to expand GAK Sejong from 55 MW to 200 MW (Source: NAVER).
- In May 2026, the National Assembly passed the AI Data Center Special Act (Source: Korea Policy Briefing).
- In December 2025, MSIT secured 13,000 GPUs with a KRW 1.46 trillion budget (Source: MSIT).
- In October 2025, Samsung, SK and OpenAI signed Stargate memoranda, including AI data center sites outside the Seoul Metropolitan Area (Source: OpenAI).
Research Methodology: How the Model Counts Korean Storage Megawatt by Megawatt
The model multiplies 16 years of installed IT capacity (about 740 MW in 2020, 1,477 MW in 2025 and 5,452 MW in 2035, 1.5% retired each year) by a storage rate per MW-year, and adds new AI megawatts (32% of 230 MW in 2025, 64% of 510 MW in 2035) times a storage rate per AI megawatt. The 2025 receipt is USD 494.55 million + USD 80.96 million = USD 575.51 million. Bound checks: (1) consistency — 2025 storage spend is 1.41 times the USD 407.96 million thermal layer in the South Korea Data Center Thermal Management Market, which uses the same capacity inputs; (2) ceiling — the 2025 total equals about 25% of Samsung SDS’s annualised cloud revenue (KRW 796.1 billion a quarter, about USD 2.3 billion a year), and storage is only one of many cloud cost lines; (3) floor — 13,000 government GPUs at about USD 75,000 per GPU cluster cost × 6% storage = USD 58.50 million, below the 2026 AI line of USD 129.36 million. Regional splits use the South Korea AI Data Center Market capacity pipeline. See our research methodology.
Table of contents
- 01Introduction
- 1.1Market Definition and Scope
- 1.2Research Methodology
- 02Executive Summary
- 2.1Market Snapshot, 2025, 2026 and 2035
- 2.2Key Market Statistics
- 2.3Key Takeaways
- 03Market Scope and Estimate Comparison
- 3.1Included and Excluded Spend
- 3.2Why Estimates Differ
- 04Market Drivers
- 4.1NIRS Daejeon Fire and Disaster Recovery
- 4.2Government GPU Programme
- 4.3GAK Sejong Expansion
- 05Market Trends
- 5.1All-Flash Primary Tier
- 5.2Object Storage as Capacity and Recovery Tier
- 06Market Challenges
- 6.1Grid-Impact Assessments
- 6.2Falling Cost per Terabyte
- 07Market Opportunities
- 7.1AI Cluster Storage in Jeollanam-do, Ulsan and Gumi
- 7.2Sovereign and Recovery Storage
- 08Pricing Analysis
- 8.1Storage Spend per MW, 2020-2035
- 09Standards and Regulation
- 9.1NIRS Disaster-Recovery Plan
- 9.2Distributed Energy Activation Special Act
- 9.3AI Data Center Special Act
- 9.4Cloud Security Assurance Program
- 9.5Personal Information Protection Act
- 10Market Segmentation
- 10.1By Storage Type
- 10.2All-Flash Arrays
- 10.3Hybrid Flash Arrays
- 10.4HDD-Based Systems
- 10.5Tape and Archive Libraries
- 10.6By Architecture
- 10.7Storage Area Network (SAN)
- 10.8Network-Attached and Scale-Out File
- 10.9Object Storage
- 10.10Direct-Attached and Hyperconverged
- 10.11By Component
- 10.12Hardware
- 10.13Storage Software
- 10.14Support and Managed Services
- 10.15By End User
- 10.16Hyperscale and Cloud Providers
- 10.17Telecom and Colocation Operators
- 10.18Enterprises and Financial Institutions
- 10.19Government and Public Sector
- 11DC Exclusive: NIRS Fire-to-Recovery Storage Ledger
- 11.1Recovery Timeline, September 2025 to End 2027
- 11.2Storage Consequences by Event
- 12Regional Insights
- 12.1Capital Region
- 12.2Chungcheong Region
- 12.3Gyeongsang Region
- 12.4Honam Region
- 12.5Gangwon and Jeju
- 13Province Analysis
- 13.1Gyeonggi-do
- 13.2Seoul
- 13.3Incheon
- 13.4Sejong
- 13.5Busan and Gyeongnam
- 13.6Daejeon
- 13.7Gangwon and Jeju
- 13.8Chungcheong Provinces
- 13.9Daegu and Gyeongbuk
- 13.10Ulsan
- 13.11Jeollanam-do
- 13.12Gwangju and Jeonbuk
- 14Forecast Scenarios
- 14.1Low Scenario
- 14.2Base Scenario
- 14.3High Scenario
- 15Competitive Insights
- 15.1Dell Technologies
- 15.2NetApp
- 15.3Hewlett Packard Enterprise (HPE)
- 15.4Pure Storage
- 15.5IBM
- 15.6Hitachi Vantara
- 15.7Huawei Technologies
- 15.8Lenovo
- 15.9Nutanix
- 15.10Samsung SDS
- 15.11LG CNS
- 15.12SK Telecom
- 15.13KT Cloud
- 15.14NAVER Cloud
- 15.15Commvault
- 16Recent Developments
- 16.1Developments, October 2025 to October 2026
- 17Research Methodology
- 17.1Capacity Model and Receipt
- 17.2Bound Checks
- Fig. 11. South Korea Data Center Storage Market Size, 2020-2035
- Table 11. Market Snapshot, 2025, 2026 and 2035
- Table 22. Scope Comparison
- Table 33. Storage Spend per MW, 2020-2035
- Table 44. Market by Storage Type, 2025 and 2035
- Table 55. Market by Architecture, 2025 and 2035
- Table 66. Market by Component, 2025 and 2035
- Table 77. Market by End User, 2025 and 2035
- Table 88. NIRS Fire-to-Recovery Storage Ledger
- Table 99. Market by Region, 2025 and 2035
- Table 1010. Top 12 Provinces and Cities, 2025 and 2035
- Table 1111. Forecast Scenarios, 2035
About this report
Written by Amit Jain and reviewed by Deepti Agrawal, Senior Editor, Research. Figures are built top-down and bottom-up and reconciled before publication, with 2025 as the base year.
Read our methodologyHow we built this
- Historical period2020-2024
- Base year2025
- Forecast period2026-2035
- Sizing approachTop-down + bottom-up
Need more than the report?
Advisory on this market
Due diligence, site selection and market entry work, by the analysts who wrote this report.
See consulting servicesFrequently asked questions
USD 694.58 million in 2026, up 20.69% from USD 575.51 million in 2025, according to DC Market Insights estimates. The market is projected to reach USD 1.69 billion by 2035, a CAGR of 11.34% from 2025.
11.34% a year from 2025 to 2035, DC Market Insights estimates, slower than the 14.12% of 2020-2025 because storage spend per megawatt falls about 3% a year while installed capacity keeps rising.
All-flash arrays, at USD 287.75 million or 50% of 2025 spend, rising to 66% by 2035 because AI clusters need flash throughput to keep GPUs busy.
Object storage, at 17.99% a year from USD 80.57 million in 2025, because AI checkpoints and the off-site backup copies required after the NIRS fire move to S3-compatible capacity tiers.
The Capital Region, with USD 402.86 million or 70% of 2025 spend; the Honam Region grows fastest at 24.27% a year as Jeollanam-do campuses add AI capacity.
About USD 38 million of extra public storage spend in 2026-2027, DC Market Insights estimates, because the government now requires storage-based disaster recovery for grade A1 to A3 systems by 2027.
About USD 0.36 million per installed megawatt a year in 2025, plus about USD 1.10 million one-off per megawatt of new AI capacity, DC Market Insights estimates; the yearly rate falls to USD 0.27 million by 2035.
Dell Technologies, NetApp and Hewlett Packard Enterprise hold about 44% of external array spend together (DC Market Insights estimate), followed by Pure Storage, IBM, Hitachi Vantara and Huawei.
Estimates differ by up to 3 times because broader definitions add memory and SSD output, enterprise storage outside data centers and cloud subscriptions; DC Market Insights counts only storage bought for Korean data center halls, USD 575.51 million in 2025.
Between USD 1.25 billion and USD 1.96 billion, with a base case of USD 1.69 billion, DC Market Insights estimates; grid access for new AI halls decides which case plays out.
About 95 days. The fire on 26 September 2025 took 709 systems offline and burned 96 completely; all 709 were restored on 30 December 2025, according to the Ministry of the Interior and Safety.
One hour for A1 systems, recovered from a second center. The NIRS recovery briefing of 2 October 2026 also sets storage-based disaster recovery for grade A1 to A3 systems by 2027 and storage backup systems for all three government centers by the end of 2027.
About USD 150 million of storage, a DC Market Insights estimate at today's per-megawatt rate. NAVER, NVIDIA and Brookfield agreed in July 2026 to expand the GAK Sejong AI factory from 55 MW to 200 MW, adding about 145 MW. Sejong grows 15.16% a year to USD 113.27 million by 2035.
Get this report
How do I get the full report?
Request a quote; we reply by email within one business day.
How and when will I receive the report?
By email, within 24–48 business hours of payment.
How can I pay?
Once you accept the quote, we email you a secure payment link.
Can I see a sample first?
Yes. Request a free sample and we will email it to you.
Can the report be tailored to my needs?
Yes. We can add countries, segments or data cuts. Talk to an analyst about the scope you need.
Can I get an invoice or pay against a purchase order?
Write to sales@dcmarketinsights.com and our team will help.