
Taiwan Data Center Market Size, Share & Forecast to 2035
Market at a glance
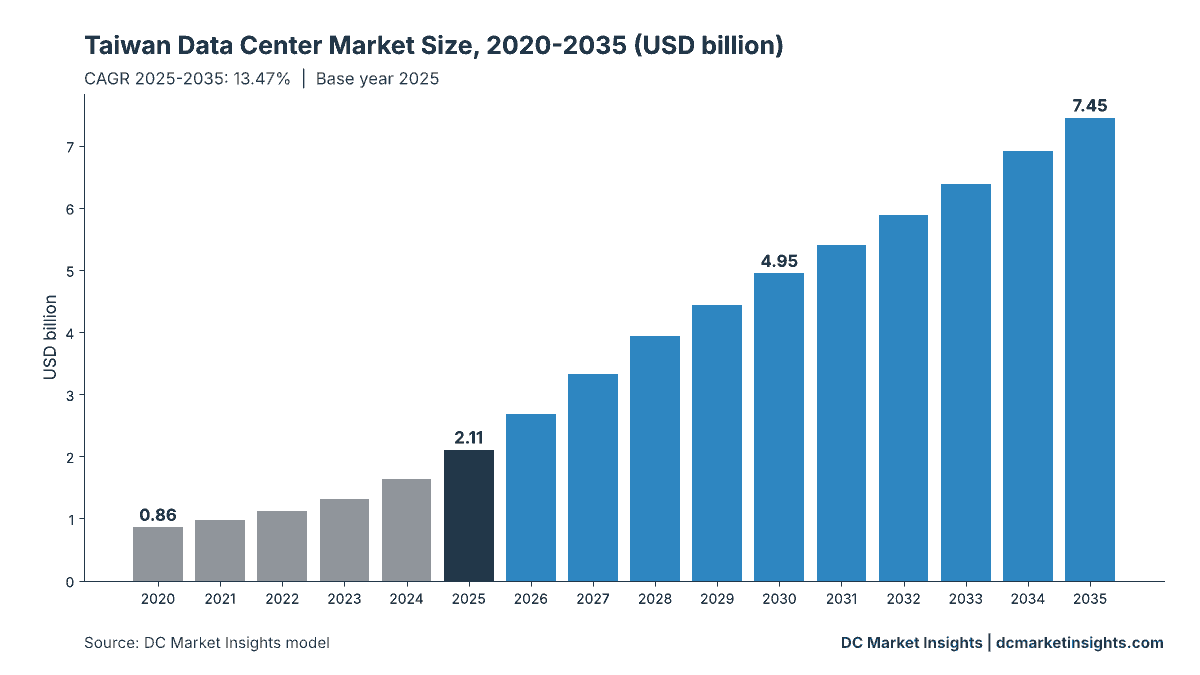
The Taiwan Data Center market was worth USD 2,110.0 million in 2025 and is forecast to reach USD 7,450.0 million by 2035, growing at a 13.47% CAGR. Northern Taiwan accounts for 62% of the market.
 By Amit Jain, Senior Consultant, ICT & Emerging Technologies
 Reviewed by Deepti Agrawal
Last updated 11 Oct 2026
Base year 2025 PDF + Excel
Source: DC Market Insights analysis
Key findings
Hyperscale Cloud Regions Commit More Than USD 5 Billion
Rack Densities Reach 200 kW and Lift Cooling to USD 1.29 billion
Grid Bottlenecks North of Taoyuan Cap Large Sites
Southern Taiwan Adds USD 1.76 billion by 2035
What is inside the report
- 01Introduction
- 02Research Methodology
- 03Executive Summary
- 04Market Scope and Definition: What Is the Taiwan Data Center Market?
- 05Taiwan Data Center Market Drivers
- 06Market Trends
- 07Market Challenges
- 08Market Opportunities
- 09Pricing Analysis: Content per MW and Electricity Tariffs
- 10Standards and Regulation
- 22chapters
- 2020-2024Historical period
- 2026-2035Forecast period
- 15Companies profiled
Regional insights
- Northern Taiwan62%
- Southern Taiwan19%
- Central Taiwan17%
- Eastern Taiwan and Offshore Islands2%
Segmentation
Companies profiled
- Chunghwa Telecom
- Chief Telecom
- Taiwan Mobile
- Far EasTone Telecommunications
- Amazon Web Services
- Microsoft
- Foxconn (Hon Hai Precision Industry)
- Visionbay.ai
- TECO Electric & Machinery
- Delta Electronics
- Quanta Computer
- Wiwynn
- Vertiv
- Schneider Electric
Recent developments
Foxconn, chip designer NVIDIA Corporation (NVIDIA) and the Taiwan government announced an AI factory featuring 10,000 NVIDIA Blackwell GPUs, with the National Science and Technology Council as a user (Source: NVIDIA newsroom).
Amazon launched the AWS Asia Pacific (Taipei) Region with three Availability Zones and plans to invest more than USD 5 billion in Taiwan (Source: Amazon press release).
Chunghwa Telecom outlined a hyperscale data center in northern Taiwan designed for at least 12 MW of IT load (Source: Chunghwa Telecom).
Foxconn and TECO Electric & Machinery formed an AI data center alliance through a share swap (Source: TECO press release).
the NCHC opened its 15 MW cloud computing center at the Southern Taiwan Science Park, and the MOEA set PUE caps of 1.3 for hyperscale and 1.4 for colocation data centers of 5 MW or more (Source: NSTC; MOEA).
the Executive Yuan approved the Ten AI Initiatives Promotion Plan to expand AI computing capacity (Source: National Development Council).
Full analysis
The Taiwan Data Center Market covers the annual investment in data center buildings and the equipment inside them across Taiwan: information technology (IT) infrastructure (general-purpose servers, storage and networking, excluding AI accelerator modules), power systems, cooling systems and general construction for colocation, hyperscale and cloud, enterprise and edge facilities. DC Market Insights values the Taiwan Data Center Market at USD 2.11 billion in 2025 and forecasts USD 7.45 billion by 2035, a CAGR of 13.47%. The build receipt: about 95 MW of new IT capacity in 2025, 45% of it built for artificial intelligence (AI), at roughly USD 15.2 million per MW in conventional halls and USD 16.0 million per MW in AI halls gives USD 1.48 billion of new-build spend, and IT refresh and facility upgrades on an installed base of about 615 MW add USD 628.09 million. Tier IV facilities are the fastest-growing segment at 17.80% a year because AI halls with 100 kW-plus racks are built to fault-tolerant designs, and Southern Taiwan is the fastest-growing region at 18.37% a year as grid bottlenecks north of Taoyuan push new campuses to Tainan and Kaohsiung.
Executive Summary
The Taiwan Data Center Market size was valued at USD 861.18 million in 2020, reached USD 2.11 billion in 2025, and is anticipated to reach USD 7.45 billion by 2035, at a CAGR of 13.47% during the forecast period.
| Report attribute | Details |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Taiwan Data Center Market Size 2025 | USD 2.11 Billion |
| Taiwan Data Center Market, CAGR | 13.47% |
| Taiwan Data Center Market Size 2035 | USD 7.45 Billion |
The market grew at 19.59% a year between 2020 and 2025, and 2025 alone added 28.9% over the USD 1.63 billion of 2024 as new IT capacity rose from about 72 MW to about 95 MW. DC Market Insights expects growth to slow to 13.47% a year from 2025 to 2035 because annual additions level off near 238 MW once the first wave of AI campuses is energized, while the recurring layer of IT refresh and facility upgrades rises from 29.8% of the market in 2025 to 38.6% in 2035 on an installed base that grows from about 615 MW to about 2,355 MW.
Market Scope: What Is the Taiwan Data Center Market?
The Taiwan Data Center Market is the money spent each year to build, equip and refresh data centers located in Taiwan, valued at installed price in current US dollars. DC Market Insights sizes it at USD 2.11 billion in 2025, equal to about USD 3.4 million for every MW of installed IT capacity.
Included. Servers, storage and network equipment for general workloads; uninterruptible power supplies (UPS), switchgear, generators and power distribution; chillers, computer room air handlers, rear-door and direct-to-chip liquid cooling; shell, core and fit-out construction; and the refresh and upgrade of these systems in existing facilities.
Excluded. AI accelerator modules (graphics processing units (GPUs) and similar chips), land, electricity bills, colocation rents, cloud service revenue, and servers built in Taiwan for export.
How the segments fit together. The infrastructure split adds IT infrastructure, power, cooling and general construction to the USD 2.11 billion total. The data center type, tier standard and end user splits re-cut the same total by facility model, by resilience level and by buyer, and the four regions and 12 cities and counties allocate it by location.
Market Drivers: What Drives the Taiwan Data Center Market?
Three drivers lift the Taiwan Data Center Market at 13.47% a year to 2035. They are hyperscale cloud regions that bring multi-billion-dollar budgets, government-backed sovereign AI compute, and AI power demand that the Ministry of Economic Affairs (MOEA) expects to rise about eightfold between 2023 and 2028.
Hyperscale Cloud Regions Commit More Than USD 5 Billion
The Taiwan Data Center Market moved into the hyperscale league in 2025. Amazon Web Services (AWS) launched its Asia Pacific (Taipei) Region in June 2025 and plans to invest more than USD 5 billion to build, connect, operate and maintain its data centers in Taiwan. Google has invested over USD 1.6 billion in its Changhua County campus since 2011, and Microsoft has been building its first Taiwan datacenters in Taoyuan. DC Market Insights estimates that hyperscale and cloud data centers took USD 716.14 million (34.0%) of 2025 spending and will reach USD 3.35 billion by 2035, growing at 16.69% a year.
Sovereign AI Compute Brings Government Money into the Market
In May 2025, Foxconn, chip designer NVIDIA Corporation (NVIDIA) and the Taiwan government announced an AI factory featuring 10,000 NVIDIA Blackwell GPUs, with the National Science and Technology Council (NSTC) as a user. On 28 January 2026 the Executive Yuan approved the Ten AI Initiatives Promotion Plan, which aims to expand AI computing capacity through public-private collaboration. DC Market Insights models the AI share of new Taiwan capacity rising from 45% in 2025 to 66% in 2030 and 70% in 2035, and the government and research end user segment growing at 14.81% a year to USD 670.63 million.
AI Power Demand Rises Eightfold to 2.24 GW by 2028
The MOEA’s 2023 power supply and demand report, published in July 2024, projects that electricity demand from AI technology rises from 0.24 GW in 2023 to 2.24 GW in 2028, an increase of about eight times. DC Market Insights models new data center IT capacity in Taiwan rising from about 95 MW in 2025 to 172 MW in 2028 and 198 MW in 2030, which more than doubles annual new-build spending to USD 3.44 billion by 2030. Each MW of new AI capacity carries about USD 16.0 million of facility and general-purpose IT content, so every 10 MW of AI load that Taiwan connects adds about USD 160 million of spending in the year it is built.
Market Trends: How Is the Taiwan Data Center Market Changing?
The Taiwan Data Center Market is shifting to very high rack densities, liquid cooling and modular, factory-built infrastructure supplied by Taiwan’s own electronics groups.
Rack Densities Reach 200 kW and Lift Cooling to USD 1.29 billion
Chief Telecom, a Chunghwa Telecom subsidiary, designed its newest AI data center for 1,800 racks with power density per cabinet ranging from 10 kW to 200 kW. Cooling is the fastest-growing infrastructure segment of the Taiwan Data Center Market at 14.02% a year, from USD 347.19 million in 2025 to USD 1.29 billion by 2035, because DC Market Insights estimates that cooling takes 33% of facility spend in an AI hall against 25% in a conventional hall. The supply chain for those systems is covered in the Taiwan Data Center Cooling Market report.
Taiwan Electronics Groups Move into Modular AI Data Centers
In July 2025, Foxconn and TECO Electric & Machinery (TECO) formed an AI data center alliance through a share swap, aiming at standardized and modular AI data center infrastructure. DC Market Insights expects factory-built power and cooling modules to keep general construction the slowest-growing infrastructure segment at 12.41% a year.
Operators Contract Clean Baseload Power
In April 2025, Google signed Taiwan’s first corporate geothermal agreement, with initial projects from Baseload Capital adding 10 MW for its Taiwan operations. DC Market Insights expects renewable supply terms to become part of most hyperscale site selections in Taiwan through 2030.
Market Challenges: What Holds the Taiwan Data Center Market Back?
Grid limits in the north, electricity prices that rose twice in 2024, and subsea cable risk are the three constraints that DC Market Insights expects to slow the Taiwan Data Center Market below its 2025 pace.
Grid Bottlenecks North of Taoyuan Cap Large Sites
In October 2024 the MOEA stated that several areas north of Taoyuan already face grid bottlenecks, and described data centers as an energy-intensive industry that governments manage carefully. National electricity demand is projected to grow only about 1.7% a year from 2025 to 2034, so large new loads compete for limited new supply. DC Market Insights models Northern Taiwan’s share of spending falling from 62.0% in 2025 to 50.0% in 2035.
Electricity Tariffs Rose 11% and Then 12.5% in 2024
The April 2024 tariff decision raised average prices by about 11% and set increases of 15% to 25% for internet data centers using 50 GWh or more a year. In October 2024 industrial rates rose a further 12.5%, to an average of 4.29 New Taiwan dollars (NT$) per kWh. DC Market Insights estimates that a 20 MW facility running at 70% load uses about 160 GWh a year after cooling, so each NT$0.10 per kWh adds about NT$16 million to its annual bill.
Subsea Cable Damage Raises the Cost of Resilience
The Ministry of Digital Affairs (MODA) recorded seven submarine cable incidents in 2025, three of them caused by anchor dragging, including damage to a Chunghwa Telecom international cable northeast of Yehliu in January and a full break of the Taiwan-Penghu No. 3 cable in February. DC Market Insights expects buyers to pay for more Tier IV and dual-site designs, which is one reason Tier IV grows at 17.80% a year.
Market Opportunities: Where Are the New Revenue Pools in the Taiwan Data Center Market?
The Taiwan Data Center Market gains two large revenue pools by 2035. AI-ready campuses in Southern Taiwan add USD 1.76 billion of annual spending, and the refresh of a fast-growing installed base adds USD 2.25 billion.
Southern Taiwan Adds USD 1.76 billion by 2035
Southern Taiwan spent USD 400.19 million on data centers in 2025, and DC Market Insights expects USD 2.16 billion by 2035. The National Center for High-performance Computing (NCHC) opened a 15 MW cloud computing center at the Southern Taiwan Science Park in Tainan in December 2025, and Foxconn’s advanced computing center in Kaohsiung was slated for completion by 2026.
Installed-Base Refresh Reaches USD 2.88 billion by 2035
IT refresh and facility upgrades are worth USD 628.09 million in 2025 and USD 2.88 billion in 2035. DC Market Insights models IT refresh at about USD 0.95 million per installed MW per year in 2025 and facility upgrades at about USD 0.24 million, on an installed base that grows from about 615 MW to about 2,355 MW.
Pricing: What Is the Taiwan Data Center Price per MW?
A conventional data center in Taiwan costs about USD 15.2 million per MW of IT load to build and equip in 2025, and an AI hall about USD 16.0 million per MW excluding accelerators. These are DC Market Insights estimates at installed price, covering facility infrastructure (USD 9.2 million and USD 12.5 million per MW) and general-purpose IT infrastructure (USD 6.0 million and USD 3.5 million per MW).
| Taiwan data center content per MW (USD million) | 2020 | 2025 | 2030 | 2035 |
|---|---|---|---|---|
| Conventional hall | 13.8 | 15.2 | 16.8 | 18.5 |
| AI hall (excluding accelerators) | 14.5 | 16.0 | 17.7 | 19.5 |
| AI share of new capacity | 5% | 45% | 66% | 70% |
Electricity sets the running cost. The October 2024 decision set the average industrial price at NT$4.29 per kWh, and the March 2025 review left prices unchanged. Data centers using 50 GWh or more a year carry the 15% to 25% surcharge set in April 2024. A cabinet density of 10 kW to 200 kW, as at Chief Telecom’s newest AI data center, means the price per rack varies by a factor of about 20, which is why DC Market Insights prices the market per MW of IT load rather than per rack.
Standards and Regulation: Which Rules Shape the Taiwan Data Center Market?
Four sets of rules decide how a data center is built in Taiwan: MOEA energy-efficiency rules, electricity tariff rules, resilience standards and information security law.
MOEA energy utilization rules. Since December 2025, data centers with contracted capacity of 5 MW or more need an approved Energy Utilization Manual before construction, with a PUE not exceeding 1.3 for hyperscale data centers and 1.4 for colocation data centers. Power usage effectiveness (PUE) is total facility energy divided by IT energy.
Electricity tariffs for internet data centers. The Electricity Price Review Committee treats internet data centers using 50 GWh or more a year as a separate group, with the 15% to 25% surcharge set in April 2024.
Uptime Institute Tier and ANSI/TIA-942. Taiwan colocation and cloud operators specify resilience against the Uptime Institute Tier classification and the Telecommunications Industry Association (TIA) data center standard; DC Market Insights estimates that Tier III facilities take 66.0% of 2025 spending.
Cyber Security Management Act and ISO/IEC 27001. Government agencies and critical infrastructure providers must meet the Cyber Security Management Act, and colocation operators in Taiwan commonly certify their facilities to ISO/IEC 27001.
Market Segmentation: Which Segment Leads the Taiwan Data Center Market, and What Is the Fastest Growing Taiwan Data Center Segment?
Tier IV facilities are the fastest-growing Taiwan data center segment at 17.80% a year, ahead of hyperscale and cloud data centers at 16.69%, because AI halls are built to fault-tolerant designs. IT infrastructure leads the Taiwan Data Center Market with 45.8% of 2025 value, colocation data centers lead facility types with 38.0%, and cloud and AI service providers lead buyers with 34.0%.
By Infrastructure: IT Infrastructure Leads with 45.8%
| Infrastructure | 2025 (USD million) | Share 2025 | 2035 (USD million) | CAGR 2025-2035 |
|---|---|---|---|---|
| IT Infrastructure | 964.54 | 45.8% | 3,483.52 | 13.70% |
| Power | 457.69 | 21.7% | 1,593.23 | 13.28% |
| Cooling | 347.19 | 16.5% | 1,289.37 | 14.02% |
| General Construction | 336.87 | 16.0% | 1,085.35 | 12.41% |
Cooling gains 0.8 points of share by 2035 as liquid cooling becomes standard in AI halls, while general construction loses share as modular power and cooling skids move work from site to factory.
By Data Center Type: Colocation Data Centers Lead with 38.0%
| Data center type | 2025 (USD million) | Share 2025 | 2035 (USD million) | CAGR 2025-2035 |
|---|---|---|---|---|
| Colocation Data Centers | 800.39 | 38.0% | 2,458.99 | 11.88% |
| Hyperscale and Cloud Data Centers | 716.14 | 34.0% | 3,353.16 | 16.69% |
| Enterprise Data Centers | 421.26 | 20.0% | 894.18 | 7.82% |
| Edge Data Centers | 168.50 | 8.0% | 745.15 | 16.03% |
Hyperscale and cloud data centers overtake colocation by 2035 with 45.0% of value against 33.0%. Colocation buyers and prices are covered in the Taiwan Data Center Colocation Market report.
By Tier Standard: Tier III Leads with 66.0%
| Tier standard | 2025 (USD million) | Share 2025 | 2035 (USD million) | CAGR 2025-2035 |
|---|---|---|---|---|
| Tier III | 1,390.15 | 66.0% | 4,619.91 | 12.76% |
| Tier IV | 463.38 | 22.0% | 2,384.47 | 17.80% |
| Tier I and II | 252.75 | 12.0% | 447.09 | 5.87% |
Tier IV spending grows from USD 463.38 million in 2025 to USD 2.38 billion by 2035, rising from 22.0% to 32.0% of value by 2035, and Tier I and II facilities grow at only 5.87% a year as small enterprise server rooms move to colocation and cloud.
By End User: Cloud and AI Service Providers Lead with 34.0%
| End user | 2025 (USD million) | Share 2025 | 2035 (USD million) | CAGR 2025-2035 |
|---|---|---|---|---|
| Cloud and AI Service Providers | 716.14 | 34.0% | 3,278.65 | 16.43% |
| IT and Telecom | 631.89 | 30.0% | 1,788.35 | 10.96% |
| Banking and Financial Services | 252.75 | 12.0% | 670.63 | 10.25% |
| Manufacturing and Semiconductors | 210.63 | 10.0% | 745.15 | 13.47% |
| Government and Research | 168.50 | 8.0% | 670.63 | 14.81% |
| Healthcare and Others | 126.38 | 6.0% | 298.06 | 8.96% |
Manufacturing and semiconductors keep a steady 10% share as chipmakers and electronics groups build private AI clusters for design and factory automation.
DC Exclusive: The Taiwan Data Center Content per MW Model and Infrastructure × Data Center Type Matrix
At USD 350.14 million in 2025, IT infrastructure in hyperscale and cloud data centers is the single largest cell of the matrix and 16.6% of all Taiwan data center spending. The matrix below cross-tabulates what is bought against who buys it. It is a DC Market Insights model, not a shipment count: it is built from 46 inputs: 32 capacity cohorts (16 years of conventional and AI halls), 4 content-per-MW rates, 6 infrastructure split ratios, 2 installed-base rates, 1 retirement rate and 1 price escalation rate, and then tested against 3 bound checks.
| 2025, USD million | Colocation | Hyperscale and Cloud | Enterprise | Edge |
|---|---|---|---|---|
| IT Infrastructure | 334.81 | 350.14 | 209.99 | 69.60 |
| Power | 190.08 | 139.02 | 88.68 | 39.91 |
| Cooling | 134.09 | 124.06 | 61.17 | 27.88 |
| General Construction | 141.41 | 102.92 | 61.43 | 31.11 |
| Total | 800.39 | 716.14 | 421.26 | 168.50 |
Colocation operators spend 23.7% of their budget on power systems because multi-tenant halls are sold by the kW and need redundant feeds, while hyperscale and cloud operators spend 48.9% of theirs on IT infrastructure because they own the servers and networks inside their halls. Edge data centers spend 23.7% on power, as small sites carry the same UPS and generator layers on less IT load.
The content per MW model has two inputs any reader can check: new IT capacity delivered each year (about 95 MW in 2025) and the share built for AI (45% in 2025). Multiplying each by its content per MW gives new-build spend; adding IT refresh and facility upgrades on the installed base gives the market. The model and its assumptions are explained on our research methodology page.
Regional Insights: Which Region Leads the Taiwan Data Center Market?
Northern Taiwan leads the Taiwan Data Center Market with 62.0% of 2025 value. Southern Taiwan is the fastest-growing region at 18.37% a year because grid bottlenecks north of Taoyuan and the science parks in Tainan and Kaohsiung pull new AI campuses south.
Northern Taiwan Holds 62.0% Share
Northern Taiwan is worth USD 1.31 billion in 2025 and USD 3.73 billion by 2035, a CAGR of 11.05%. Taipei, New Taipei and Taoyuan host the AWS Asia Pacific (Taipei) Region, Microsoft’s Taoyuan datacenters and Chief Telecom’s 20 MW AI data center, and Chunghwa Telecom plans a hyperscale site of at least 12 MW of IT load in the north.
Southern Taiwan Holds 19.0% Share
Southern Taiwan is worth USD 400.19 million in 2025 and USD 2.16 billion by 2035, a CAGR of 18.37%. The NCHC cloud computing center in Tainan opened with an installed power capacity of 15 megawatts in December 2025, and Foxconn’s Kaohsiung advanced computing center consists of 64 racks and 4,608 GPUs.
Central Taiwan Holds 17.0% Share
Central Taiwan is worth USD 358.07 million in 2025 and USD 1.42 billion by 2035, a CAGR of 14.74%. Google’s Changhua County campus, Google’s first data center in Taiwan, opened in 2013 and has absorbed over USD 1.6 billion of investment.
Eastern Taiwan and Offshore Islands Holds 2.0% Share
Eastern Taiwan and Offshore Islands is worth USD 42.13 million in 2025 and USD 149.03 million by 2035, a CAGR of 13.47%. Hualien, Taitung and the islands host mainly edge and government sites, and Penghu’s link to the main island depends on subsea cables that were cut in 2025.
City and County Analysis: Where in Taiwan Is Data Center Spending Concentrated?
Taoyuan City is the largest location in the Taiwan Data Center Market at USD 400.19 million in 2025, 19.0% of national value, followed by New Taipei City at USD 358.07 million (17.0%) and Taipei City at USD 294.88 million (14.0%). The 12 largest cities and counties account for 96.0% of 2025 spending.
| Rank | City or county | Region | 2025 (USD million) | Share 2025 | 2035 (USD million) | CAGR 2025-2035 |
|---|---|---|---|---|---|---|
| 1 | Taoyuan City | Northern Taiwan | 400.19 | 19.0% | 1,266.75 | 12.21% |
| 2 | New Taipei City | Northern Taiwan | 358.07 | 17.0% | 968.69 | 10.46% |
| 3 | Taipei City | Northern Taiwan | 294.88 | 14.0% | 670.63 | 8.56% |
| 4 | Tainan City | Southern Taiwan | 189.57 | 9.0% | 968.69 | 17.72% |
| 5 | Kaohsiung City | Southern Taiwan | 168.50 | 8.0% | 968.69 | 19.11% |
| 6 | Changhua County | Central Taiwan | 168.50 | 8.0% | 596.12 | 13.47% |
| 7 | Hsinchu City and County | Northern Taiwan | 147.44 | 7.0% | 447.09 | 11.73% |
| 8 | Taichung City | Central Taiwan | 105.31 | 5.0% | 447.09 | 15.56% |
| 9 | Yunlin County | Central Taiwan | 63.19 | 3.0% | 298.06 | 16.78% |
| 10 | Keelung City | Northern Taiwan | 63.19 | 3.0% | 223.54 | 13.47% |
| 11 | Yilan County | Northern Taiwan | 42.13 | 2.0% | 149.03 | 13.47% |
| 12 | Miaoli County | Central Taiwan | 21.06 | 1.0% | 74.51 | 13.47% |
Kaohsiung City is the fastest-growing large location at 19.11% a year, as AI and sovereign compute projects locate near the southern science parks. The city and county figures are a DC Market Insights allocation of the regional totals, weighted by each location’s estimated share of installed and new data center capacity.
Forecast Scenarios: How Could the 2035 Taiwan Data Center Forecast Change?
The Taiwan Data Center Market reaches USD 7.45 billion by 2035 in the base case, with a range of USD 6.24 billion to USD 8.71 billion across the low and high scenarios.
| Scenario | Assumption from 2026 | 2035 (USD billion) | CAGR 2025-2035 |
|---|---|---|---|
| Low | New capacity 15% below base; IT refresh spend 10% lower | 6.24 | 11.48% |
| Base | Additions rise to 238 MW a year; AI share of new capacity reaches 70% | 7.45 | 13.47% |
| High | New capacity 15% above base; IT refresh spend 10% higher | 8.71 | 15.25% |
The low case reflects slower grid connections in the north and a pause in AI capital spending. The high case assumes that the Ten AI Initiatives and hyperscale regions bring forward campuses now planned for after 2030.
Competitive Insights: Who Leads the Taiwan Data Center Market?
- Chunghwa Telecom
- Chief Telecom
- Taiwan Mobile
- Far EasTone Telecommunications
- Amazon Web Services
- Microsoft
- Foxconn (Hon Hai Precision Industry)
- Visionbay.ai
- TECO Electric & Machinery
- Delta Electronics
- Quanta Computer
- Wiwynn
- Vertiv
- Schneider Electric
The Taiwan Data Center Market is concentrated among a few large spenders: DC Market Insights estimates that the three largest investors, Amazon Web Services, the Chunghwa Telecom group (including Chief Telecom) and Google, together accounted for about 38% of 2025 spending. The estimate spreads AWS’s pledge of more than USD 5 billion over the 15-year horizon AWS gave in 2024 (about USD 333 million a year, or 15.8% of the market), and adds estimates for Chunghwa Telecom’s new and converted data halls and Google’s Changhua campus upgrades. Chunghwa Telecom plans a hyperscale data center in northern Taiwan designed for at least 12 MW of IT load and is converting existing sites to AI-ready halls (Source: Chunghwa Telecom). Chief Telecom’s newest AI data center draws 20 MW from dual Taipower stations. Google states it has invested over USD 1.6 billion in Taiwan since 2011, and Microsoft notes that completing its Taoyuan buildings does not indicate datacenter availability. Foxconn and Visionbay.ai are building a sovereign AI supercomputing center on NVIDIA GB300 NVL72 systems, and Delta Electronics, Quanta Computer and Wiwynn supply power systems and servers from Taiwan.
Recent Developments
- In May 2025, Foxconn, chip designer NVIDIA Corporation (NVIDIA) and the Taiwan government announced an AI factory featuring 10,000 NVIDIA Blackwell GPUs, with the National Science and Technology Council as a user (Source: NVIDIA newsroom).
- In June 2025, Amazon launched the AWS Asia Pacific (Taipei) Region with three Availability Zones and plans to invest more than USD 5 billion in Taiwan (Source: Amazon press release).
- In July 2025, Chunghwa Telecom outlined a hyperscale data center in northern Taiwan designed for at least 12 MW of IT load (Source: Chunghwa Telecom).
- In July 2025, Foxconn and TECO Electric & Machinery formed an AI data center alliance through a share swap (Source: TECO press release).
- In December 2025, the NCHC opened its 15 MW cloud computing center at the Southern Taiwan Science Park, and the MOEA set PUE caps of 1.3 for hyperscale and 1.4 for colocation data centers of 5 MW or more (Source: NSTC; MOEA).
- In January 2026, the Executive Yuan approved the Ten AI Initiatives Promotion Plan to expand AI computing capacity (Source: National Development Council).
We follow these launches, deals and rules as they happen in our data center industry updates. Buyers planning sites outside the main campuses can compare locations in the Taiwan Edge Data Center Market report.
Methodology: How We Built the Taiwan Data Center Market Model
DC Market Insights built this market bottom-up from 16 annual capacity cohorts (2020 to 2035), each split into conventional and AI halls. New-build spend multiplies each cohort by its content per MW: USD 9.2 million of facility infrastructure and USD 6.0 million of IT infrastructure per MW in conventional halls, and USD 12.5 million and USD 3.5 million per MW in AI halls, in 2025 prices escalating 2% a year. Installed-base spend adds IT refresh at USD 0.95 million per installed MW per year in 2025 and facility upgrades at USD 0.24 million per installed MW per year. The installed base of about 615 MW in 2025 retires at 1.5% a year. The total was split by 4 infrastructure types, 4 data center types, 3 tier standards, 6 end users, 4 regions and 12 cities and counties, and every split sums to the market total.
Because no statistics office publishes Taiwan data center spending, the result was tested against three bounds. Ceiling one: the modeled installed base of about 1,026 MW in 2028 at a PUE of 1.35 implies about 1.38 GW of data center power, below the MOEA’s projection of 2.24 GW of AI electricity demand in 2028. Ceiling two: 2025 spending of USD 2.11 billion is 22.5% of the roughly USD 9.35 billion replacement value of the installed base, well below the whole stock. Floor: Chief Telecom’s single 20 MW AI data center at USD 9.2 million of facility content per MW represents about USD 184 million, about 8.7% of the modeled market. The analyst named on this page built the model, and the reviewer checked the arithmetic, the sources and the dates before publication.
Table of contents
- 01Introduction
- 1.1Market Definition
- 1.2Historical Period, Base Year and Forecast Period
- 1.3Report Attributes
- 02Research Methodology
- 2.1Build Receipt: New IT Capacity × Content per MW
- 2.2IT Refresh and Facility Upgrades on the Installed Base
- 2.3Segment, Region and City and County Allocation
- 2.4Bound Checks: AI Power Demand, Replacement Value and Project Floor
- 03Executive Summary
- 3.1Market Snapshot, 2020, 2025 and 2035
- 3.2Growth Outlook, 2025-2035
- 04Market Scope and Definition: What Is the Taiwan Data Center Market?
- 4.1Included: IT Infrastructure, Power, Cooling and Construction
- 4.2Excluded: AI Accelerators, Land, Electricity, Rents, Cloud Revenue and Export Servers
- 4.3How the Segments Fit Together
- 05Taiwan Data Center Market Drivers
- 5.1Hyperscale Cloud Regions Commit More Than USD 5 Billion
- 5.2Sovereign AI Compute Brings Government Money into the Market
- 5.3AI Power Demand Rises Eightfold to 2.24 GW by 2028
- 06Market Trends
- 6.1Rack Densities Reach 200 kW and Lift Cooling to USD 1.29 billion
- 6.2Taiwan Electronics Groups Move into Modular AI Data Centers
- 6.3Operators Contract Clean Baseload Power
- 07Market Challenges
- 7.1Grid Bottlenecks North of Taoyuan Cap Large Sites
- 7.2Electricity Tariffs Rose 11% and Then 12.5% in 2024
- 7.3Subsea Cable Damage Raises the Cost of Resilience
- 08Market Opportunities
- 8.1Southern Taiwan Adds USD 1.76 billion by 2035
- 8.2Installed-Base Refresh Reaches USD 2.88 billion by 2035
- 09Pricing Analysis: Content per MW and Electricity Tariffs
- 9.1Conventional Hall Content per MW
- 9.2AI Hall Content per MW (Excluding Accelerators)
- 9.3AI Share of New Capacity
- 9.4Industrial Electricity Price and Data Center Surcharge
- 10Standards and Regulation
- 10.1MOEA Energy Utilization Rules and PUE Caps
- 10.2Electricity Tariffs for Internet Data Centers
- 10.3Uptime Institute Tier and ANSI/TIA-942
- 10.4Cyber Security Management Act and ISO/IEC 27001
- 11Taiwan Data Center Market, By Infrastructure
- 11.1IT Infrastructure
- 11.2Power
- 11.3Cooling
- 11.4General Construction
- 12Taiwan Data Center Market, By Data Center Type
- 12.1Colocation Data Centers
- 12.2Hyperscale and Cloud Data Centers
- 12.3Enterprise Data Centers
- 12.4Edge Data Centers
- 13Taiwan Data Center Market, By Tier Standard
- 13.1Tier III
- 13.2Tier IV
- 13.3Tier I and II
- 14Taiwan Data Center Market, By End User
- 14.1Cloud and AI Service Providers
- 14.2IT and Telecom
- 14.3Banking and Financial Services
- 14.4Manufacturing and Semiconductors
- 14.5Government and Research
- 14.6Healthcare and Others
- 15DC Exclusive: Content per MW Model and Infrastructure × Data Center Type Matrix
- 15.1Infrastructure × Data Center Type Matrix, 2025
- 15.2Spending Mix by Data Center Type
- 15.3Content per MW Model Inputs
- 16Taiwan Data Center Market, By Region
- 16.1Northern Taiwan
- 16.2Southern Taiwan
- 16.3Central Taiwan
- 16.4Eastern Taiwan and Offshore Islands
- 17City and County Analysis
- 17.1Taoyuan City
- 17.2New Taipei City
- 17.3Taipei City
- 17.4Tainan City
- 17.5Kaohsiung City
- 17.6Changhua County
- 17.7Hsinchu City and County
- 17.8Taichung City
- 17.9Yunlin County
- 17.10Keelung City
- 17.11Yilan County
- 17.12Miaoli County
- 18Forecast Scenarios 2035
- 18.1Low Scenario
- 18.2Base Scenario
- 18.3High Scenario
- 19Competitive Landscape
- 19.1Market Concentration: Three Largest Investors, 2025
- 19.2Hyperscale Cloud Providers: AWS, Google and Microsoft
- 19.3Telecom Operators: Chunghwa Telecom and Chief Telecom
- 19.4Sovereign AI Builders and Taiwan Suppliers
- 20Company Profiles
- 20.1Chunghwa Telecom
- 20.2Chief Telecom
- 20.3Taiwan Mobile
- 20.4Far EasTone Telecommunications
- 20.5Google
- 20.6Amazon Web Services
- 20.7Microsoft
- 20.8Foxconn (Hon Hai Precision Industry)
- 20.9Visionbay.ai
- 20.10TECO Electric & Machinery
- 20.11Delta Electronics
- 20.12Quanta Computer
- 20.13Wiwynn
- 20.14Vertiv
- 20.15Schneider Electric
- 21Recent Developments
- 21.1Foxconn, NVIDIA and Taiwan Government AI Factory (May 2025)
- 21.2AWS Asia Pacific (Taipei) Region Launch (June 2025)
- 21.3Chunghwa Telecom Hyperscale Data Center Plan (July 2025)
- 21.4Foxconn and TECO AI Data Center Alliance (July 2025)
- 21.5NCHC 15 MW Cloud Computing Center and MOEA PUE Caps (December 2025)
- 21.6Ten AI Initiatives Promotion Plan (January 2026)
- 22Appendix
- 22.1Abbreviations: IT, AI, UPS, GPU, MOEA, NSTC, NCHC, MODA, PUE, TIA, CAGR
- Fig. 1Taiwan Data Center Market Size, 2020-2035 (USD Million)
- Table 1Report Attributes
- Table 2Content per MW, 2020-2035 (USD Million)
- Table 3Market by Infrastructure, 2025 and 2035
- Table 4Market by Data Center Type, 2025 and 2035
- Table 5Market by Tier Standard, 2025 and 2035
- Table 6Market by End User, 2025 and 2035
- Table 7Infrastructure × Data Center Type Matrix, 2025
- Table 8Top 12 Cities and Counties, 2025 and 2035
- Table 9Forecast Scenarios, 2035
About this report
Written by Amit Jain and reviewed by Deepti Agrawal, Senior Editor, Research. Figures are built top-down and bottom-up and reconciled before publication, with 2025 as the base year.
Read our methodologyHow we built this
- Historical period2020-2024
- Base year2025
- Forecast period2026-2035
- Sizing approachTop-down + bottom-up
Need more than the report?
Advisory on this market
Due diligence, site selection and market entry work, by the analysts who wrote this report.
See consulting servicesFrequently asked questions
USD 2.11 billion in 2025: the Taiwan Data Center Market is the annual spending to build, equip and refresh data centers in Taiwan, covering IT infrastructure, power, cooling and construction. DC Market Insights forecasts USD 7.45 billion by 2035.
13.47% a year from 2025 to 2035, after 19.59% a year between 2020 and 2025, when new IT capacity rose to about 95 MW a year and AI halls took 45% of it.
About USD 15.2 million per MW for a conventional hall and USD 16.0 million per MW for an AI hall excluding accelerators in 2025, DC Market Insights estimates. Industrial electricity averages NT$4.29 per kWh after the October 2024 tariff decision.
Tier IV facilities, at 17.80% a year from USD 463.38 million in 2025 to USD 2.38 billion by 2035. Hyperscale and cloud data centers follow at 16.69%, and cooling is the fastest infrastructure segment at 14.02%.
45.8% of 2025 value, or USD 964.54 million, goes to IT infrastructure. Colocation data centers lead facility types with 38.0%.
62.0% of 2025 value, or USD 1.31 billion, is spent in Northern Taiwan. Southern Taiwan grows fastest at 18.37% a year as grid bottlenecks north of Taoyuan push AI campuses to Tainan and Kaohsiung.
About 38% of 2025 spending comes from Amazon Web Services, the Chunghwa Telecom group and Google combined (DC Market Insights estimate). Taiwan Mobile, Far EasTone, Microsoft, Foxconn, TECO Electric & Machinery, Delta Electronics, Quanta Computer and Wiwynn also compete.
More than USD 5 billion, according to Amazon, which launched the AWS Asia Pacific (Taipei) Region in June 2025. DC Market Insights spreads it at about USD 333 million a year over 15 years.
Get this report
How do I get the full report?
Request a quote; we reply by email within one business day.
How and when will I receive the report?
By email, within 24–48 business hours of payment.
How can I pay?
Once you accept the quote, we email you a secure payment link.
Can I see a sample first?
Yes. Request a free sample and we will email it to you.
Can the report be tailored to my needs?
Yes. We can add countries, segments or data cuts. Talk to an analyst about the scope you need.
Can I get an invoice or pay against a purchase order?
Write to sales@dcmarketinsights.com and our team will help.