
India Data Center Market Size, Share & Forecast to 2035
Market at a glance
The India Data Center market was worth USD 9,040.0 million in 2025 and is forecast to reach USD 57.22 billion by 2035, growing at a 20.27% CAGR.
 By Amit Jain, Senior Consultant, ICT & Emerging Technologies
 Reviewed by Deepti Agrawal
Last updated 30 Oct 2026
Base year 2025 PDF + Excel
Key findings
Budget 2026-27 Tax Holiday Until 2047 for Cloud Exports From Indian Data Centres
Conglomerates Build Gigawatt Campuses: Reliance and Tata
Industrial Power at INR 10.78 per kWh in Maharashtra
Cooling Systems: USD 386.49 Million in 2025 to USD 2.34 Billion in 2035
What is inside the report
- 01Key Market Statistics
- 02Key Takeaways
- 03India Data Center Market Summary
- 04What Does the India Data Center Market Include?
- 05Why Do India Data Center Market Estimates Differ?
- 06Market Drivers
- 07Market Trends
- 08Market Challenges
- 09Market Opportunities
- 10Pricing
- 19chapters
- 2020-2024Historical period
- 2026-2035Forecast period
- —Companies profiled
Segmentation
Recent developments
Google announced about USD 15 billion for a Visakhapatnam AI hub over 2026-2030 (Source: Press Information Bureau).
TCS and TPG agreed to commit up to INR 18,000 crore to HyperVault AI data centres (Source: Tata Group).
Microsoft committed USD 17.5 billion to India for 2026-2029 (Source: Microsoft).
the Union Budget 2026-27 gave foreign cloud providers using Indian data centres a tax holiday to 2047 (Source: Press Information Bureau).
Bharti Airtel announced a USD 1 billion investment in Nxtra led by Alpha Wave Global and Carlyle (Source: Bharti Airtel).
Reliance Industries and Meta agreed to build a 168 MW AI data centre in Jamnagar (Source: Reliance Industries).
Full analysis
The India Data Center Market is valued at USD 12.60 billion in 2026 and is projected to reach USD 57.22 billion by 2035, up from USD 9.04 billion in 2025, a CAGR of 20.27% from 2025 to 2035 (DC Market Insights estimate). The money in India moves with megawatts that clear the grid: the Ministry of Electronics and Information Technology (MeitY) told Parliament in March 2026 that national capacity grew from about 375 MW in 2020 to about 1,500 MW by 2025, and DC Market Insights expects 450 MW of new IT load in 2026 alone, against 305 MW in 2025. The Union Budget 2026-27 then changed who pays for those halls, giving notified foreign cloud providers a tax holiday until 2047 if they serve the world from data centre capacity bought from Indian operators (Source: Press Information Bureau). The 2025 build receipt is 305 MW x USD 6.34 million per MW = USD 1.93 billion of facilities, plus USD 2.34 billion of AI servers and USD 4.77 billion of conventional IT on 2,384 MW of operating conventional load. AI workloads grow fastest at 29.83% a year, and Southern India is the fastest region at 23.58% because Google’s gigawatt-scale Visakhapatnam campus and new Chennai and Hyderabad halls shift the build away from Mumbai.
Key Market Statistics: How Big Is the India Data Center Market in 2026?
The India Data Center Market reaches USD 12.60 billion in 2026, 39.44% above the USD 9.04 billion of 2025. DC Market Insights values the year’s 450 MW of new IT load and the servers that fill it.
- Market size 2025: USD 9.04 billion (DC Market Insights estimate)
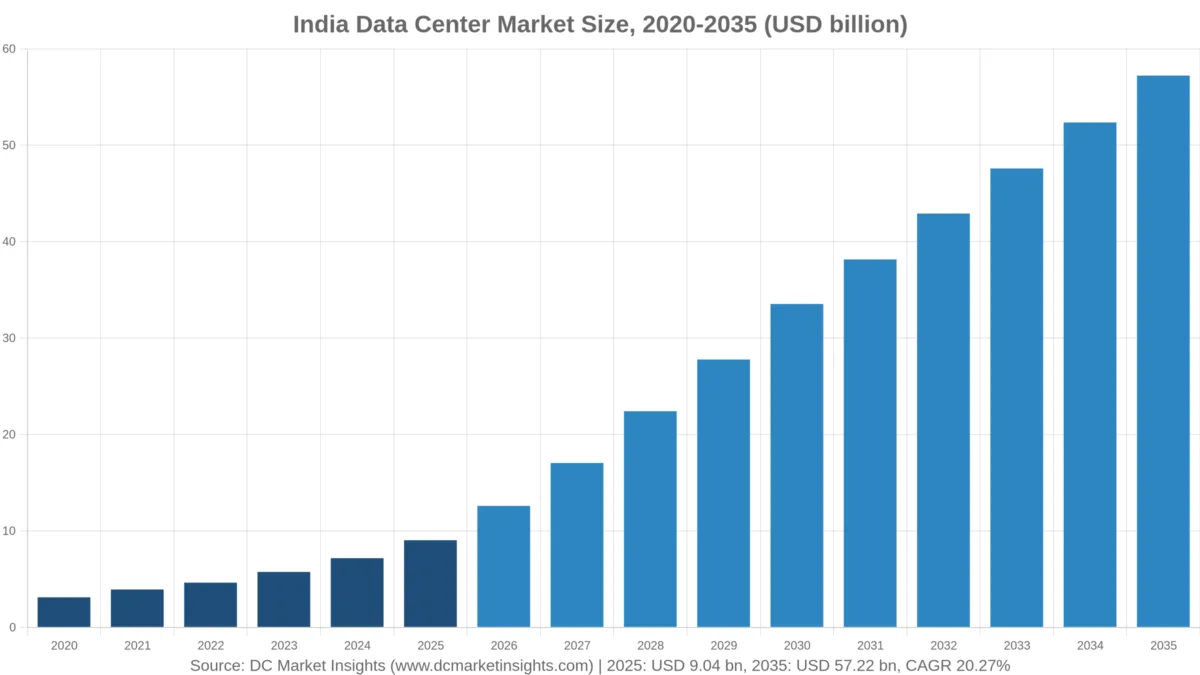
- Market size 2026: USD 12.60 billion, up 39.44%
- Market size 2030: USD 33.54 billion
- Market size 2035: USD 57.22 billion
- CAGR 2025-2035: 20.27% in the base case (17.47% low case, 22.68% high case)
- Largest segment: IT Infrastructure, USD 7.10 billion or 78.62% of 2025 value
- Fastest segment: AI Workloads, 29.83% a year to USD 38.37 billion in 2035
- Leading region: Western India, 48.00% of 2025 value; fastest region: Southern India, 23.58% a year
- Largest state: Maharashtra, USD 3.84 billion in 2025; fastest state: Andhra Pradesh, 41.27% a year
- Largest operators by published capacity: ST Telemedia Global Data Centres (STT GDC) India (over 400 MW) and Nxtra by Airtel (about 300 MW), together about 47% of the 1,500 MW national base
Key Takeaways: What Should Buyers and Investors Know About India’s Data Center Build?
Four figures explain the India Data Center Market to 2035.
- New IT load rises from 305 MW in 2025 to 950 MW in 2030, because hyperscale self-builds in Visakhapatnam, Jamnagar and Hyderabad add gigawatt-class campuses on top of colocation.
- AI workloads lift from 31.21% of spend in 2025 to 67.05% in 2035, because each AI megawatt carries about USD 25 million of servers against USD 2.00 million a year for a conventional megawatt.
- Maharashtra’s share falls from 42.50% to 33.00% by 2035, because Andhra Pradesh, Telangana and Uttar Pradesh offer land, subsea landings and state incentives that Mumbai cannot match on cost.
- Power cost is the largest operating risk: the Maharashtra Electricity Regulatory Commission (MERC) set the HT-Industry average billing rate at INR 10.78 per kWh for FY26, so a 1 MW IT hall at a power usage effectiveness (PUE) of 1.5 pays about INR 14.2 crore a year for electricity.
India Data Center Market Summary: How Much Did India Spend on Data Centers in 2025?
The India Data Center Market size was valued at USD 3.12 billion in 2020, reached USD 9.04 billion in 2025, and is anticipated to reach USD 57.22 billion by 2035, at a CAGR of 20.27% during the forecast period.
| Attribute | Value |
|---|---|
| Historical period | 2020-2024 |
| Base year | 2025 |
| Forecast period | 2026-2035 |
| Market size 2025 | USD 9.04 billion |
| Market size 2026 | USD 12.60 billion |
| CAGR 2025-2035 | 20.27% |
| Market size 2035 | USD 57.22 billion |
| Unit | USD million, current prices |
DC Market Insights estimates that India’s spend grew 23.71% a year between 2020 and 2025, faster than the 20.27% forecast for 2025-2035, because the base was small: 70 MW of new IT load in 2020 against 305 MW in 2025. The next decade adds 9,100 MW, so annual new build climbs to 1,200 MW by 2035 and the operating commercial base reaches 10,605 MW.
What Does the India Data Center Market Include?
The India Data Center Market covers USD 9.04 billion of 2025 spending on data center facilities built in India and the IT equipment installed in them, measured as annual capital and refresh spend.
Included
The scope counts power, cooling and construction for new commercial halls (USD 1.93 billion in 2025), AI servers and their refresh (USD 2.34 billion), and servers, storage and networking for conventional workloads in colocation, hyperscale and enterprise or government in-house rooms (USD 4.77 billion). Small and mid-sized enterprises (SMEs) that rent racks in colocation are inside the colocation figure.
Excluded
Cloud service revenue, IT services and outsourcing, software licences, land, electricity bills, telecom radio networks and data centre REIT valuations are outside the estimate, as are hyperscale investments booked in India but spent on non-data-center businesses.
How the Segments Fit Together
Every dimension sums to the same total each year: component (IT, power, cooling, construction), workload (AI and conventional), data center type and end user. The 5 regions sum to the national figure, and the 12 states in the country table cover 95.40% of 2025 value.
Why Do India Data Center Market Estimates Differ?
DC Market Insights values the India Data Center Market at USD 12.60 billion in 2026; estimates for the same market name range from a few billion dollars, when only colocation rent is counted, to well above USD 20 billion, when cloud services and IT outsourcing are added.
Broader definitions add public cloud consumption, managed services, data center colocation services revenue and electricity, while narrower ones count only third-party colocation revenue; India Data Center Colocation Market figures are therefore a slice of this total. This edition replaces an earlier, higher DC Market Insights figure that was not tied to a capacity base; the new figure rests on the 1,500 MW national capacity that MeitY reported to Parliament. Terms such as data center construction market, hyperscale data center market, edge data center, green data center and modular data center describe parts that sit inside this scope when they are spent on India’s halls.
| Element | In this report | Why |
|---|---|---|
| Facility power, cooling, construction | Yes, USD 1.93 billion (2025) | Capex on new IT MW |
| AI servers and refresh | Yes, USD 2.34 billion | Fit-out of AI halls |
| Conventional servers, storage, network | Yes, USD 4.77 billion | Spend per operating MW |
| Cloud service revenue | No | Service layer, not infrastructure |
| Electricity and land | No | Operating cost and real estate |
| IT outsourcing and software | No | Service and licence revenue |
The same buyer groups appear in every definition: hyperscale cloud providers, Indian conglomerates, banks and insurers, government departments, telecom operators and SMEs renting racks.
Market Drivers: Why Is India’s Data Center Spending Rising?
Three India-specific forces lift India Data Center Market spend to USD 33.54 billion in 2030. They are a tax rule that rewards global cloud exports from Indian halls, gigawatt-class hyperscale commitments, and state-subsidised AI compute.
Budget 2026-27 Tax Holiday Until 2047 for Cloud Exports From Indian Data Centres
The Union Budget presented on 1 February 2026 made notified foreign companies that sell cloud services through data centre capacity bought from an Indian operator eligible for a tax holiday from Tax Year 2026-27 to Tax Year 2046-47, and set a 15% safe-harbour margin on cost for related-party data centre services (Source: Press Information Bureau, Budget backgrounder, 14 February 2026). The rule favours colocation and wholesale operators, which DC Market Insights puts at 33.00% of 2025 market value, a share held through 2035. The same document put India’s cloud data centre capacity at about 1,280 MW, so the rule applies to a base that must grow several times over to serve export demand.
USD 32.5 Billion of Google and Microsoft Commitments for 2026-2030
Google said in October 2025 that it would spend about USD 15 billion over 2026-2030 on an AI hub in Visakhapatnam with gigawatt-scale data centre operations, built with AdaniConneX and Bharti Airtel (Source: Press Information Bureau, 14 October 2025). Microsoft committed USD 17.5 billion over calendar 2026 to 2029, its largest investment in Asia, and Amazon said it would invest more than USD 35 billion across its India businesses through 2030 (Source: Amazon, 10 December 2025). These named commitments cover about 29% of the USD 113.41 billion that DC Market Insights models for 2026-2030, which is why hyperscale and cloud self-build spend grows fastest among data center types, at 26.06% a year.
IndiaAI Mission: 38,000 GPUs at INR 65 per Hour
The IndiaAI Mission has an outlay of INR 10,371.92 crore over five years and had sanctioned 93.18 lakh GPU-hours by August 2026, according to the Press Information Bureau. Its compute portal lists 38,000 graphics processing units (GPUs) offered at about INR 65 per hour (Source: Press Information Bureau, October 2025), against more than INR 200 an hour on global clouds (Source: Press Information Bureau, February 2026). Yotta alone committed 9,216 GPUs, including 8,192 NVIDIA H100 units, to the Mission (Source: Yotta, February 2025). Subsidised hours turn GPU halls into bankable assets, which helps AI Workloads grow 29.83% a year, from 31.21% to 67.05% of spend by 2035.
Market Trends: How Is India’s Data Center Industry Changing?
The India Data Center Market is moving from 20 MW city halls to campuses above 100 MW. The build is also shifting from Mumbai to the south coast and from colocation rent to global capital, with AI workloads rising from 31.21% to 67.05% of spend by 2035.
Conglomerates Build Gigawatt Campuses: Reliance and Tata
Reliance Industries said at its 48th annual general meeting in August 2025 that work had begun on gigawatt-scale AI data centres in Jamnagar, and in June 2026 it agreed with Meta to build a 168 MW data centre there within two years (Source: Reliance Industries). Tata Consultancy Services (TCS) and TPG agreed in November 2025 to commit up to INR 18,000 crore to HyperVault, a platform for AI data centres above 1 GW (Source: Tata Group). DC Market Insights counts about 3,000 MW of disclosed new campus capacity, 84% of the 3,600 MW its model adds in 2026-2030.
Global Capital Re-Rates Indian Platforms
Bharti Airtel said in March 2026 that Alpha Wave Global and Carlyle would invest USD 1 billion in Nxtra, valuing it at about USD 3.1 billion, to take its roughly 300 MW to 1 GW (Source: Bharti Airtel). Canada Pension Plan Investment Board committed INR 7,000 crore to CtrlS, and Sify filed to list Sify Infinit Spaces with a fresh issue of up to INR 2,500 crore (Source: Sify Technologies 6-K, October 2025). Fresh equity of this size, about USD 2.1 billion, funds about 320 MW of halls at USD 6.49 million per MW in 2026, a DC Market Insights estimate.
Southern Coast Halls Follow Subsea Cables
Airtel is building a cable landing station in Visakhapatnam to host Google’s new subsea cables, and STT GDC India plans INR 4,200 crore of investment and about 130 MW of potential capacity in Chennai (Source: STT GDC India, February 2026). Southern India’s share rises from 32.00% to 42.00% by 2035 as a result.
Market Challenges: What Slows Data Center Projects in India?
Power price and the gap between announced and energised megawatts are the two limits on the India Data Center Market; DC Market Insights models a low case of USD 45.20 billion in 2035, 21% below base, if either bites.
Industrial Power at INR 10.78 per kWh in Maharashtra
The Maharashtra Electricity Regulatory Commission’s post-remand tariff order of 25 March 2026 set the HT-Industry average billing rate at INR 10.78 per kWh for FY26 and INR 9.97 for FY30, an 8% cut over the period (Source: MERC tariff order, Case 75 of 2025). At a PUE of 1.5, 1 MW of IT load uses 13.14 GWh a year, or about INR 14.2 crore (USD 1.63 million at INR 87 per USD), close to the USD 2.00 million a year that conventional IT costs per megawatt. Operators answer with green open-access power; the 2025 MERC order gave a 10% wheeling-charge discount for 100% green supply.
Official Capacity Figures Disagree by 540 MW
Government sources put installed capacity at about 960 MW (Press Information Bureau, India AI Stack note, 4 February 2026), about 1,280 MW of cloud capacity (Budget backgrounder, 14 February 2026) and about 1,500 MW by 2025 (MeitY reply to Parliament, March 2026). The 540 MW spread is worth about USD 3.4 billion of facilities at 2025 costs, so lenders discount pipelines that lack a grid connection date. DC Market Insights uses the 1,500 MW figure because it includes enterprise-grade colocation, and checks it against the 700 MW that STT GDC India and Nxtra publish.
Market Opportunities: Where Can Suppliers Win in India’s Data Center Market?
Cooling and power equipment for AI halls are the two largest India Data Center Market openings, worth USD 6.72 billion together in 2035.
Cooling Systems: USD 386.49 Million in 2025 to USD 2.34 Billion in 2035
Cooling grows 19.71% a year as its share of facility capex rises from 20% to 24% with liquid-cooled AI racks; India’s 30 to 45 degree Celsius summers make direct-to-chip cooling a design default for halls above 50 kW per rack, a DC Market Insights estimate.
Power Solutions: USD 869.60 Million in 2025 to USD 4.38 Billion in 2035
Switchgear, transformers, uninterruptible power supply (UPS) and on-site substations take 45% of facility capex. State dual-grid commitments, such as Uttar Pradesh’s promise of dual-grid supply to its first 3 data centre parks, cut the redundancy an operator must buy (Source: Invest UP, Data Centre Policy 2021).
Pricing: What Does a Data Center Megawatt Cost in India?
In the India Data Center Market, a new facility costs USD 6.34 million per MW of IT load in 2025. That rises to USD 8.11 million by 2035, about 41% below the USD 10.7 million used for the global market.
| Cost item | 2020 | 2025 | 2030 | 2035 |
|---|---|---|---|---|
| Facility per new MW (USD million) | 5.60 | 6.34 | 7.17 | 8.11 |
| AI IT fit-out per AI MW (USD million) | 25.00 | 25.00 | 22.50 | 20.00 |
| Conventional IT per operating MW-year (USD million) | 1.85 | 2.00 | 2.15 | 2.30 |
| New commercial IT load (MW) | 70 | 305 | 950 | 1,200 |
Public price anchors: the IndiaAI portal rents subsidised GPUs at about INR 65 per hour; Equinix spent over USD 95 million on its Mumbai MB3 site for more than 1,370 cabinets, about USD 69,000 per cabinet (Source: Equinix, April 2026); and Maharashtra industrial power averages INR 10.78 per kWh in FY26.
Standards and Regulation: Which Rules Shape India’s Data Center Market?
Four rule sets decide where the India Data Center Market’s USD 12.60 billion of 2026 spend lands. They are the tax holiday for cloud exports, the data protection law, state data centre policies and electricity tariffs.
- Digital Personal Data Protection Act 2023 and the DPDP Rules 2025, notified in November 2025 with an 18-month phased compliance timeline (Source: Press Information Bureau, 14 November 2025).
- Union Budget 2026-27: tax holiday to 2047 for notified foreign cloud providers using Indian data centre capacity, and a 15% cost-plus safe harbour (Source: Press Information Bureau backgrounder).
- Uttar Pradesh Data Centre Policy 2021: 250 MW and INR 20,000 crore target, 7% capital subsidy up to INR 10 crore and 100% electricity-duty exemption for 10 years (Source: Invest UP).
- Tamil Nadu Data Centre Policy 2021, which aims to make the state the first choice for data centres (Source: Government of Tamil Nadu).
- MERC multi-year tariff orders of 28 March 2025 and 25 March 2026, which place data centres in the industrial tariff category (Source: Maharashtra Electricity Regulatory Commission).
Market Segmentation: Which India Data Center Market Segment Leads?
IT Infrastructure leads the India Data Center Market with USD 7.10 billion, or 78.62% of 2025 value, and AI Workloads are the fastest segment at 29.83% a year.
By Component
| Component | 2025 (USD million) | Share 2025 | 2035 (USD million) | CAGR 2025-2035 |
|---|---|---|---|---|
| IT Infrastructure | 7,104.39 | 78.62% | 47,488.42 | 20.92% |
| Power Solutions | 869.60 | 9.62% | 4,379.65 | 17.55% |
| Cooling Systems | 386.49 | 4.28% | 2,335.81 | 19.71% |
| General Construction | 676.36 | 7.48% | 3,017.09 | 16.13% |
By Workload
| Workload | 2025 (USD million) | Share 2025 | 2035 (USD million) | CAGR 2025-2035 |
|---|---|---|---|---|
| AI Workloads | 2,820.30 | 31.21% | 38,366.19 | 29.83% |
| Conventional Workloads | 6,216.54 | 68.79% | 18,854.79 | 11.73% |
AI Workloads overtake conventional spend in 2028 in the base case, a DC Market Insights estimate.
By Data Center Type
| Data Center Type | 2025 (USD million) | Share 2025 | 2035 (USD million) | CAGR 2025-2035 |
|---|---|---|---|---|
| Hyperscale and Cloud Self-Build | 2,711.05 | 30.00% | 27,466.08 | 26.06% |
| Colocation and Wholesale | 2,982.15 | 33.00% | 18,882.93 | 20.27% |
| Enterprise and Government In-House | 3,343.63 | 37.00% | 10,871.99 | 12.51% |
By End User
| End User | 2025 (USD million) | Share 2025 | 2035 (USD million) | CAGR 2025-2035 |
|---|---|---|---|---|
| IT and Cloud Services | 3,976.21 | 44.00% | 32,043.75 | 23.20% |
| BFSI | 1,717.00 | 19.00% | 8,583.15 | 17.46% |
| Government and Public Sector | 1,084.42 | 12.00% | 5,722.10 | 18.10% |
| Telecom | 994.05 | 11.00% | 4,577.68 | 16.50% |
| Manufacturing and Others | 1,265.16 | 14.00% | 6,294.31 | 17.40% |
DC Exclusive: The India Gigawatt Campus Pipeline Tracker, 9 Projects and About 3,018 MW of Disclosed New Capacity
The India Gigawatt Campus Pipeline Tracker is a DC Market Insights model of the India Data Center Market pipeline, estimated from 9 inputs (company and government disclosures); it finds about 3,018 MW of new capacity with a stated size, 84% of the 3,600 MW that the model adds in 2026-2030.
| Project | Location | Disclosed size | Source |
|---|---|---|---|
| Google AI hub with AdaniConneX and Airtel | Visakhapatnam, Andhra Pradesh | Gigawatt scale (counted 1,000 MW); USD 15 billion 2026-2030 | Press Information Bureau, Oct 2025 |
| TCS and TPG HyperVault | Multiple sites | Above 1 GW (counted 1,000 MW); INR 18,000 crore | Tata Group, Nov 2025 |
| Nxtra by Airtel expansion | National | About 300 MW to 1 GW (counted 700 MW); USD 1 billion raise | Bharti Airtel, Mar 2026 |
| Reliance and Meta AI data centre | Jamnagar, Gujarat | 168 MW within two years | Reliance Industries, Jun 2026 |
| STT GDC India Chennai campuses | Chennai, Tamil Nadu | About 130 MW potential; INR 4,200 crore | STT GDC India, Feb 2026 |
| Digital Connexion MAA10 | Chennai, Tamil Nadu | 20 MW | Digital Connexion |
| Equinix MB3 | Mumbai, Maharashtra | 1,370+ cabinets; USD 95 million | Equinix, Apr 2026 |
| Microsoft India South Central region | Hyderabad, Telangana | Part of USD 17.5 billion 2026-2029 | Microsoft, Dec 2025 |
| Yotta GPU cloud for IndiaAI | Navi Mumbai, Maharashtra | 9,216 GPUs | Yotta, Feb 2025 |
Where an announcement says only “gigawatt scale” or “above 1 GW”, the tracker counts 1,000 MW; the Nxtra line counts only the 700 MW step from today’s base. Andhra Pradesh and Tamil Nadu hold 1,150 MW of the counted pipeline against 168 MW in Gujarat, which is the basis for the southern shift in the regional forecast.
Regional Insights: Where Are India’s Data Centers Built?
Western India leads the India Data Center Market with USD 4.34 billion, 48.00% of 2025 value. Southern India grows fastest at 23.58% a year to USD 24.03 billion in 2035, overtaking the west by 2033.
| Region | 2025 (USD million) | Share 2025 | 2035 (USD million) | CAGR 2025-2035 |
|---|---|---|---|---|
| Western India | 4,337.68 | 48.00% | 20,714.00 | 16.92% |
| Southern India | 2,891.79 | 32.00% | 24,032.82 | 23.58% |
| Northern India | 1,355.52 | 15.00% | 9,155.36 | 21.05% |
| Eastern India | 316.29 | 3.50% | 2,288.84 | 21.89% |
| Central India | 135.55 | 1.50% | 1,029.98 | 22.48% |
Western India
Mumbai and Navi Mumbai carry the subsea landings and financial-sector demand; Equinix’s MB3 brought its India cabinets to more than 4,725, and Reliance’s 168 MW Jamnagar build adds Gujarat to the region, which grows 16.92% a year.
Southern India
Chennai, Hyderabad, Bengaluru and Visakhapatnam add USD 21.14 billion of annual spend by 2035; Microsoft’s Hyderabad region and Google’s Visakhapatnam hub are the anchors.
Northern India
Noida and Greater Noida lead under Uttar Pradesh’s 250 MW policy target, lifting the region from USD 1.36 billion to USD 9.16 billion at 21.05% a year.
Eastern India
Kolkata and Bhubaneswar serve banking and government disaster-recovery demand, USD 316.29 million in 2025, growing 21.89% a year.
Central India
Madhya Pradesh and Chhattisgarh, with land and coal-region power, hold USD 135.55 million in 2025 and grow 22.48% a year from a small base.
State Analysis: Which Indian States Spend the Most on Data Centers?
In the India Data Center Market, Maharashtra is the largest state at USD 3.84 billion in 2025. Andhra Pradesh is the fastest large state at 41.27% a year, from USD 180.74 million to USD 5.72 billion in 2035 as the Visakhapatnam hub is energised.
| Rank | State | Region | 2025 (USD million) | 2035 (USD million) | CAGR |
|---|---|---|---|---|---|
| 1 | Maharashtra | Western India | 3,840.65 | 18,882.93 | 17.26% |
| 2 | Tamil Nadu | Southern India | 1,219.97 | 7,438.73 | 19.82% |
| 3 | Telangana | Southern India | 768.13 | 6,294.31 | 23.41% |
| 4 | Delhi NCT | Northern India | 542.21 | 2,574.94 | 16.86% |
| 5 | Karnataka | Southern India | 542.21 | 3,147.15 | 19.23% |
| 6 | Uttar Pradesh | Northern India | 497.03 | 4,291.57 | 24.06% |
| 7 | Gujarat | Western India | 361.47 | 1,716.63 | 16.86% |
| 8 | Haryana | Northern India | 271.10 | 2,002.73 | 22.14% |
| 9 | West Bengal | Eastern India | 225.92 | 1,487.75 | 20.74% |
| 10 | Andhra Pradesh | Southern India | 180.74 | 5,722.10 | 41.27% |
| 11 | Kerala | Southern India | 108.44 | 858.31 | 22.98% |
| 12 | Odisha | Eastern India | 63.26 | 572.21 | 24.64% |
Forecast Scenarios: How Big Could the India Data Center Market Be in 2035?
The India Data Center Market reaches USD 57.22 billion in 2035 in the base case. The range runs from USD 45.20 billion if grid connections slip to USD 69.81 billion if export-led cloud demand under the 2047 tax holiday arrives early.
| Scenario | 2035 (USD million) | CAGR 2025-2035 | Assumption |
|---|---|---|---|
| Low | 45,204.58 | 17.47% | New IT load averages 21% below base after 2027; AI share stays under 50% |
| Base | 57,220.99 | 20.27% | 950 MW new in 2030, 1,200 MW in 2035; AI share 55% to 62% |
| High | 69,809.61 | 22.68% | Export cloud and IndiaAI demand lift new build 22% above base |
Key Players: Who Builds and Runs India’s Data Centers?
STT GDC India and Nxtra by Airtel are the largest India Data Center Market operators, with over 400 MW and about 300 MW. Together they hold about 47% of India’s 1,500 MW base (DC Market Insights calculation from company disclosures and the MeitY figure).
- STT GDC India
- Nxtra by Airtel
- CtrlS Datacenters
- Yotta Data Services
- Sify Infinit Spaces
- AdaniConneX
- Reliance Industries (Jio)
- Tata Consultancy Services (HyperVault)
- NTT DATA India
- Equinix
- Digital Connexion
- Princeton Digital Group
- Amazon Web Services
- Microsoft
STT GDC India runs 30 data centres in 10 cities with over 400 MW of critical IT load (Source: STT GDC India, February 2026). Nxtra runs 14 core data centres and more than 120 edge sites and targets about 25% market share (Source: Bharti Airtel, March 2026). Equinix has invested more than USD 365 million in India (Source: Equinix, April 2026). Hyperscalers increasingly self-build: Google, Microsoft and Amazon together announced more than USD 67 billion of India investment for 2026-2030, part of it outside data centers.
Recent Developments: What Changed in India’s Data Center Market Since 2025?
Six dated events since October 2025 moved more than USD 35 billion of commitments into the India Data Center Market pipeline, by DC Market Insights count of the company and government statements below.
- In October 2025, Google announced about USD 15 billion for a Visakhapatnam AI hub over 2026-2030 (Source: Press Information Bureau).
- In November 2025, TCS and TPG agreed to commit up to INR 18,000 crore to HyperVault AI data centres (Source: Tata Group).
- In December 2025, Microsoft committed USD 17.5 billion to India for 2026-2029 (Source: Microsoft).
- In February 2026, the Union Budget 2026-27 gave foreign cloud providers using Indian data centres a tax holiday to 2047 (Source: Press Information Bureau).
- In March 2026, Bharti Airtel announced a USD 1 billion investment in Nxtra led by Alpha Wave Global and Carlyle (Source: Bharti Airtel).
- In June 2026, Reliance Industries and Meta agreed to build a 168 MW AI data centre in Jamnagar (Source: Reliance Industries).
Methodology: How the Model Values the India Data Center Market
DC Market Insights values the India Data Center Market at USD 9.04 billion in 2025 from capacity cohorts with 14 inputs and 25 sourced facts. New commercial IT load (305 MW in 2025, 950 MW in 2030, 1,200 MW in 2035) x facility cost per MW (USD 6.34 million in 2025) gives facility spend; new AI megawatts (25% of new load in 2025, 55% in 2030, 62% in 2035) x USD 25 million, plus a 20% yearly refresh of the installed AI base, gives AI IT; and 2,384 MW of operating conventional load, including about 1,270 MW of enterprise and government in-house rooms, x USD 2.00 million a year gives conventional IT. The total is USD 9.04 billion in 2025.
Three bound checks hold. Ceiling 1: the 5,105 MW of commercial capacity modelled for 2030 is 55% of the 9.2 GW that the India AI Stack note projects for 2030. Ceiling 2: the 2025 value is below the USD 14.25 billion India row of the global Data Center Market model. Floor: STT GDC India and Nxtra alone publish about 700 MW, 47% of the 1,505 MW base modelled for end-2025. The full method is described on the research methodology page; related figures appear in the Data Center Market, the Asia Pacific Data Center Market, the India Data Center Colocation Market and the India AI Data Center Market.
Source for capacity growth: Digital India, data centre capacity statement.
Table of contents
- 01Key Market Statistics
- 1.1Market Snapshot, 2025, 2026 and 2035
- 02Key Takeaways
- 2.1Four Takeaways With Figures
- 03India Data Center Market Summary
- 3.1Market Size Chart, 2020-2035
- 3.2Market Attribute Table
- 04What Does the India Data Center Market Include?
- 4.1Included
- 4.2Excluded
- 4.3How the Segments Fit Together
- 05Why Do India Data Center Market Estimates Differ?
- 5.1Scope Table: What Is In and Out
- 06Market Drivers
- 6.1Budget 2026-27 Tax Holiday Until 2047 for Cloud Exports From Indian Data Centres
- 6.2USD 32.5 Billion of Google and Microsoft Commitments for 2026-2030
- 6.3IndiaAI Mission: 38,000 GPUs at INR 65 per Hour
- 07Market Trends
- 7.1Conglomerates Build Gigawatt Campuses: Reliance and Tata
- 7.2Global Capital Re-Rates Indian Platforms
- 7.3Southern Coast Halls Follow Subsea Cables
- 08Market Challenges
- 8.1Industrial Power at INR 10.78 per kWh in Maharashtra
- 8.2Official Capacity Figures Disagree by 540 MW
- 09Market Opportunities
- 9.1Cooling Systems: USD 386.49 Million in 2025 to USD 2.34 Billion in 2035
- 9.2Power Solutions: USD 869.60 Million in 2025 to USD 4.38 Billion in 2035
- 10Pricing
- 10.1Cost per MW, 2020-2035
- 10.2Public Price Anchors
- 11Standards and Regulation
- 11.1DPDP Act and Rules
- 11.2Budget 2026-27 Tax Holiday
- 11.3State Data Centre Policies
- 11.4Electricity Tariff Orders
- 12Market Segmentation
- 12.1By Component: IT Infrastructure, Power Solutions, Cooling Systems, General Construction
- 12.2By Workload: AI Workloads, Conventional Workloads
- 12.3By Data Center Type: Hyperscale and Cloud Self-Build, Colocation and Wholesale, Enterprise and Government In-House
- 12.4By End User: IT and Cloud Services, BFSI, Government and Public Sector, Telecom, Manufacturing and Others
- 13DC Exclusive
- 13.1Pipeline Tracker Table: 9 Projects
- 14Regional Insights
- 14.1Western India
- 14.2Southern India
- 14.3Northern India
- 14.4Eastern India
- 14.5Central India
- 15State Analysis
- 15.1Maharashtra
- 15.2Tamil Nadu
- 15.3Telangana
- 15.4Delhi NCT
- 15.5Karnataka
- 15.6Uttar Pradesh
- 15.7Gujarat
- 15.8Haryana
- 15.9West Bengal
- 15.10Andhra Pradesh
- 15.11Kerala
- 15.12Odisha
- 16Forecast Scenarios
- 16.1Low Case
- 16.2Base Case
- 16.3High Case
- 17Key Players
- 17.1STT GDC India
- 17.2Nxtra by Airtel
- 17.3CtrlS Datacenters
- 17.4Yotta Data Services
- 17.5Sify Infinit Spaces
- 17.6AdaniConneX
- 17.7Reliance Industries (Jio)
- 17.8Tata Consultancy Services (HyperVault)
- 17.9NTT DATA India
- 17.10Equinix
- 17.11Digital Connexion
- 17.12Princeton Digital Group
- 17.13Amazon Web Services
- 17.14Microsoft
- 17.15Google
- 18Recent Developments
- 18.1October 2025 to June 2026 Events
- 19Methodology
- 19.1Capacity Cohort Model
- 19.2Bound Checks
- Fig. 1India Data Center Market Size, 2020-2035 (USD billion)
- Table 1India Data Center Market Attributes, 2025, 2026 and 2035
- Table 2Scope Table, In and Out of the Estimate
- Table 3Cost per MW, 2020-2035
- Table 4Market by Component, 2025 and 2035
- Table 5Market by Workload, 2025 and 2035
- Table 6Market by Data Center Type, 2025 and 2035
- Table 7Market by End User, 2025 and 2035
- Table 8India Gigawatt Campus Pipeline Tracker
- Table 9Market by Region, 2025 and 2035
- Table 10Top 12 States, 2025 and 2035
- Table 11Forecast Scenarios, 2035
About this report
Written by Amit Jain and reviewed by Deepti Agrawal, Senior Editor, Research. Figures are built top-down and bottom-up and reconciled before publication, with 2025 as the base year.
Read our methodologyHow we built this
- Historical period2020-2024
- Base year2025
- Forecast period2026-2035
- Sizing approachTop-down + bottom-up
Need more than the report?
Advisory on this market
Due diligence, site selection and market entry work, by the analysts who wrote this report.
See consulting servicesFrequently asked questions
USD 12.60 billion in 2026, up 39.44% from USD 9.04 billion in 2025, according to DC Market Insights estimates. The market is projected to reach USD 57.22 billion by 2035, a CAGR of 20.27% from 2025.
About 1,500 MW by 2025, up from about 375 MW in 2020, according to the Ministry of Electronics and Information Technology. DC Market Insights models 5,105 MW of commercial IT capacity by 2030 and 10,605 MW by 2035.
20.27% a year from 2025 to 2035, after 23.71% a year in 2020-2025. New IT load rises from 305 MW in 2025 to 1,200 MW in 2035, and AI’s share of new load rises from 25% to 62%.
AI Workloads, at 29.83% a year to USD 38.37 billion in 2035, overtaking conventional workloads in 2028. By data center type, hyperscale and cloud self-build grows fastest at 26.06%.
Maharashtra, with USD 3.84 billion or 42.50% of 2025 value, led by Mumbai and Navi Mumbai. Andhra Pradesh grows fastest at 41.27% a year as Google’s Visakhapatnam hub comes online.
Notified foreign cloud providers that serve customers through data centre capacity bought from Indian operators pay no tax on that income until Tax Year 2046-47, per the Press Information Bureau. It favours colocation spend, worth USD 2.98 billion in 2025.
USD 6.34 million per MW of IT load in 2025 for the facility, rising to USD 8.11 million by 2035, a DC Market Insights estimate. AI servers add about USD 25 million per AI megawatt.
STT GDC India, with over 400 MW, and Nxtra by Airtel, with about 300 MW, hold about 47% of the 1,500 MW national base. CtrlS, Yotta, Sify, AdaniConneX, Equinix and NTT DATA follow.
USD 57.22 billion in the base case, within a range of USD 45.20 billion to USD 69.81 billion, DC Market Insights estimates. The spread depends on grid connections and export cloud demand.
The USD 12.60 billion 2026 figure counts facilities and IT equipment only. Estimates that add cloud service revenue, IT outsourcing or electricity are larger, and colocation-only estimates are smaller.
About INR 14.2 crore a year for a 1 MW IT hall at a power usage effectiveness (PUE) of 1.5. This rests on the Maharashtra Electricity Regulatory Commission's HT-Industry average billing rate of INR 10.78 per kWh for FY26. Power cost is the largest operating risk.
31.21% of spend in 2025, rising to 67.05% in 2035. Each AI megawatt carries about USD 25 million of servers, against USD 2.00 million a year for a conventional megawatt, according to DC Market Insights estimates.
It covers USD 9.04 billion of 2025 spending on facilities and IT equipment: USD 1.93 billion of facilities, USD 2.34 billion of AI servers and USD 4.77 billion of conventional IT. Cloud service revenue, IT outsourcing, software, land and electricity are excluded.
Get this report
How do I get the full report?
Request a quote; we reply by email within one business day.
How and when will I receive the report?
By email, within 24-48 business hours of payment.
How can I pay?
Once you accept the quote, we email you a secure payment link.
Can I see a sample first?
Yes. Request a free sample and we will email it to you.
Can the report be tailored to my needs?
Yes. We can add countries, segments or data cuts. Talk to an analyst about the scope you need.
Can I get an invoice or pay against a purchase order?
Write to sales@dcmarketinsights.com and our team will help.