
Sweden Data Center Colocation Market Size, Share & Forecast to 2035
Market at a glance
The Sweden Data Center Colocation market was worth USD 367.3 million in 2025 and is forecast to reach USD 1,610.0 million by 2035, growing at a 15.9% CAGR.
 By Amit Jain, Senior Consultant, ICT & Emerging Technologies
 Reviewed by Deepti Agrawal
Last updated 29 Oct 2026
Base year 2025 PDF + Excel
Key findings
Power at Half the EU Price: EUR 0.0852 per kWh Against EUR 0.1596
Global Operators Buy Into the Nordics: USD 4 Billion for atNorth
A 5,500 MW Data-Center Queue at Svenska kraftnät
AI-Ready Wholesale Halls in Dalarna and Norrland
What is inside the report
- 01Introduction and Key Statistics
- 02Executive Summary
- 03Market Scope
- 04Market Drivers
- 05Market Trends
- 06Market Challenges
- 07Market Opportunities
- 08Pricing Analysis
- 09Standards and Regulation
- 10Market Segmentation
- 17chapters
- 2020-2024Historical period
- 2026-2035Forecast period
- 13Companies profiled
Segmentation
Companies profiled
- EcoDataCenter (owned 97.6% by Areim)
- Conapto
- Equinix
- Digital Realty
- Bahnhof
- atNorth (Equinix and CPP Investments)
- STACK Infrastructure
- GleSYS
- GlobalConnect
- Brookfield (Strängnäs)
- evroc
- Hydro66
- Magnora DC
Recent developments
Brookfield announced up to SEK 95 billion to expand its Strängnäs AI data center site from 300 MW to 750 MW (Source: Brookfield).
EcoDataCenter broke ground on its Borlänge campus with 250 MW at launch and raised SEK 6.7 billion of debt (Source: EcoDataCenter; Areim).
Sweden's cybersecurity act implementing NIS2 entered into force on 15 January (Source: Swedish Government).
atNorth announced SWE02, a 30 MW metro data center in Kista due in the fourth quarter of 2027 (Source: atNorth).
Conapto's 28 MW Stockholm 5 data center was fully contracted (Source: Conapto).
CPP Investments and Equinix completed the USD 4 billion acquisition of atNorth (Source: Equinix).
Full analysis
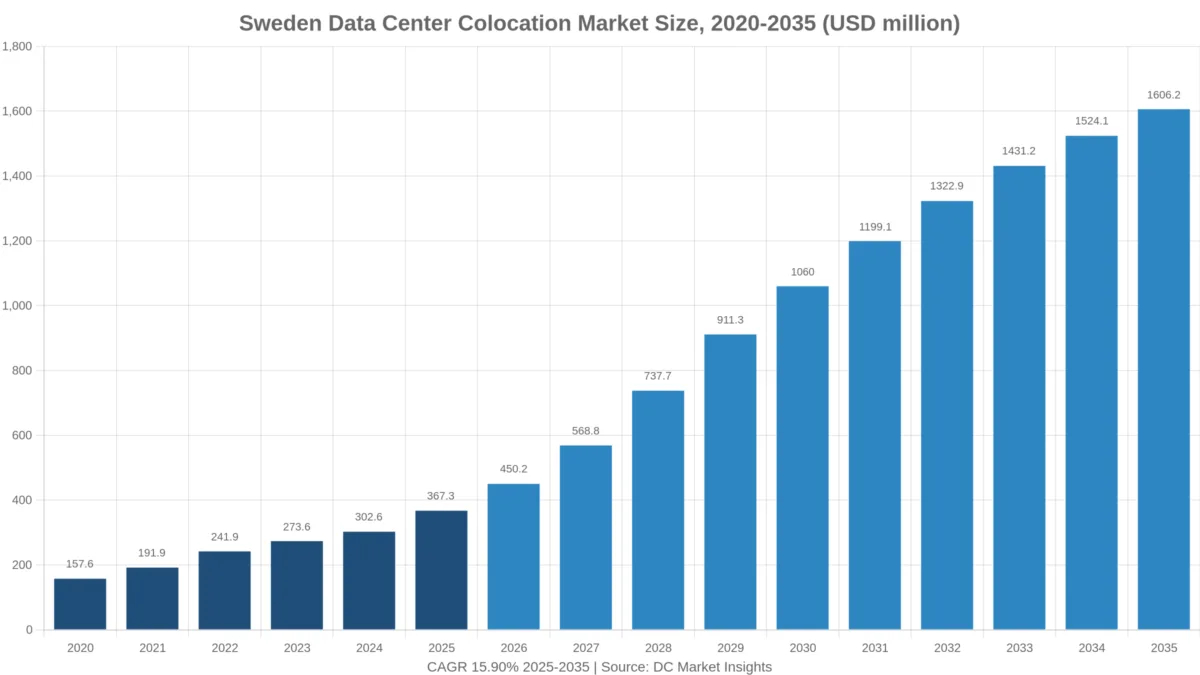
The Sweden Data Center Colocation Market is valued at USD 450.16 million in 2026 and is projected to reach USD 1.61 billion by 2035, up from USD 367.29 million in 2025, a CAGR of 15.90% from 2025 to 2035 (DC Market Insights estimate). Swedish colocation sells cheap, low-carbon power wrapped in a building, and two numbers set its margin: business electricity cost EUR 0.0852 per kWh excluding VAT in the second half of 2025, about half the EU average of EUR 0.1596, while data centers have paid the full energy tax since the 0.6 öre per kWh reduced rate was abolished on 1 July 2023 (Source: Eurostat; Swedish Ministry of Finance). The constraint is the grid, not demand: Svenska kraftnät counted 5,500 MW of large data-center connections in its queue in November 2025, 4,900 MW of it around Stockholm, Mälardalen, Uppsala and Gävleborg (Source: Svenska kraftnät). Sweden Data Center Colocation covers the rent, power and services that third-party operators bill for space in shared Swedish data centers; DC Market Insights builds it from 187.50 MW of average live colocation IT load in 2025, 82.00% sold, at about EUR 225 per kW per month for retail and EUR 118 for wholesale, all-in with power. Wholesale Colocation grows fastest at 21.54% a year as AI and high-performance computing (HPC) tenants take whole halls, and Northern Sweden is the fastest-growing region at 28.73% a year because its SE1 and SE2 price areas have spare grid capacity that Stockholm lacks.
Key Market Statistics: How Big Is the Sweden Data Center Colocation Market in 2026?
DC Market Insights values the Sweden data center colocation market at USD 450.16 million in 2026, 22.56% above 2025, as live colocation capacity rises from about 205 MW to 250 MW with Conapto’s Stockholm halls and EcoDataCenter’s Falun expansion.
- Market size 2025: USD 367.29 million
- Market size 2026: USD 450.16 million
- Market size 2030: USD 1.06 billion
- Market size 2035: USD 1.61 billion
- CAGR 2025-2035: 15.90% (low case 13.41%, high case 18.09%)
- Largest segment: Retail Colocation, 53.64% of 2025 revenue (USD 197.02 million)
- Fastest segment: Wholesale Colocation, 21.54% a year; racks above 30 kW grow 28.24% a year
- Leading region: Stockholm and Mälardalen, 60.00% of 2025 revenue; fastest-growing region: Northern Sweden, 28.73% a year
- Largest location: Kista and Akalla, USD 79.33 million in 2025
- Market leader: EcoDataCenter, about 19% of 2025 revenue (DC Market Insights estimate)
Key Takeaways: What Should a Swedish Colocation Buyer Know Before Signing?
DC Market Insights draws four takeaways from a Sweden data center colocation market that grows from USD 367.29 million in 2025 to USD 1.61 billion in 2035.
- Power is cheap but connections are scarce: Swedish business power cost EUR 0.0852 per kWh in 2025, yet 5,500 MW of data-center requests waited for Svenska kraftnät in November 2025, because transmission capacity around Stockholm is booked years ahead (Source: Eurostat; Svenska kraftnät).
- Electricity is only about 24% of a retail bill: at EUR 0.0852 per kWh, 70% load and a power usage effectiveness (PUE) of 1.25, power for one sold kW costs about EUR 54 a month against EUR 225 all-in (DC Market Insights estimate).
- Swedish demand is enterprise-deep: 72.0% of Swedish enterprises with 10 or more staff bought paid cloud services in 2025 against 52.7% in the EU, because Swedish banks, retailers and public bodies outsource early (Source: Eurostat).
- AI tenants changed the revenue mix: EcoDataCenter’s net revenue rose from SEK 297.1 million in 2024 to SEK 685.4 million in 2025, because HPC customers filled its Falun halls (Source: EcoDataCenter annual report 2025).
Sweden Colocation Summary: What Did Swedish Colocation Earn in 2025?
Swedish colocation operators earned USD 367.29 million in 2025. The Sweden Data Center Colocation Market size was valued at USD 157.62 million in 2020, reached USD 367.29 million in 2025, and is anticipated to reach USD 1.61 billion by 2035, at a CAGR of 15.90% during the forecast period. From 2020 to 2025 revenue grew 18.43% a year, helped by the 2022 power-price spike, which lifted all-in retail prices from about EUR 190 to EUR 250 per kW per month before they eased to EUR 225 in 2025, and by the July 2023 end of the data-center tax reduction, which operators passed through to tenants (DC Market Insights estimate; Source: Swedish Ministry of Finance).
| Report attribute | Details |
|---|---|
| Historical period | 2020-2024 |
| Base year | 2025 |
| Forecast period | 2026-2035 |
| Market size 2025 | USD 367.29 million |
| Market size 2026 | USD 450.16 million |
| CAGR 2025-2035 | 15.90% |
| Market size 2035 | USD 1.61 billion |
| Segments covered | Colocation Type, Enterprise Size, End User, Rack Density |
| Regions covered | Stockholm and Mälardalen, Dalarna and Gävleborg, Western Sweden, Southern Sweden, Northern Sweden |
Sweden data center colocation growth accelerates after 2026 because the capacity under construction is larger than the capacity in service: EcoDataCenter is building 24 MW in Borlänge, Conapto has 28 MW fully contracted in Stockholm, and atNorth plans 30 MW in Kista for the fourth quarter of 2027. DC Market Insights expects live colocation capacity to reach about 600 MW by 2030 and 885 MW by 2035.
What Does Sweden Data Center Colocation Cover, and Where Does It Stop?
Sweden data center colocation, at USD 367.29 million in 2025, counts only revenue that third-party operators bill tenants for space, power, cross-connects and on-site services in Swedish data centers.
Included
- Retail colocation: cabinets, cages and private suites under about 1 MW, billed per kW or per rack with power.
- Wholesale colocation: powered shells and whole halls of 1 MW or more leased to cloud, AI and HPC tenants.
- Interconnection and managed services: cross-connects, remote hands, migration and managed hosting sold by the colocation operator, 14% of retail revenue.
Excluded
- Hyperscale self-builds operated by their owners, such as Meta’s Luleå campus and the cloud regions that Microsoft and Amazon Web Services run in Sweden.
- Cloud services, enterprise-owned server rooms, construction spend and land sales.
- Electricity that a tenant buys directly from a utility outside the colocation contract.
How the Segments Fit Together
Every segment table, region and location in this Sweden data center colocation analysis sums to the same USD 367.29 million in 2025 and USD 1.61 billion in 2035. Colocation type follows the model build (retail plus wholesale plus services); enterprise size, end user and rack density split the same total.
Why Do Sweden Data Center Colocation Market Estimates Differ?
DC Market Insights puts the Sweden data center colocation market at USD 450.16 million in 2026; published estimates that count more than third-party colocation are larger. Broader definitions add the hyperscale campuses that Meta, Microsoft and Amazon Web Services own, the construction value of new halls such as Brookfield’s planned SEK 95 billion Strängnäs site, or cloud and hosting revenue that runs on top of the space. Some also count the whole Nordic market under a Swedish heading. Our earlier edition valued 2025 at USD 467.76 million on a top-down basis; this edition rebuilds the market from megawatts sold and prices per kW, which gives USD 367.29 million. Small and medium enterprises are inside the scope: they buy 28.00% of 2025 revenue, mostly retail racks in Stockholm, Gothenburg and Malmö. The Sweden Data Center Market report covers the wider market including self-builds.
| Element | Counted by DC Market Insights | Why |
|---|---|---|
| Retail and wholesale colocation | Yes, USD 339.71 million in 2025 | Revenue billed by third-party operators |
| Interconnection and managed services | Yes, USD 27.58 million in 2025 | Sold by the same operators in the same halls |
| Hyperscale self-builds | No | No colocation contract; owner-operated |
| Construction and land | No | Capital spend, not service revenue |
| Cloud services | No | Sold by cloud providers, not colocation operators |
Market Drivers: Why Is Swedish Colocation Demand Rising?
Three Sweden-specific drivers lift Swedish colocation revenue by USD 1.24 billion between 2025 and 2035.
Power at Half the EU Price: EUR 0.0852 per kWh Against EUR 0.1596
Swedish non-household electricity in the 2,000 to 19,999 MWh band cost EUR 0.0852 per kWh excluding VAT in the second half of 2025, against an EU average of EUR 0.1596 (Source: Eurostat). For a 1 MW wholesale tenant at 70% load that gap is worth about EUR 0.46 million a year before cooling overhead, which is why AI and HPC tenants, at 16.00% of 2025 Sweden colocation revenue, grow 24.22% a year to 2035.
EcoDataCenter’s Falun Halls Show AI Demand: 29 MW to 41 MW in One Year
EcoDataCenter lifted live capacity in Falun from 29 MW to 41 MW during 2025 and plans 65 MW once data centers E and F run, while its net revenue more than doubled to SEK 685.4 million (Source: EcoDataCenter annual report 2025). In the Sweden colocation model, Dalarna and Gävleborg rise from 20.00% of revenue in 2025 to about 22% in 2035.
Swedish Enterprises Already Outsource: 72.0% Buy Cloud
Eurostat counts 72.0% of Swedish enterprises with 10 or more staff buying paid cloud services in 2025 and 29.3% buying computing power, against EU averages of 52.7% and 14.9% (Source: Eurostat, 2025). Cloud and IT service providers that serve these firms are the largest Sweden colocation end user at 26.00% of 2025 revenue.
Market Trends: How Are Swedish Colocation Halls Changing?
Swedish colocation halls are moving to higher densities and larger leases: racks above 30 kW rise from 16.00% of 2025 revenue to about 44% in 2035.
Global Operators Buy Into the Nordics: USD 4 Billion for atNorth
CPP Investments and Equinix agreed on 27 February 2026 to buy atNorth for USD 4 billion of enterprise value, an operator with about 800 MW installed and in development across five Nordic countries, including Kista and Sollefteå sites in Sweden; the deal closed on 2 September 2026 (Source: Equinix). Ownership by larger groups shifts Swedish colocation toward wholesale halls sold to global cloud and AI tenants.
Campus Sites Move Out of Stockholm
New Swedish campuses sit where grid capacity exists: EcoDataCenter broke ground in Borlänge in September 2025 with 250 MW at launch and up to 600 MW, and Brookfield plans to take its Strängnäs site from 300 MW to 750 MW over 10 to 15 years (Source: EcoDataCenter; Brookfield, June 2025). Strängnäs and Västerås grow 23.23% a year in the Sweden colocation model.
Stockholm Metro Halls Fill Before Opening
Conapto’s 28 MW Stockholm 5 hall was fully contracted in April 2026, before completion, and Ellevio granted Conapto 8 MW more for Stockholm 4 South in October 2025 (Source: Conapto). Kista and Akalla stay the largest Sweden colocation location at 21.60% of 2025 revenue.
Market Challenges: What Holds Back Swedish Colocation?
Two constraints hold Swedish colocation growth to about 57 MW of new live capacity a year from 2030 to 2035.
A 5,500 MW Data-Center Queue at Svenska kraftnät
Large data centers in the Svenska kraftnät queue reached 5,500 MW in mid-November 2025, against a national peak load of 22,500 MW, and 4,900 MW of the requests sit in Mälardalen, Gävleborg, Uppsala and Stockholm (Source: Svenska kraftnät). Stockholm and Mälardalen’s share of Sweden colocation revenue therefore falls from 60.00% in 2025 to about 47% in 2035.
The Price-Area Gap: SE3 Power Costs Several Times SE1
The Swedish Energy Agency reported June 2025 spot averages of 3 öre per kWh in SE1 against 24 öre in SE3 and 44 öre in SE4 (Source: Swedish Energy Agency, June 2025). Halls in Stockholm (SE3) and Malmö (SE4) pay more for the same kW, so Southern Sweden grows only 13.81% a year, the slowest Swedish colocation region.
Market Opportunities: Where Can Swedish Colocation Operators Win?
Two openings add about USD 0.56 billion of Swedish colocation revenue between 2025 and 2035.
AI-Ready Wholesale Halls in Dalarna and Norrland
Wholesale Colocation rises from 38.85% of Swedish colocation revenue in 2025 to 62.50% in 2035; the Borlänge and Sollefteå campuses alone add about USD 0.33 billion of 2035 revenue in the Sweden colocation model (DC Market Insights estimate).
Regulated Buyers Who Need Swedish Halls
Sweden’s cybersecurity act (SFS 2025:1506), in force since 15 January 2026, covers medium-sized and larger providers of data-center services and their customers in banking, health and government (Source: Swedish Government). BFSI, government and healthcare tenants buy USD 102.84 million of Sweden colocation in 2025, rising to USD 337.31 million in 2035.
Pricing: How Much Does Colocation Cost per kW in Sweden?
Swedish colocation cost about EUR 225 per kW per month for retail and EUR 118 for wholesale in 2025, all-in with power (DC Market Insights estimate), below Western European metros because power is cheaper.
| Year | Retail (EUR per kW-month) | Wholesale (EUR per kW-month) | Retail (USD) | Wholesale (USD) |
|---|---|---|---|---|
| 2020 | EUR 190.00 | EUR 100.00 | USD 216.60 | USD 114.00 |
| 2025 | EUR 225.00 | EUR 118.00 | USD 254.25 | USD 133.34 |
| 2030 | EUR 242.39 | EUR 120.98 | USD 278.75 | USD 139.13 |
| 2035 | EUR 261.12 | EUR 124.03 | USD 300.29 | USD 142.63 |
Public anchors behind the Sweden colocation price model: business power at EUR 0.0852 per kWh excluding VAT in the second half of 2025 (Eurostat), the 2026 energy tax of 36.0 öre per kWh after 43.9 öre in 2025 (Skatteverket), and EcoDataCenter revenue of SEK 685.4 million on an average of about 35 MW live in Falun, roughly USD 165 per kW per month (DC Market Insights estimate). Prices rise 1.5% a year for retail and 0.5% for wholesale from 2026 because new wholesale halls compete on cheap northern power.
Standards and Regulation: Which Swedish Rules Apply to a Colocation Hall?
Four rules shape a Swedish colocation hall’s costs in 2026, led by an energy tax of 36.0 öre per kWh that data centers now pay in full.
- Energy tax: the reduced data-center rate of 0.6 öre per kWh was abolished from 1 July 2023, a change worth SEK 0.36 billion a year to the state (Source: Swedish Ministry of Finance); the standard rate is 36.0 öre per kWh in 2026 (Source: Skatteverket).
- Energy Efficiency Directive (EU) 2023/1791 and Delegated Regulation (EU) 2024/1364: data centers of 500 kW or more report energy and water use to an EU database; Sweden wrote the rules into law through Government Bill 2024/25:131, mostly from 1 July 2025 (Source: Swedish Government).
- Cybersecurity act (SFS 2025:1506): Sweden’s NIS2 law, in force 15 January 2026, covers data-center service providers (Source: Swedish Government).
- Design standards: EN 50600 / ISO/IEC 22237 for facility design and ISO/IEC 27001 for information security are the certifications Swedish tenants ask for in tenders.
Market Segmentation: Which Colocation Type Earns the Most in Sweden?
Retail Colocation earns the most in Sweden at USD 197.02 million in 2025, but Wholesale Colocation overtakes it in 2028 and reaches 62.50% of revenue in 2035.
By Colocation Type
| Colocation type | 2025 (USD million) | Share 2025 | 2035 (USD million) | CAGR 2025-2035 |
|---|---|---|---|---|
| Retail Colocation | 197.02 | 53.64% | 528.36 | 10.37% |
| Wholesale Colocation | 142.69 | 38.85% | 1,003.90 | 21.54% |
| Interconnection and Managed Services | 27.58 | 7.51% | 73.97 | 10.37% |
By Enterprise Size
| Enterprise size | 2025 (USD million) | Share 2025 | 2035 (USD million) | CAGR 2025-2035 |
|---|---|---|---|---|
| Large Enterprises | 264.45 | 72.00% | 1,188.61 | 16.22% |
| Small and Medium Enterprises | 102.84 | 28.00% | 417.62 | 15.04% |
By End User
| End user | 2025 (USD million) | Share 2025 | 2035 (USD million) | CAGR 2025-2035 |
|---|---|---|---|---|
| Cloud and IT Service Providers | 95.50 | 26.00% | 417.62 | 15.90% |
| AI and HPC Tenants | 58.77 | 16.00% | 513.99 | 24.22% |
| BFSI | 47.75 | 13.00% | 144.56 | 11.71% |
| Telecom and Media | 40.40 | 11.00% | 112.44 | 10.78% |
| Government and Public Sector | 36.73 | 10.00% | 112.44 | 11.84% |
| Manufacturing and Industry | 33.06 | 9.00% | 128.50 | 14.54% |
| Healthcare and Life Sciences | 18.36 | 5.00% | 80.31 | 15.90% |
| Others | 36.73 | 10.00% | 96.37 | 10.13% |
By Rack Density
| Rack density | 2025 (USD million) | Share 2025 | 2035 (USD million) | CAGR 2025-2035 |
|---|---|---|---|---|
| Up to 10 kW per Rack | 176.30 | 48.00% | 321.25 | 6.18% |
| 10 to 30 kW per Rack | 132.22 | 36.00% | 578.24 | 15.90% |
| Above 30 kW per Rack | 58.77 | 16.00% | 706.74 | 28.24% |
DC Exclusive: Swedish Colocation Pipeline Tracker, 11 Sites and About 1.38 GW Stated
The Swedish Colocation Pipeline Tracker is a DC Market Insights model built on 11 inputs: the named sites below state about 1,383 MW of current and planned capacity, of which the Sweden colocation forecast counts about 885 MW live by 2035, or 64%.
| Site | Region | Capacity | Status |
|---|---|---|---|
| EcoDataCenter Falun | Dalarna | 41 MW live end-2025, 65 MW after halls E and F | Live and expanding |
| EcoDataCenter Borlänge (B1, B2) | Dalarna | 24 MW under construction; campus 250 MW at launch, up to 600 MW | First hall early 2027 |
| Conapto Stockholm 4 South | Stockholm | 20 MW to 28 MW (+8 MW from Ellevio) | October 2025 |
| Conapto Stockholm 5 | Stockholm | 28 MW, fully contracted | April 2026 |
| atNorth SWE01 Kista | Stockholm | 12 MW | Live since March 2022 |
| atNorth SWE02 Kista | Stockholm | 30 MW | Q4 2027 |
| atNorth Sollefteå (SWE04) | Northern Sweden | 200 MW initial | Land secured December 2024 |
| Brookfield Strängnäs | Mälardalen | 300 MW to 750 MW, up to SEK 95 billion | 10-15 year build from 2025 |
| STACK STO01 | Stockholm | 18 MW | Live |
| GleSYS Falkenberg AI pod | Western Sweden | 2 MW, SEK 40 million | July 2025 |
| evroc Arlandastad | Stockholm | Land bought for SEK 25 million; no MW stated | February 2025 |
How to read the tracker: Stockholm sites are small (12 MW to 30 MW) and sell retail and metro wholesale; the large blocks sit in Dalarna, Mälardalen and Northern Sweden, where grid capacity exists, and they are why Wholesale Colocation grows 21.54% a year.
Regional Insights: Which Swedish Region Leads Colocation Revenue?
Stockholm and Mälardalen leads Swedish colocation with 60.00% of 2025 revenue, and Northern Sweden grows fastest at 28.73% a year.
Stockholm and Mälardalen
Stockholm and Mälardalen earns USD 220.37 million in 2025 Swedish colocation revenue and grows 13.10% a year; Bahnhof, the largest operator in central Stockholm, Equinix (SK1 Bromma, SK2 Sköndal, SK3 Spånga), Digital Realty (STO6 Kista) and Conapto anchor it, and Strängnäs adds wholesale capacity after 2028.
Dalarna and Gävleborg
Dalarna and Gävleborg earns USD 73.46 million in 2025 and grows 17.01% a year, led by EcoDataCenter’s 41 MW Falun site and its Borlänge campus, whose first hall is due in early 2027.
Western Sweden
Western Sweden earns USD 25.71 million in 2025 and grows 14.13% a year, from Gothenburg retail halls and GleSYS’s Falkenberg site, where a SEK 40 million, 2 MW AI pod was added in 2025.
Southern Sweden
Southern Sweden earns USD 22.04 million in 2025 and grows 13.81% a year; Malmö sits in price area SE4, where June 2025 spot power averaged 44 öre per kWh (Source: Swedish Energy Agency), and serves Øresund-region enterprises.
Northern Sweden
Northern Sweden earns USD 25.71 million in 2025 and grows fastest at 28.73% a year, because atNorth’s 200 MW Sollefteå site and Luleå and Boden halls sit in SE1 and SE2, where June 2025 spot power averaged 3 to 5 öre per kWh (Source: Swedish Energy Agency; atNorth).
Location Analysis: Which Swedish Locations Earn the Most Colocation Revenue?
Kista and Akalla earns the most Swedish colocation revenue at USD 79.33 million in 2025, and Borlänge grows fastest among locations above USD 5 million in 2025, at 36.25% a year.
| Rank | Location | Region | 2025 (USD million) | 2035 (USD million) | CAGR 2025-2035 |
|---|---|---|---|---|---|
| 1 | Kista and Akalla | Stockholm and Mälardalen | 79.33 | 226.48 | 11.06% |
| 2 | Falun | Dalarna and Gävleborg | 64.64 | 159.02 | 9.42% |
| 3 | Southern Stockholm (Sköndal and Haninge) | Stockholm and Mälardalen | 44.07 | 128.34 | 11.28% |
| 4 | Inner Stockholm | Stockholm and Mälardalen | 35.26 | 75.49 | 7.91% |
| 5 | Bromma and Spånga | Stockholm and Mälardalen | 30.85 | 75.49 | 9.36% |
| 6 | Strängnäs and Västerås | Stockholm and Mälardalen | 30.85 | 249.13 | 23.23% |
| 7 | Luleå and Boden | Northern Sweden | 23.14 | 176.69 | 22.54% |
| 8 | Malmö | Southern Sweden | 22.04 | 80.31 | 13.81% |
| 9 | Gothenburg | Western Sweden | 19.28 | 72.28 | 14.13% |
| 10 | Borlänge | Dalarna and Gävleborg | 8.81 | 194.35 | 36.25% |
| 11 | Falkenberg | Western Sweden | 6.43 | 24.09 | 14.13% |
| 12 | Sundsvall and Sollefteå | Northern Sweden | 2.57 | 144.56 | 49.62% |
Sundsvall and Sollefteå grows from a small base at 49.62% a year as atNorth’s Sollefteå site opens; Falun stays second in 2025 because EcoDataCenter’s halls are already full.
Forecast Scenarios: How Could Swedish Colocation Revenue Look in 2035?
Swedish colocation revenue reaches between USD 1.29 billion and USD 1.94 billion in 2035, with USD 1.61 billion as the DC Market Insights base case.
| Scenario | 2035 (USD million) | CAGR 2025-2035 | Assumption |
|---|---|---|---|
| Low | 1,293.27 | 13.41% | Grid delays cut new capacity after 2025 by 20%; prices 5% lower by 2035 |
| Base | 1,606.23 | 15.90% | 885 MW live by 2035, 85% sold |
| High | 1,936.23 | 18.09% | Strängnäs and Sollefteå run ahead: new capacity +18%, prices 6% higher |
Competitive Insights: Who Leads Sweden Data Center Colocation?
EcoDataCenter leads Swedish colocation with about 19% of 2025 revenue, and the top five operators hold about 56% (DC Market Insights estimate, based on published capacity and revenue).
- EcoDataCenter (owned 97.6% by Areim)
- Conapto
- Equinix
- Digital Realty
- Bahnhof
- atNorth (Equinix and CPP Investments)
- STACK Infrastructure
- GleSYS
- GlobalConnect
- Brookfield (Strängnäs)
- evroc
- Hydro66
- Magnora DC
Company facts: EcoDataCenter’s 2025 net revenue of SEK 685.4 million is about USD 69 million, or about 19% of the 2025 Sweden colocation market, after capital spending of SEK 2,566.5 million on halls in 2025 and SEK 6.7 billion of debt from Deutsche Bank in September 2025 (Source: EcoDataCenter; Areim). Conapto holds four Stockholm data centers and reports about SEK 710 million of contracted EBITDA after the Stockholm 5 lease (Source: Conapto, April 2026). Bahnhof’s group revenue was SEK 2,219 million in 2025 with SEK 678 million from business customers; it does not split out data-center revenue (Source: Bahnhof annual report 2025). For the wider picture see the Europe Data Center Colocation Market and the global Data Center Colocation Market.
Recent Developments: What Changed in Swedish Colocation Since 2025?
Six dated events since 2025 moved about 1 GW of Swedish colocation capacity into construction or new ownership.
- In June 2025, Brookfield announced up to SEK 95 billion to expand its Strängnäs AI data center site from 300 MW to 750 MW (Source: Brookfield).
- In September 2025, EcoDataCenter broke ground on its Borlänge campus with 250 MW at launch and raised SEK 6.7 billion of debt (Source: EcoDataCenter; Areim).
- In January 2026, Sweden’s cybersecurity act implementing NIS2 entered into force on 15 January (Source: Swedish Government).
- In January 2026, according to atNorth, its SWE02 metro data center in Kista will add 30 MW in the fourth quarter of 2027 (Source: atNorth).
- In April 2026, Conapto’s 28 MW Stockholm 5 data center was fully contracted (Source: Conapto).
- In September 2026, CPP Investments and Equinix completed the USD 4 billion acquisition of atNorth (Source: Equinix).
Methodology: How DC Market Insights Built the Swedish Colocation Model
DC Market Insights built the Sweden data center colocation model from 205 MW of live colocation IT capacity at the end of 2025, rising to 885 MW in 2035, with 82% to 85% sold, a wholesale share of 58% to 80% and prices of EUR 118 to EUR 261 per kW per month, converted at USD 1.13 per EUR in 2025 and USD 1.15 from 2026.
The 2025 receipt: 187.50 MW average live load × 82.00% sold = 153.75 MW billed; 58% wholesale at EUR 118 and 42% retail at EUR 225 per kW per month gives USD 142.69 million and USD 197.02 million, plus USD 27.58 million of services, for USD 367.29 million. Three bound checks hold the result:
- Ceiling 1: 153.75 MW billed at 70% load and PUE 1.25 uses about 1.18 TWh, about 28% of the 4.0 to 4.4 TWh that the Swedish Energy Agency’s RISE study forecast for all Swedish data centers in 2025.
- Ceiling 2: 885 MW live in 2035 equals 16% of the 5,500 MW of large data-center requests in the Svenska kraftnät queue in November 2025.
- Floor: EcoDataCenter alone earned about USD 69 million in 2025, 19% of the modelled market, and Conapto, Equinix, Digital Realty and Bahnhof each run several Stockholm halls.
The full approach is set out in the DC Market Insights research methodology. For AI-specific capacity see the Sweden AI Data Center Market.
Table of contents
- 01Introduction and Key Statistics
- 1.1Market Snapshot, 2025, 2026 and 2035
- 1.2Key Market Statistics
- 1.3Key Takeaways for Colocation Buyers
- 02Executive Summary
- 2.1Market Size, 2020-2035
- 2.2Report Attributes
- 03Market Scope
- 3.1Included
- 3.2Excluded
- 3.3How the Segments Fit Together
- 3.4Why Estimates Differ
- 04Market Drivers
- 4.1Power at Half the EU Price
- 4.2EcoDataCenter's Falun Halls and AI Demand
- 4.3Enterprise Cloud Adoption
- 05Market Trends
- 5.1Global Operators Buy Into the Nordics
- 5.2Campus Sites Move Out of Stockholm
- 5.3Stockholm Metro Halls Fill Before Opening
- 06Market Challenges
- 6.1Svenska kraftnät Data-Center Queue
- 6.2Price-Area Gap SE1 to SE4
- 07Market Opportunities
- 7.1AI-Ready Wholesale Halls in Dalarna and Norrland
- 7.2Regulated Buyers
- 08Pricing Analysis
- 8.1Retail and Wholesale Price per kW, 2020-2035
- 8.2Public Price Anchors
- 09Standards and Regulation
- 9.1Energy Tax
- 9.2Energy Efficiency Directive Reporting
- 9.3Cybersecurity Act (NIS2)
- 9.4Design Standards
- 10Market Segmentation
- 10.1By Colocation Type
- 10.2Retail Colocation
- 10.3Wholesale Colocation
- 10.4Interconnection and Managed Services
- 10.5By Enterprise Size
- 10.6Large Enterprises
- 10.7Small and Medium Enterprises
- 10.8By End User
- 10.9Cloud and IT Service Providers
- 10.10AI and HPC Tenants
- 10.11BFSI
- 10.12Telecom and Media
- 10.13Government and Public Sector
- 10.14Manufacturing and Industry
- 10.15Healthcare and Life Sciences
- 10.16Others
- 10.17By Rack Density
- 10.18Up to 10 kW per Rack
- 10.1910 to 30 kW per Rack
- 10.20Above 30 kW per Rack
- 11DC Exclusive: Swedish Colocation Pipeline Tracker
- 11.111 Named Sites and About 1.38 GW Stated
- 11.2How to Read the Tracker
- 12Regional Insights
- 12.1Stockholm and Mälardalen
- 12.2Dalarna and Gävleborg
- 12.3Western Sweden
- 12.4Southern Sweden
- 12.5Northern Sweden
- 13Location Analysis
- 13.1Kista and Akalla
- 13.2Falun
- 13.3Southern Stockholm (Sköndal and Haninge)
- 13.4Inner Stockholm
- 13.5Bromma and Spånga
- 13.6Strängnäs and Västerås
- 13.7Luleå and Boden
- 13.8Malmö
- 13.9Gothenburg
- 13.10Borlänge
- 13.11Falkenberg
- 13.12Sundsvall and Sollefteå
- 14Forecast Scenarios
- 14.1Low Case
- 14.2Base Case
- 14.3High Case
- 15Competitive Insights
- 15.1Market Concentration
- 15.2EcoDataCenter
- 15.3Conapto
- 15.4Equinix
- 15.5Digital Realty
- 15.6Bahnhof
- 15.7atNorth
- 15.8STACK Infrastructure
- 15.9GleSYS
- 15.10GlobalConnect
- 15.11Brookfield
- 15.12evroc
- 15.13Hydro66
- 15.14Magnora DC
- 16Recent Developments
- 16.12025 Developments
- 16.22026 Developments
- 17Research Methodology
- 17.1Model Build and 2025 Receipt
- 17.2Bound Checks
- Fig. 1Sweden Data Center Colocation Market Size, 2020-2035 (USD million)
- Table 1Report Attributes
- Table 2Scope of the Sweden Data Center Colocation Market
- Table 3Retail and Wholesale Colocation Prices, 2020-2035
- Table 4Market by Colocation Type, 2025 and 2035
- Table 5Market by Enterprise Size, 2025 and 2035
- Table 6Market by End User, 2025 and 2035
- Table 7Market by Rack Density, 2025 and 2035
- Table 8Swedish Colocation Pipeline Tracker
- Table 9Top 12 Swedish Colocation Locations, 2025 and 2035
- Table 10Forecast Scenarios, 2035
About this report
Written by Amit Jain and reviewed by Deepti Agrawal, Senior Editor, Research. Figures are built top-down and bottom-up and reconciled before publication, with 2025 as the base year.
Read our methodologyHow we built this
- Historical period2020-2024
- Base year2025
- Forecast period2026-2035
- Sizing approachTop-down + bottom-up
Need more than the report?
Advisory on this market
Due diligence, site selection and market entry work, by the analysts who wrote this report.
See consulting servicesFrequently asked questions
USD 450.16 million in 2026, up 22.56% from USD 367.29 million in 2025, according to DC Market Insights estimates. The market is projected to reach USD 1.61 billion by 2035, a CAGR of 15.90% from 2025.
15.90% a year from 2025 to 2035, after 18.43% a year in 2020-2025, as live colocation capacity rises from about 205 MW to 885 MW with new halls in Stockholm, Borlänge, Strängnäs and Sollefteå.
About EUR 225 per kW per month for retail and EUR 118 for wholesale in 2025, all-in with power (DC Market Insights estimate). Power alone is about EUR 54 per sold kW at EUR 0.0852 per kWh.
Wholesale Colocation, at 21.54% a year from USD 142.69 million in 2025 to USD 1.00 billion in 2035, as AI and HPC tenants lease whole halls.
Northern Sweden, at 28.73% a year to USD 321.25 million by 2035, because price areas SE1 and SE2 have cheap power and spare grid capacity for sites such as atNorth’s 200 MW Sollefteå campus.
EcoDataCenter, Conapto, Equinix, Digital Realty and Bahnhof hold about 56% of 2025 revenue (DC Market Insights estimate). atNorth, STACK Infrastructure, GleSYS and GlobalConnect follow.
About 205 MW of live colocation IT capacity at the end of 2025 and 250 MW by the end of 2026, by DC Market Insights estimates, with about 1.38 GW stated across 11 named current and planned sites.
5,500 MW of large data-center connections waited in the Svenska kraftnät queue in November 2025, 4,900 MW of it around Stockholm and Mälardalen, so new campuses move to Dalarna and Northern Sweden.
USD 367.29 million in 2025 counts only space sold by third-party operators. The Sweden data center market also counts hyperscale self-builds such as Meta’s Luleå campus and enterprise data centers.
USD 450.16 million in 2026 is the DC Market Insights figure for third-party colocation only. Estimates that add hyperscale self-builds, construction spend or cloud revenue are several times larger.
Get this report
How do I get the full report?
Request a quote; we reply by email within one business day.
How and when will I receive the report?
By email, within 24–48 business hours of payment.
How can I pay?
Once you accept the quote, we email you a secure payment link.
Can I see a sample first?
Yes. Request a free sample and we will email it to you.
Can the report be tailored to my needs?
Yes. We can add countries, segments or data cuts. Talk to an analyst about the scope you need.
Can I get an invoice or pay against a purchase order?
Write to sales@dcmarketinsights.com and our team will help.