
Taiwan AI Data Center Market Size, Share & Forecast to 2035
Market at a glance
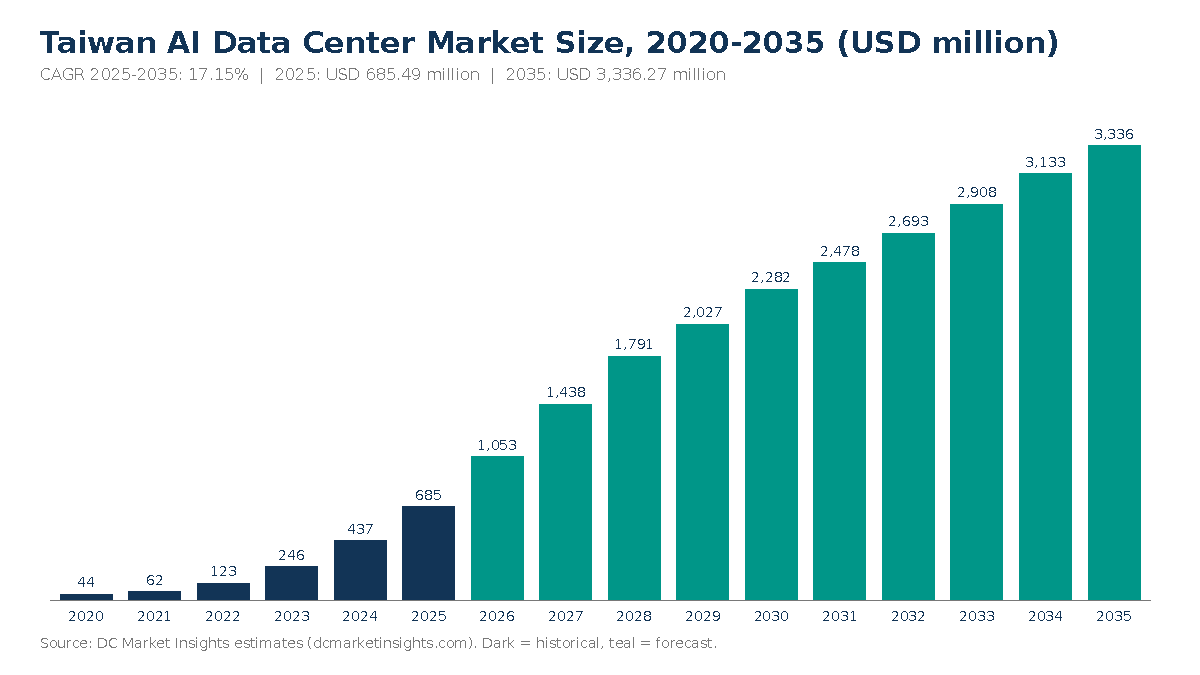
The Taiwan AI Data Center market was worth USD 685.5 million in 2025 and is forecast to reach USD 3,340.0 million by 2035, growing at a 17.15% CAGR.
 By Amit Jain, Senior Consultant, ICT & Emerging Technologies
 Reviewed by Deepti Agrawal
Last updated 18 Oct 2026
Base year 2025 PDF + Excel
What is inside the report
- 01Introduction
- 02Research Methodology
- 03Executive Summary
- 04Market Dynamics
- 05Pricing Analysis
- 06Standards and Regulation
- 07Market Segmentation by Component
- 08Market Segmentation by Project Type
- 09Market Segmentation by Workload
- 10Market Segmentation by Data Center Type
- 16chapters
- 2020-2024Historical period
- 2026-2035Forecast period
- —Companies profiled
Segmentation
Full analysis
The Taiwan AI Data Center Market is valued at USD 1.05 billion in 2026 and is projected to reach USD 3.34 billion by 2035, up from USD 685.49 million in 2025, a CAGR of 17.15% from 2025 to 2035 (DC Market Insights estimate). Power, not chips, sets the pace here: since 2024 requests above 5 megawatts (MW) north of Taoyuan have waited behind grid bottlenecks that the Ministry of Economic Affairs (MOEA) acknowledged in October 2024, while 79 AI data center power applications for about 4,758 MW were on file with Taiwan Power Company (Taipower) by November 2025, only 40 of them (3,033 MW) approved (Source: MOEA; Taipower figures reported in October 2026). The Taiwan AI Data Center Market covers the facility infrastructure built and operated for artificial intelligence (AI) workloads in Taiwan: electrical systems, cooling, the building shell and fit-out, the AI network fabric, and operations services and software; graphics processing unit (GPU) servers are excluded. The 2025 build receipt is 42.75 MW of new AI IT capacity (45% of the 95 MW completed in Taiwan) × USD 14.00 million per AI MW = USD 598.50 million, plus 12 MW of hall retrofits × USD 4.50 million = USD 54.00 million, plus USD 0.40 million of services on each of 82.5 MW of installed AI capacity = USD 32.99 million. Operations Services and Software is the fastest-growing segment at 34.40% a year, and Southern Taiwan is the fastest-growing region at 22.39% a year because Tainan and Kaohsiung have grid headroom that Taoyuan lacks.
Key Market Statistics: How Big Is the Taiwan AI Data Center Market in 2026?
DC Market Insights values the Taiwan AI Data Center Market at USD 1.05 billion in 2026, 53.59% above 2025. Growth comes as new AI IT capacity rises from 42.75 MW to 65.00 MW.
- Market size 2025: USD 685.49 million
- Market size 2026: USD 1.05 billion
- Market size 2030: USD 2.28 billion
- Market size 2035: USD 3.34 billion
- CAGR 2025-2035: 17.15% (low case 13.24%, high case 19.65%)
- Largest component: Electrical Infrastructure, 33.55% of 2025 spend (USD 229.95 million)
- Fastest component: Operations Services and Software, 34.40% a year; fastest workload: AI Inference, 24.32% a year
- Leading region: Northern Taiwan, 60% of 2025 spend; fastest-growing region: Southern Taiwan, 22.39% a year
- Largest city: Taoyuan City, USD 143.95 million in 2025
- Market leader: Delta Electronics, about 14% of 2025 equipment and services value (DC Market Insights estimate)
Key Takeaways: What Should Buyers of Taiwan AI Data Center Capacity Know?
DC Market Insights draws four takeaways from a market that grows from USD 685.49 million in 2025 to USD 3.34 billion in 2035.
- Grid access decides location: Southern Taiwan rises from 20% to 31% of spend by 2035 because new northern loads above 5 MW wait for Taipower capacity.
- An AI hall costs USD 14.00 million per MW of IT load before servers in 2025, about 44% more than a conventional hall, because power trains and liquid cooling are heavier.
- Inference overtakes training around 2031, lifting AI Inference from 32% to 58% of spend, because enterprise and sovereign models move into production.
- Services become a business in their own right: operations spend grows from USD 32.99 million to USD 634.49 million as the installed AI base passes 1,400 MW.
Taiwan AI Data Center Market Summary: How Much Did Taiwan Spend on AI Data Center Facilities in 2025?
Taiwan spent USD 685.49 million on AI data center facility infrastructure in 2025. The Taiwan AI Data Center Market size was valued at USD 43.58 million in 2020, reached USD 685.49 million in 2025, and is anticipated to reach USD 3.34 billion by 2035, at a CAGR of 17.15% during the forecast period. From 2020 to 2025 the market grew 73.52% a year from a small base, as the AI share of new Taiwanese capacity rose from 8% to 45% and the first GPU halls opened in Taipei, Kaohsiung and Tainan.
| Report attribute | Details |
|---|---|
| Historical period | 2020-2024 |
| Base year | 2025 |
| Forecast period | 2026-2035 |
| Market size 2025 | USD 685.49 million |
| Market size 2026 | USD 1.05 billion |
| CAGR 2025-2035 | 17.15% |
| Market size 2035 | USD 3.34 billion |
| Segments covered | Component, Project Type, Workload, Data Center Type |
| Regions covered | Northern, Central, Southern, Eastern Taiwan and Offshore Islands; 12 cities and counties |
Growth slows from 53.59% in 2026 to 6.50% by 2035 because annual AI completions level off near 155 MW while the price per MW rises 2% a year; the installed AI base still climbs from 136 MW at the end of 2025 to about 1,415 MW in 2035, so services carry the later years. DC Market Insights estimates that the AI-hall facility content in 2025 (USD 570.71 million at USD 13.35 million per MW) equals 46% of the Taiwan Data Center Infrastructure Market for the same year.
What Is the Taiwan AI Data Center Market, and Where Does It Stop?
The Taiwan AI Data Center Market is USD 685.49 million (2025) of facility spend on halls built for AI accelerators. Those halls run racks of 40 kilowatts (kW) to 200 kW each.
Included
Medium-voltage switchgear, transformers, uninterruptible power supply (UPS) systems and busways sized for AI loads; chillers, coolant distribution units (CDUs), direct-to-chip loops and rear-door heat exchangers; reinforced floors, white-space fit-out and racks; the AI network fabric (structured optical cabling, cable trays and spine-room build); retrofits that convert existing halls for liquid cooling; and operations services and monitoring software on installed AI halls.
Excluded
GPU servers, storage and switches, AI server manufacturing for export by original design manufacturers (ODMs), land, electricity bills, Taipower transmission works, colocation rent, and GPU-as-a-service or cloud revenue. Servers that Taiwanese factories build and ship abroad are manufacturing output, not spend inside Taiwan’s data centers. All data center spend in Taiwan, AI and conventional, is sized in the Taiwan Data Center Market; the worldwide total is in the Data Center Market (not restated here).
How the segments fit together
Every year the four component lines sum to the total, and so do the three project types, the two workloads, the four data center types and the four regions: in 2025, USD 598.50 million of new AI halls + USD 54.00 million of retrofits + USD 32.99 million of operations = USD 685.49 million.
Why Do Taiwan AI Data Center Market Estimates Differ?
Estimates differ because the 2026 figure of USD 1.05 billion counts only the facility layer; an estimate that adds GPU servers would be roughly ten times larger.
The previous edition of this page counted only a narrow set of dedicated AI sites. Broader definitions add accelerator servers, AI server exports by Taiwanese ODMs, GPU cloud subscriptions and power purchase costs. DC Market Insights keeps those out so the figure can be compared with facility budgets and with the Asia Pacific AI Data Center Market, which uses the same boundary.
| Element | Included in DC Market Insights scope | Why |
|---|---|---|
| Electrical, cooling, shell and fabric | Yes, USD 652.50 million (2025, new halls and retrofits) | Physical build of the AI hall |
| Operations services and software | Yes, USD 32.99 million (2025) | Recurring spend tied to installed AI MW |
| GPU servers and storage | No | IT equipment, priced per accelerator |
| AI server exports | No | Manufacturing output, not data center spend |
| Electricity and colocation rent | No | Operating payments to utilities and landlords |
In-scope buyers include hyperscale cloud providers, colocation operators, the National Center for High-performance Computing (NCHC) and other government sponsors, semiconductor and electronics manufacturers running private AI clusters, and small and medium-sized enterprises (SMEs) that rent AI racks through colocation.
Why Is Taiwan AI Data Center Spending Rising So Fast?
Three buyer groups lift Taiwan AI data center spend by 53.59% in 2026. Hyperscale cloud regions, government-backed sovereign compute and high-density colocation together add 65.00 MW of AI IT capacity that year (DC Market Insights estimate).
AWS, Google and Microsoft commit billions to Taiwanese cloud regions
Amazon launched the Amazon Web Services (AWS) Asia Pacific (Taipei) Region in June 2025 and said it plans to invest more than USD 5 billion in Taiwan data centers (Source: Amazon). According to Google, its Changhua County campus has absorbed more than USD 1.6 billion since 2011, and Microsoft reported building its first Taiwan data centers in Taoyuan in April 2025. DC Market Insights estimates that hyperscale and cloud halls took 42% of Taiwan AI Data Center Market spend in 2025 (USD 287.91 million) and reach 50% by 2035, the fastest-growing data center type at 19.21% a year, because each region adds AI availability zones on top of conventional capacity.
Sovereign compute: the NCHC Tainan center and a 10,000-GPU AI factory
The National Science and Technology Council (NSTC) opened the NCHC Cloud Computing Center at the Southern Taiwan Science Park in December 2025 with 15 MW of installed power (Source: NSTC). In May 2025 Foxconn (Hon Hai Precision Industry), NVIDIA Corporation (NVIDIA) and the Taiwan government announced an AI factory with 10,000 NVIDIA Blackwell GPUs, according to NVIDIA. DC Market Insights counts sovereign and research centers at USD 123.39 million in 2025, 18% of the market, and expects their share to ease to 12% by 2035 as commercial halls scale faster than public budgets.
Racks of 100 kW and more raise the price of every megawatt
Chief Telecom designed its LY2 AI data center for 1,800 racks at 10 kW to 200 kW per cabinet with 20 MW from dual Taipower stations, according to the company (Source: Chief Telecom). GMI Cloud’s USD 500 million AI factory, announced in February 2026, puts 7,000 NVIDIA Blackwell GPUs into 96 high-density racks drawing 16 MW, or about 167 kW per rack, according to the company. Densities of that order need direct-to-chip cooling and heavier power trains, which is why DC Market Insights prices an AI hall at USD 14.00 million per MW of IT load in 2025 against USD 9.75 million for a conventional hall, a 44% premium that rises to USD 17.07 million per AI MW by 2035.
How Are Taiwan AI Data Center Designs Changing?
Three design shifts lift Southern Taiwan to 31% of Taiwan AI data center spend by 2035. Halls migrate south, cooling becomes modular and liquid, and campuses contract clean firm power; together they lift Southern Taiwan from USD 137.10 million in 2025 to 31% of spend by 2035.
Kaohsiung and Tainan host the next AI halls
Foxconn opened an advanced computing center in Kaohsiung with 64 racks and 4,608 GPUs in June 2024, according to Foxconn, and the NCHC Tainan center followed in December 2025. DC Market Insights models Kaohsiung City as the fastest-growing city at 23.29% a year, from USD 61.69 million in 2025 to USD 500.44 million in 2035, because southern substations still accept loads that Taoyuan cannot.
Foxconn and TECO standardise modular AI power and cooling
Foxconn and TECO Electric and Machinery (TECO) formed an AI data center alliance through a share swap in July 2025 to push standardised, modular builds, according to TECO. DC Market Insights estimates that Cooling Infrastructure took 32.79% of Taiwan AI data center spend in 2025 (USD 224.78 million), with retrofit work weighted 60% to cooling.
Geothermal and other firm clean power enter AI campus contracts
Google signed Taiwan’s first corporate geothermal agreement in April 2025 for an initial 10 MW from Baseload Capital, according to Google. Contracts like this do not enter the market value directly, but they decide which sites get permits under the MOEA efficiency rules that took effect for loads of 5 MW and more.
What Holds Back Taiwan AI Data Center Build-Outs?
Grid access is the main restraint, with 64% of Taiwan AI data center power requests approved. Only 3,033 MW of the 4,758 MW filed with Taipower had been approved by November 2025, according to Taipower figures reported in October 2026.
Taipower capacity north of Taoyuan
The MOEA projected in July 2024 that AI electricity demand in Taiwan would rise from 0.24 gigawatts (GW) in 2023 to 2.24 GW in 2028 (Source: MOEA), and in October 2024 it acknowledged grid bottlenecks in several areas north of Taoyuan. DC Market Insights therefore caps new AI completions at 125 MW in 2026 and 195 MW in 2030; in the low case, a 25% shortfall in completions from 2027 cuts the 2035 market to USD 2.38 billion.
Tariffs and subsea cable risk
According to the MOEA tariff decision of March 2024, internet data centers using 50 gigawatt-hours (GWh) or more a year pay 15% to 25% more, and the October 2024 decision raised industrial rates 12.5% to an average NT$4.29 per kilowatt-hour (kWh). The Ministry of Digital Affairs (MODA) recorded seven submarine cable incidents in 2025, three of them (42.9%) caused by anchor dragging, according to MODA. Both raise the cost of running an AI hall in Taiwan and push buyers toward PUE-efficient liquid designs.
Where Can Suppliers Win in Taiwan AI Data Centers?
Liquid-cooling retrofits worth USD 445.42 million over 2026-2030 are the largest Taiwan AI data center opening outside new halls. Operations services come next and reach 19.02% of spend in 2035 (DC Market Insights estimate).
Liquid-cooling retrofits of existing Taipei and Taoyuan halls
With new northern loads queued, operators convert existing halls instead: DC Market Insights models 93 MW of retrofits in 2026-2030 at USD 4.50 million to USD 4.97 million per MW, worth USD 445.42 million, most of it CDUs, rear-door heat exchangers and upgraded switchgear.
Operations, monitoring and lifecycle services for AI halls
Each installed AI MW needs USD 0.40 million of services and software a year in 2025, rising to USD 0.50 million by 2035, so operations spend reaches USD 634.49 million in 2035 on about 1,415 MW of installed AI capacity, growing 34.40% a year.
What Does an AI Data Center Megawatt Cost in Taiwan?
A Taiwan AI data center hall costs USD 14.00 million per MW of IT load in 2025, before servers. DC Market Insights builds that estimate from USD 5.00 million electrical, USD 4.50 million cooling, USD 3.85 million shell, fit-out and racks, and USD 0.65 million AI network fabric.
| Price point (USD million) | 2020 | 2025 | 2030 | 2035 |
|---|---|---|---|---|
| New AI hall, per MW of IT load | 12.68 | 14.00 | 15.46 | 17.07 |
| Retrofit of an existing hall, per MW | 4.08 | 4.50 | 4.97 | 5.49 |
| Operations services and software, per installed AI MW a year | 0.30 | 0.40 | 0.45 | 0.50 |
Public anchors bracket these figures: GMI Cloud’s USD 500 million for 16 MW equals USD 31.25 million per MW including GPUs, so the facility layer is under half of an all-in AI hall budget; the industrial power price of NT$4.29 per kWh after October 2024 sets the running cost that efficient cooling has to beat.
Which Rules and Policies Govern Taiwan AI Data Centers?
Taiwan AI data center sites of 5 MW or more face a PUE cap of 1.3 or 1.4 since December 2025. Every Taiwanese data center with contracted capacity of 5 MW or more needs an approved Energy Utilization Manual and must meet a power usage effectiveness (PUE) cap of 1.3 for hyperscale or 1.4 for colocation sites (Source: MOEA).
The rule adds roughly USD 0.30 million per MW of cooling and controls content to a typical AI hall (DC Market Insights estimate). Other rules that shape the market: the MOEA tariff decisions of March 2024 (+15% to 25% for data centers using 50 GWh or more) and September 2024 (+12.5% industrial rates); the Taiwan Grid Resilience Enhancement Construction Plan, a ten-year programme from 2022 with NT$564.5 billion of planned investment, according to the International Energy Agency (IEA) policy database; and MODA’s subsea cable protection measures after the 2025 incidents. Building and fire codes follow the Ministry of the Interior, and Uptime Institute Tier ratings and American Society of Heating, Refrigerating and Air-Conditioning Engineers (ASHRAE) thermal guidelines are the design references most AI halls cite.
Which Segment Carries the Most Value in the Taiwan AI Data Center Market, and Which Grows Fastest?
Electrical Infrastructure carries the most value at USD 229.95 million (33.55%) in 2025. Operations Services and Software is the fastest-growing segment at 34.40% a year because the installed AI base grows tenfold by 2035 (DC Market Insights estimate).
Taiwan AI Data Center Market by Component
Power trains lead because AI racks above 100 kW need more switchgear, UPS and busway capacity per MW than any other layer.
| Component | 2025 (USD million) | Share 2025 | 2035 (USD million) | CAGR 2025-2035 |
|---|---|---|---|---|
| Electrical Infrastructure | 229.95 | 33.55% | 961.79 | 15.38% |
| Cooling Infrastructure | 224.78 | 32.79% | 883.71 | 14.67% |
| Building Shell and Fit-Out | 167.29 | 24.40% | 730.65 | 15.88% |
| AI Network Fabric | 30.49 | 4.45% | 125.64 | 15.21% |
| Operations Services and Software | 32.99 | 4.81% | 634.49 | 34.40% |
Taiwan AI Data Center Market by Project Type
New AI halls take 87.31% of 2025 spend; retrofits stay near USD 55 million a year as conversions of older northern halls peak in 2029-2030 and then taper.
| Project type | 2025 (USD million) | Share 2025 | 2035 (USD million) | CAGR 2025-2035 |
|---|---|---|---|---|
| New AI Halls | 598.50 | 87.31% | 2,646.92 | 16.03% |
| Retrofits of Existing Halls | 54.00 | 7.88% | 54.85 | 0.16% |
| Operations and Lifecycle Services | 32.99 | 4.81% | 634.49 | 34.40% |
Taiwan AI Data Center Market by Workload
AI Inference grows 24.32% a year, from 32% to 58% of spend, as Taiwanese manufacturers and banks put trained models into production close to their users.
| Workload | 2025 (USD million) | Share 2025 | 2035 (USD million) | CAGR 2025-2035 |
|---|---|---|---|---|
| AI Training | 466.13 | 68.00% | 1,401.23 | 11.63% |
| AI Inference | 219.36 | 32.00% | 1,935.04 | 24.32% |
Taiwan AI Data Center Market by Data Center Type
Hyperscale and cloud halls lead the Taiwan AI data center build with 42% of 2025 spend; colocation AI halls such as Chief Telecom LY2 follow with 30%.
| Data center type | 2025 (USD million) | Share 2025 | 2035 (USD million) | CAGR 2025-2035 |
|---|---|---|---|---|
| Hyperscale and Cloud Data Centers | 287.91 | 42.00% | 1,668.13 | 19.21% |
| Colocation AI Data Centers | 205.65 | 30.00% | 934.16 | 16.34% |
| Sovereign and Research AI Centers | 123.39 | 18.00% | 400.35 | 12.49% |
| Enterprise and Edge AI Data Centers | 68.55 | 10.00% | 333.63 | 17.15% |
DC Exclusive: The Taiwan AI Power and Permit Timeline, 10 Decisions and Projects, 2024-2026
Ten decisions and projects shaped 135.75 MW of Taiwan AI data center capacity in 2024-2026. DC Market Insights built this timeline from those 10 inputs to show how 135.75 MW of AI IT capacity completed in 2024-2026 was shaped by tariff, grid and efficiency decisions; the MW and cost effects in the last column are modelled DC Market Insights estimates based on those 10 inputs.
| Date | Decision or project | Figure | Effect on AI facility spend (DC Market Insights estimate) |
|---|---|---|---|
| March 2024 | MOEA tariff decision for internet data centers | +15% to 25% for users of 50 GWh or more | Pushes PUE below 1.3; more liquid cooling content per MW |
| July 2024 | MOEA AI electricity demand outlook | 0.24 GW (2023) to 2.24 GW (2028) | Sets the ceiling used in the model’s bound check |
| September 2024 | Chief Telecom LY2 AI data center | 1,800 racks, 10-200 kW per cabinet, 20 MW | About USD 280 million of facility content at USD 14.00 million per MW |
| October 2024 | Industrial tariff decision; MOEA grid bottleneck statement | +12.5%, NT$4.29 per kWh; loads north of Taoyuan constrained | Shifts new AI halls toward Central and Southern Taiwan |
| June 2025 | AWS Asia Pacific (Taipei) Region | More than USD 5 billion planned | Anchors hyperscale share at 42% of 2025 spend |
| July 2025 | Chunghwa Telecom hyperscale plan; Foxconn-TECO alliance | At least 12 MW IT load | About USD 170 million of facility content |
| November 2025 | Taipower AI data center applications | 79 filed, 4,758 MW; 40 approved, 3,033 MW | Model completions 2026-2030 use 496 MW of AI IT load, 16% of approved MW |
| December 2025 | MOEA Energy Utilization Manual and PUE caps; NCHC Tainan center | PUE 1.3 hyperscale, 1.4 colocation; 15 MW | Adds cooling and controls content; supports Southern Taiwan growth of 22.39% |
| February 2026 | GMI Cloud AI factory | USD 500 million, 7,000 GPUs, 16 MW | About USD 224 million of facility content, 45% of the budget |
| April 2026 | MODA subsea cable incident review | 7 incidents in 2025, 42.9% from anchor dragging | Raises redundancy spend on network fabric and power |
Read together, the timeline shows why the market grows 17.15% a year rather than faster: approvals, not demand, set the pace of AI halls in Taiwan.
Which Part of Taiwan Leads AI Data Center Spend, and Which Grows Fastest?
Northern Taiwan leads Taiwan AI data center spend with USD 411.29 million, 60% of the 2025 total. Southern Taiwan is the fastest-growing region at 22.39% a year as grid headroom in Tainan and Kaohsiung draws the newest AI halls (DC Market Insights estimate).
| Region | 2025 (USD million) | Share 2025 | 2035 (USD million) | CAGR 2025-2035 |
|---|---|---|---|---|
| Northern Taiwan | 411.29 | 60% | 1,568.05 | 14.32% |
| Central Taiwan | 123.39 | 18% | 667.25 | 18.39% |
| Southern Taiwan | 137.10 | 20% | 1,034.24 | 22.39% |
| Eastern Taiwan and Offshore Islands | 13.71 | 2% | 66.73 | 17.15% |
Northern Taiwan
Taoyuan, New Taipei, Taipei and Hsinchu hold the cloud regions and most colocation AI halls, including Chief Telecom LY2 and Microsoft’s Taoyuan builds; the region’s share falls from 60% to 47% by 2035 because new loads above 5 MW wait for Taipower capacity.
Central Taiwan
Changhua County, home to Google’s campus, and Taichung lift Central Taiwan to USD 667.25 million in 2035, growing 18.39% a year.
Southern Taiwan
The NCHC Tainan center (15 MW) and Foxconn’s Kaohsiung computing center make Southern Taiwan the growth region: spend rises to USD 1.03 billion in 2035, 31% of the market.
Eastern Taiwan and Offshore Islands
Eastern Taiwan holds 2% of spend, USD 13.71 million in 2025, mostly edge AI sites and cable landing resilience projects after the 2025 Taiwan-Penghu cable outage.
Which Taiwanese Cities Lead AI Data Center Spend?
Taoyuan City leads Taiwan AI data center spend with USD 143.95 million in 2025. Kaohsiung City grows fastest at 23.29% a year, and the 12 cities and counties below hold 96% of 2025 spend (USD 658.04 million), with the rest in smaller counties.
| Rank | City or county | 2025 (USD million) | 2035 (USD million) | CAGR 2025-2035 | Region |
|---|---|---|---|---|---|
| 1 | Taoyuan City | 143.95 | 600.53 | 15.35% | Northern Taiwan |
| 2 | New Taipei City | 102.82 | 333.63 | 12.49% | Northern Taiwan |
| 3 | Taipei City | 82.26 | 233.54 | 11.00% | Northern Taiwan |
| 4 | Tainan City | 68.55 | 433.72 | 20.26% | Southern Taiwan |
| 5 | Kaohsiung City | 61.69 | 500.44 | 23.29% | Southern Taiwan |
| 6 | Changhua County | 61.69 | 300.26 | 17.15% | Central Taiwan |
| 7 | Hsinchu City and County | 54.84 | 233.54 | 15.59% | Northern Taiwan |
| 8 | Taichung City | 34.27 | 200.18 | 19.30% | Central Taiwan |
| 9 | Yunlin County | 20.56 | 133.45 | 20.56% | Central Taiwan |
| 10 | Keelung City | 13.71 | 66.73 | 17.15% | Northern Taiwan |
| 11 | Yilan County | 6.85 | 33.36 | 17.15% | Northern Taiwan |
| 12 | Miaoli County | 6.85 | 33.36 | 17.15% | Central Taiwan |
How Could the Taiwan AI Data Center Forecast for 2035 Change?
The 2035 Taiwan AI Data Center Market ranges from USD 2.38 billion to USD 4.12 billion. The base case is USD 3.34 billion, and the range depends on how many AI MW Taipower can connect (DC Market Insights estimate).
| Scenario | Assumption from 2027 | 2035 (USD million) | CAGR 2025-2035 |
|---|---|---|---|
| Low | New capacity 25% below base, AI share 5 points lower | 2,377.42 | 13.24% |
| Base | Completions 155 MW (2027) to 235 MW (2035), AI share 56% to 66% | 3,336.27 | 17.15% |
| High | New capacity 20% above base, prices 5% higher | 4,122.12 | 19.65% |
Who Supplies Taiwan AI Data Centers, and How Concentrated Is the Market?
Delta Electronics holds about 14% of 2025 Taiwan AI data center equipment and services value. The top five suppliers hold about 46%, measured on the USD 685.49 million market (DC Market Insights estimate based on product mix and disclosed Taiwanese projects).
- Delta Electronics
- Schneider Electric
- Vertiv
- TECO Electric and Machinery
- Fortune Electric
- Chung-Hsin Electric and Machinery
- Shihlin Electric
- Asia Vital Components
- Auras Technology
- Trane Technologies
- Daikin
- Foxconn (Hon Hai Precision Industry)
- Chief Telecom
- Chunghwa Telecom
- Amazon Web Services
- Microsoft
Delta Electronics reported consolidated sales of NT$57.06 billion for September 2025, according to the company, with power and cooling for AI racks among its growth lines. Taiwanese thermal makers Asia Vital Components and Auras Technology supply cold plates and CDUs, while Fortune Electric, Shihlin Electric and Chung-Hsin Electric and Machinery supply transformers and switchgear for Taipower-connected campuses.
What Changed in Taiwan’s AI Data Center Market in 2025 and 2026?
At least five Taiwan AI data center projects totalling more than 60 MW were announced or opened between May 2025 and April 2026. The efficiency rules for 5 MW sites took effect.
- In May 2025, Foxconn, NVIDIA and the Taiwan government announced an AI factory with 10,000 NVIDIA Blackwell GPUs (Source: NVIDIA).
- In June 2025, Amazon launched the AWS Asia Pacific (Taipei) Region with more than USD 5 billion of planned investment (Source: Amazon).
- In July 2025, Chunghwa Telecom announced a hyperscale data center in northern Taiwan of at least 12 MW of IT load (Source: Chunghwa Telecom).
- In November 2025, Foxconn and Visionbay.ai announced a sovereign AI supercomputing center on GB300 NVL72 systems, online in the first half of 2026 (Source: Foxconn).
- In December 2025, the NCHC Cloud Computing Center opened in Tainan with 15 MW, and the MOEA set PUE caps of 1.3 and 1.4 for sites of 5 MW or more (Source: NSTC; MOEA).
- In February 2026, GMI Cloud announced a USD 500 million, 16 MW AI factory with 7,000 GPUs (Source: GMI Cloud announcement).
Methodology: How Did DC Market Insights Build the Taiwan AI Data Center Model?
DC Market Insights built the Taiwan AI data center model bottom-up from 16 annual capacity cohorts and 15 inputs. The inputs are new IT MW completed in Taiwan (40 MW in 2020, 95 MW in 2025, 195 MW in 2030, 235 MW in 2035, aligned with the Taiwan Data Center Infrastructure Market), the AI share of new capacity (8%, 45%, 64%, 66%), AI facility content of USD 14.00 million per MW in 2025 rising 2% a year, retrofits of 12 MW in 2025 at USD 4.50 million per MW, and services of USD 0.40 million per installed AI MW a year on an installed base of 136 MW at the end of 2025 (1.5% retired a year).
Three bound checks hold the result in place. First, installed AI capacity of 435.8 MW in 2028 at a PUE of 1.3 draws 0.57 GW, 25% of the MOEA’s 2.24 GW AI electricity outlook for 2028 (ceiling). Second, 700 MW of installed AI capacity in 2030 at PUE 1.3 needs 0.91 GW, 30% of the 3,033 MW of approved Taipower applications (ceiling). Third, named AI halls of 2024-2026 (Chief Telecom LY2 20 MW, NCHC 15 MW, Chunghwa Telecom 12 MW, GMI Cloud 16 MW and about 20 MW for the 10,000-GPU AI factory) total 83 MW, 61% of the 135.75 MW modelled for those years (floor). Every split sums to the total in every year, and the CAGR is recomputed from the endpoints. Full method notes are on the DC Market Insights research methodology page.
Table of contents
- 01Introduction
- 1.1Market Definition and Scope
- 1.2Included and Excluded Elements
- 1.3How the Segments Fit Together
- 1.4Why Taiwan AI Data Center Market Estimates Differ
- 02Research Methodology
- 2.1Bottom-Up Model: AI MW × Content per MW
- 2.2Bound Checks
- 2.3Source Ledger
- 03Executive Summary
- 3.1Market Snapshot, 2025, 2026 and 2035
- 3.2Key Market Statistics
- 3.3Key Takeaways
- 04Market Dynamics
- 4.1Driver: AWS, Google and Microsoft Cloud Regions
- 4.2Driver: NCHC Tainan Center and Sovereign AI Factories
- 4.3Driver: Racks of 100 kW and More
- 4.4Trend: AI Halls Move to Kaohsiung and Tainan
- 4.5Trend: Modular Power and Cooling (Foxconn-TECO)
- 4.6Trend: Geothermal and Firm Clean Power
- 4.7Restraint: Taipower Capacity North of Taoyuan
- 4.8Restraint: Tariffs and Subsea Cable Risk
- 4.9Opportunity: Liquid-Cooling Retrofits
- 4.10Opportunity: Operations and Lifecycle Services
- 05Pricing Analysis
- 5.1Cost per AI MW, 2020-2035
- 5.2Public Price Anchors
- 06Standards and Regulation
- 6.1MOEA Energy Utilization Manual and PUE Caps
- 6.2MOEA Data Center Tariff Decisions 2024
- 6.3Grid Resilience Enhancement Construction Plan
- 6.4Subsea Cable Protection
- 07Market Segmentation by Component
- 7.1Electrical Infrastructure
- 7.2Cooling Infrastructure
- 7.3Building Shell and Fit-Out
- 7.4AI Network Fabric
- 7.5Operations Services and Software
- 08Market Segmentation by Project Type
- 8.1New AI Halls
- 8.2Retrofits of Existing Halls
- 8.3Operations and Lifecycle Services
- 09Market Segmentation by Workload
- 9.1AI Training
- 9.2AI Inference
- 10Market Segmentation by Data Center Type
- 10.1Hyperscale and Cloud Data Centers
- 10.2Colocation AI Data Centers
- 10.3Sovereign and Research AI Centers
- 10.4Enterprise and Edge AI Data Centers
- 11DC Exclusive: Taiwan AI Power and Permit Timeline
- 11.1Ten Decisions and Projects, 2024-2026
- 11.2Effect on AI Facility Spend
- 12Regional Analysis
- 12.1Northern Taiwan
- 12.2Central Taiwan
- 12.3Southern Taiwan
- 12.4Eastern Taiwan and Offshore Islands
- 13City and County Analysis
- 13.1Taoyuan City
- 13.2New Taipei City
- 13.3Taipei City
- 13.4Tainan City
- 13.5Kaohsiung City
- 13.6Changhua County
- 13.7Hsinchu City and County
- 13.8Taichung City
- 13.9Yunlin County
- 13.10Keelung City
- 13.11Yilan County
- 13.12Miaoli County
- 14Forecast Scenarios
- 14.1Low Case
- 14.2Base Case
- 14.3High Case
- 15Competitive Landscape
- 15.1Delta Electronics
- 15.2Schneider Electric
- 15.3Vertiv
- 15.4TECO Electric and Machinery
- 15.5Fortune Electric
- 15.6Chung-Hsin Electric and Machinery
- 15.7Shihlin Electric
- 15.8Asia Vital Components
- 15.9Auras Technology
- 15.10Trane Technologies
- 15.11Daikin
- 15.12Foxconn (Hon Hai Precision Industry)
- 15.13Chief Telecom
- 15.14Chunghwa Telecom
- 15.15Amazon Web Services
- 15.16Google
- 15.17Microsoft
- 16Recent Developments
- 16.1Dated Events, May 2025 to February 2026
- Fig. 1Taiwan AI Data Center Market Size, 2020-2035 (USD million)
- Table 1Report Attributes
- Table 2Scope Comparison
- Table 3Cost per AI MW, 2020-2035
- Table 4Market by Component
- Table 5Market by Project Type
- Table 6Market by Workload
- Table 7Market by Data Center Type
- Table 8Taiwan AI Power and Permit Timeline
- Table 9Market by Region
- Table 10Top 12 Cities and Counties
- Table 11Forecast Scenarios, 2035
About this report
Written by Amit Jain and reviewed by Deepti Agrawal, Senior Editor, Research. Figures are built top-down and bottom-up and reconciled before publication, with 2025 as the base year.
Read our methodologyHow we built this
- Historical period2020-2024
- Base year2025
- Forecast period2026-2035
- Sizing approachTop-down + bottom-up
Need more than the report?
Advisory on this market
Due diligence, site selection and market entry work, by the analysts who wrote this report.
See consulting servicesFrequently asked questions
USD 1.05 billion in 2026, up 53.59% from USD 685.49 million in 2025, according to DC Market Insights estimates. The market is projected to reach USD 3.34 billion by 2035, a CAGR of 17.15% from 2025, as installed AI capacity grows past 1,400 MW.
USD 685.49 million of facility spend in 2025 went into Taiwanese halls built for GPU racks of 40 kW to 200 kW: electrical systems, cooling, shell and fit-out, AI network fabric, and operations services. GPU servers are excluded.
17.15% a year from 2025 to 2035, after 73.52% a year from 2020 to 2025, because new AI IT capacity rises from 42.75 MW in 2025 to about 155 MW a year by 2035 (DC Market Insights estimate).
USD 14.00 million per MW of IT load in 2025, before GPU servers, about 44% more than a conventional Taiwanese hall at USD 9.75 million. The figure rises to USD 17.07 million per MW by 2035 (DC Market Insights estimate).
Operations Services and Software, at 34.40% a year, from USD 32.99 million in 2025 to USD 634.49 million in 2035, as the installed AI base passes 1,400 MW. AI Inference is the fastest workload at 24.32%.
Southern Taiwan, at 22.39% a year, rising from 20% to 31% of spend by 2035, because Tainan and Kaohsiung still have grid capacity while loads above 5 MW north of Taoyuan wait for Taipower.
Delta Electronics, with about 14% of 2025 equipment and services value; the top five suppliers hold about 46% (DC Market Insights estimate). Schneider Electric, Vertiv, TECO, Fortune Electric, Asia Vital Components and Auras Technology also supply AI halls.
2.24 GW of AI electricity demand by 2028, according to the MOEA, up from 0.24 GW in 2023. By November 2025, 79 AI data center applications for 4,758 MW had been filed with Taipower and 3,033 MW approved.
Sites of 5 MW or more need an approved Energy Utilization Manual and a PUE of 1.3 (hyperscale) or 1.4 (colocation) since December 2025, according to the MOEA. Data centers using 50 GWh a year pay 15% to 25% higher tariffs since 2024.
USD 1.05 billion in 2026 counts only the AI facility layer. Estimates that add GPU servers, AI server exports, GPU cloud revenue or electricity bills come out several times larger, while the previous edition counted only a narrow set of dedicated AI sites.
Electrical Infrastructure, at 33.55% of 2025 spend, or USD 229.95 million. It covers medium-voltage switchgear, transformers, UPS systems and busways sized for AI loads. Operations Services and Software is smaller today but grows fastest, at 34.40% a year.
Get this report
How do I get the full report?
Request a quote; we reply by email within one business day.
How and when will I receive the report?
By email, within 24–48 business hours of payment.
How can I pay?
Once you accept the quote, we email you a secure payment link.
Can I see a sample first?
Yes. Request a free sample and we will email it to you.
Can the report be tailored to my needs?
Yes. We can add countries, segments or data cuts. Talk to an analyst about the scope you need.
Can I get an invoice or pay against a purchase order?
Write to sales@dcmarketinsights.com and our team will help.