
Thailand Data Center Colocation Market Size, Share & Forecast to 2035
Market at a glance
The Thailand Data Center Colocation market was worth USD 305.2 million in 2025 and is forecast to reach USD 4,850.0 million by 2035, growing at a 31.86% CAGR. Bangkok Metropolitan Region accounts for 85.8% of the market.
 By Amit Jain, Senior Consultant, ICT & Emerging Technologies
 Reviewed by Deepti Agrawal
Last updated 7 Oct 2026
Base year 2025 PDF + Excel
Source: DC Market Insights analysis
Key findings
Bangkok Colocation Vacancy Fell from 24% to 16% in Six Months
Hyperscale Campuses of 100 MW Move to the EEC
Power Costs of THB 5 to 6 per kWh Squeeze Margins
Platform Tenants Need Leased Capacity at Scale
What is inside the report
- 01Introduction
- 02Research Methodology
- 03Executive Summary
- 04Market Dynamics
- 05Pricing Analysis
- 06Standards and Regulation
- 07Supply Chain and Capacity Analysis
- 08Thailand Data Center Colocation Market Size and Forecast
- 09Market by Colocation Type
- 10Market by Service
- 21chapters
- 2020-2024Historical period
- 2026-2035Forecast period
- 14Companies profiled
Regional insights
- Bangkok Metropolitan Region85.8%
- Other Central and Eastern Provinces5.5%
- Eastern Economic Corridor5%
- North, Northeast and South3.7%
Segmentation
Companies profiled
- True IDC
- STT GDC Thailand
- NTT Global Data Centers
- Telehouse Thailand (KDDI)
- GSA Data Center (Gulf, Singtel, AIS)
- Digital Edge
- Bridge Data Centres
- Equinix
- Evolution Data Centres
- Skyline Data Center and Cloud Services
- NextGen Data Center and Cloud Services
- Zenith Data Center and Cloud Services
- Vistas Technology
- B.Grimm Power
Recent developments
AWS launched its Asia Pacific (Thailand) Region with three Availability Zones and plans to invest more than USD 5 billion in Thailand (Source: Amazon press release).
the BOI approved four data center projects worth a combined THB 100 billion, including a 12 MW Telehouse facility (Source: W.Media report).
True IDC broke ground on a 250 MW AI hyperscale data center in the EEC at a cost of THB 77 billion (Source: W.Media report).
USD 880 million of green loan financing was announced for the Digital Edge and B.Grimm Power joint venture's 100 MW BKK Data Center Campus in Chonburi (Source: Milbank news release).
NTT broke ground on its Bangkok 4 campus in Chonburi, backed by a 100 MW PPA with B.Grimm Power (Source: Data Center Dynamics report).
Evolution Data Centres pre-leased the first 12 MW phase of its TH01 Bangkok facility to a tier 1 global hyperscaler (Source: Data Center Dynamics report).
Full analysis
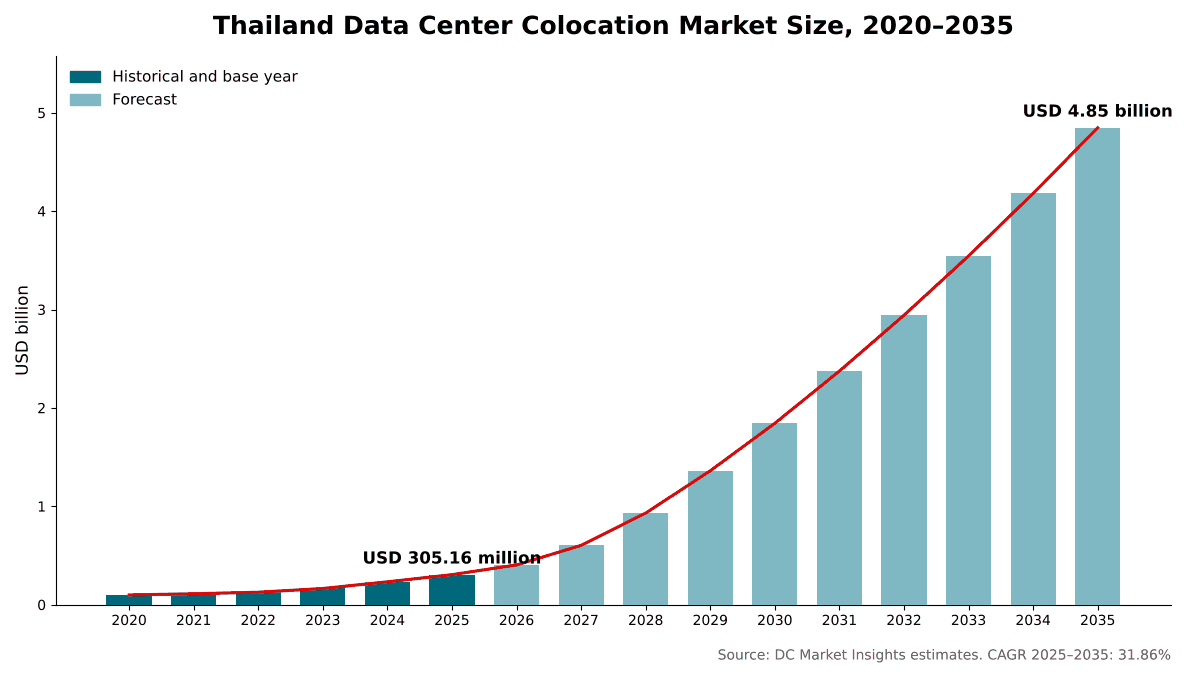
The Thailand Data Center Colocation Market covers the revenue that third-party operators earn from data centers in Thailand by leasing space, power and cooling to tenants: retail colocation (racks, cages and private suites), wholesale colocation (whole halls and build-to-suit capacity for cloud, platform and AI tenants), interconnection and managed services sold inside colocation facilities. DC Market Insights values the Thailand Data Center Colocation Market at USD 305.16 million in 2025 and forecasts USD 4.85 billion by 2035, a CAGR of 31.86%. The 2025 value is built from leased capacity: about 97 MW of occupied colocation IT load on average through 2025, priced at about USD 290 per kW per month for retail space and power in Bangkok and USD 175 per kW per month for wholesale halls, plus interconnection and managed services, gives about USD 3.15 million of revenue per occupied MW. Wholesale colocation is the fastest-growing segment at 42.68% a year because the new campuses in Thailand are pre-leased by hyperscale and platform tenants, and the Eastern Economic Corridor (EEC) is the fastest-growing region at 63.19% a year because most of that wholesale capacity is being built in Chonburi and Chachoengsao.
Executive Summary
The Thailand Data Center Colocation Market size was valued at USD 99.07 million in 2020, reached USD 305.16 million in 2025, and is anticipated to reach USD 4.85 billion by 2035, at a CAGR of 31.86% during the forecast period.
| Report attribute | Details |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Thailand Data Center Colocation Market Size 2025 | USD 305.16 Million |
| Thailand Data Center Colocation Market, CAGR | 31.86% |
| Thailand Data Center Colocation Market Size 2035 | USD 4.85 Billion |
The Thailand Data Center Colocation Market grew at 25.23% a year between 2020 and 2025, and 2025 added 31.3% over 2024 in the DC Market Insights model as Bangkok vacancy fell and new halls filled. Operational data center capacity in Bangkok reached 113 MW in 2025, with colocation vacancy of 17.6%, and 134 MW in the first half of 2026, up 19%, according to Cushman and Wakefield. Revenue growth peaks at 54.5% in 2028, when the wholesale campuses now under construction are handed over and leased, and slows to 16.0% by 2035 as the leased base becomes large.
The supply wave is already visible. Bangkok under-construction capacity rose 148% to 859 MW in the first half of 2026, putting Thailand second in Asia Pacific behind Malaysia, and the Thailand Board of Investment (BOI) received 36 data center projects in 2025 with a combined investment value exceeding USD 23.1 billion (THB 728 billion), according to the BOI’s 2025 investment release. DC Market Insights expects colocation operators to build about 52% of new national capacity from 2029, taking colocation capacity from about 147 MW at the end of 2025 to 2,607 MW at the end of 2035.
Market Scope: What Does the Thailand Data Center Colocation Market Cover?
The Thailand Data Center Colocation Market is the annual revenue of multi-tenant data center operators in Thailand, valued in current US dollars, with 2025 as the base year and forecasts to 2035. DC Market Insights sizes it at USD 305.16 million in 2025.
Included. Retail colocation (single racks, partial racks, cages and private suites, usually under 1 MW per customer), wholesale colocation (halls, floors and build-to-suit buildings leased to cloud, platform, AI and large enterprise tenants), power and cooling charges billed with the space, interconnection (cross-connects, internet exchange ports and cloud on-ramps) and managed services sold in the facility (remote hands, monitoring, security and disaster recovery).
Excluded. Capacity that hyperscalers, telecom operators, banks and government agencies build and run for themselves, public cloud and software revenue, tenant-owned IT equipment, construction spend and land.
How the segments fit together. Revenue is counted where the facility is located. The colocation type, service, end-user, enterprise-size and tier splits each re-cut the same USD 305.16 million, and the regional split allocates it across four Thai sub-markets. The capacity base is shared with the DC Market Insights Thailand Data Center Market and Thailand Data Center Infrastructure Market models, which measure spending on building and equipping the same halls.
Market Drivers: What Drives the Thailand Data Center Colocation Market?
Falling vacancy in Bangkok, cloud regions that lease capacity from local operators and data residency rules drive the Thailand Data Center Colocation Market, which DC Market Insights expects to grow 32.4% in 2026.
Bangkok Colocation Vacancy Fell from 24% to 16% in Six Months
Bangkok colocation vacancy dropped from 24% in the second half of 2024 to 16% by the end of the first half of 2025, according to Cushman and Wakefield data reported by W.Media, and stood at 17.6% for 2025 as a whole while operational capacity grew to 113 MW. Bangkok carrier-neutral colocation had reached roughly 105 MW, up from 59 MW in December 2023, according to a Mondaq legal briefing. In the DC Market Insights model, average occupied colocation capacity in Thailand rose from about 73 MW in 2024 to about 97 MW in 2025, which is why revenue grew faster than capacity.
Cloud Regions Lease Capacity from Thai Colocation Operators
Amazon Web Services (AWS) launched its Asia Pacific (Thailand) Region in January 2025 with three Availability Zones and plans to invest more than USD 5 billion in Thailand. Microsoft has partnered with CP Group, and True IDC will serve as one of the data centers for Microsoft’s Thai cloud region; True IDC’s Thailand data center is scalable up to 60 MW and capable of housing high-density compute infrastructure, according to Data Center Dynamics. Evolution Data Centres has pre-leased the first 12 MW phase of its TH01 facility in Bangkok to a tier 1 global hyperscaler on a multi-year contract. Wholesale colocation, which serves these tenants, grows 42.68% a year in the DC Market Insights model, the fastest rate of any colocation type.
Data Residency and Sector Rules Keep Workloads in Thailand
Domestic enterprises are choosing the path of least regulatory resistance under Thailand’s Personal Data Protection Act (PDPA), and Bank of Thailand (BOT) cloud-outsourcing rules apply to regulated financial institutions, according to Mondaq. Banking, financial services and insurance (BFSI) customers spend USD 45.45 million on colocation in Thailand in 2025, 14.9% of the market, by DC Market Insights estimates. Government and public sector customers add USD 28.31 million, 9.3% of the market, as state agencies move systems into colocation in the DC Market Insights model.
Market Trends: How Is Colocation in Thailand Changing?
Pre-leased hyperscale halls, AI-ready capacity and green power financing are reshaping the Thailand Data Center Colocation Market: DC Market Insights estimates the wholesale share of revenue rises from 34.0% in 2025 to 74.9% in 2035.
Hyperscale Campuses of 100 MW Move to the EEC
Digital Edge lists its BKK1 facility in Chonburi as a 100 MW AI-ready hyperscale data center ready in the fourth quarter of 2026, and USD 880 million of green loan financing was announced in May 2026 for the Digital Edge and B.Grimm Power joint venture’s 100 MW BKK Data Center Campus. Bridge Data Centres was approved for a THB 24.6 billion project supporting an IT load of 134 MW in Chonburi, and Skyline Data Center and Cloud Services for a THB 46 billion project supporting 200 MW in Chachoengsao, according to Thailand Business News. DC Market Insights places 52% of new colocation capacity in the EEC between 2026 and 2030.
AI-Ready Halls Become a Colocation Product
True IDC launched an AI hyperscale data center in Bangkok in May 2025 equipped with over 20 megawatts of power capacity, and in March 2026 broke ground on a 250 MW AI hyperscale data center in the EEC at a cost of THB 77 billion, with the first phase scheduled to be operational by 2027. Tier IV colocation revenue grows 40.91% a year in the DC Market Insights model, the fastest tier, as AI tenants ask for concurrently maintainable power and liquid cooling.
Interconnection Concentrates in Bangkok
The Bangkok Neutral Internet Exchange (BKNIX) lists 71 peers and 4.4 Tbps of total port capacity on PeeringDB, and is present in seven Thai facilities including STT Bangkok 1, NTT Bangkok 2 and Telehouse Bangkok. Interconnection revenue is USD 17.31 million in 2025, 5.7% of the market, and USD 14.89 million of it is earned in the Bangkok Metropolitan Region, by DC Market Insights estimates.
Market Challenges: What Holds the Thailand Data Center Colocation Market Back?
Power prices, new grid rules and the risk that 859 MW of construction arrives faster than tenants are the main constraints DC Market Insights sees on a market growing 31.86% a year.
Power Costs of THB 5 to 6 per kWh Squeeze Margins
Data centers are expected to pay around THB 5 to 6 (USD 0.15 to 0.18) per kWh under Thailand’s new tariff structure, according to Eco-Business, against a general rate of THB 3.95 per unit for May to August 2026 set by the Energy Regulatory Commission (ERC). Power is billed with space in most Thai colocation contracts, so DC Market Insights holds wholesale prices close to flat in real terms, from USD 175 per kW per month in 2025 to USD 169.82 in 2030.
Grid Guarantees and Commercial-Operation Deadlines
Local media have reported a proposed transmission-capacity guarantee of THB 4.5 million (USD 135,771) per MW, and developers may have to demonstrate commercial operations within five to seven years or risk losing allocated capacity, according to Eco-Business. DC Market Insights treats slower grid connection as the main downside in its low scenario, with colocation completions 25% below the base case.
Supply Could Outrun Leasing
Bangkok under-construction capacity of 859 MW in the first half of 2026 compares with 134 MW in operation, and the Bangkok pipeline reached 2,084 MW, up 99%, according to Cushman and Wakefield. National colocation occupancy dips from about 74% at the end of 2025 to about 67% in 2027 in the DC Market Insights model as new halls open part-empty, before recovering to about 83% by 2035.
Market Opportunities: Where Are the New Revenue Pools in the Thailand Data Center Colocation Market?
Wholesale halls for platform and AI tenants and colocation outside Bangkok form the largest new revenue pools: DC Market Insights estimates wholesale colocation at USD 3.63 billion and EEC colocation at USD 2.05 billion in 2035.
Platform Tenants Need Leased Capacity at Scale
The BOI approved a TikTok System (Thailand) project valued at THB 842 billion, or approximately USD 25 billion, in May 2026, the largest of the projects in that round, according to Thailand Business News. Projects of this size need wholesale halls faster than tenants can build their own, and DC Market Insights expects the IT and telecom segment, which includes cloud and platform tenants, to grow 36.74% a year to USD 3.51 billion by 2035.
Thai Energy Groups Build Colocation Platforms
GULF expects to generate THB 100 million of revenue per 1 MW from the GSA data center, its joint venture with Singtel and AIS, which was set to begin commercializing 6.4 MW, targeting 25 MW by the end of 2025 and 50 MW afterward, Kaohoon International reported in June 2025. GULF has set an ambition to reach 2,000 MW of data center capacity within three to five years, including the 38 MW GSA 02 facility slated for 2027. Other central and eastern provinces, where land and power are available near Bangkok, grow 37.65% a year to USD 410.21 million by 2035 in the DC Market Insights model.
Pricing: How Much Does Colocation Cost in Thailand?
Retail colocation in Bangkok costs about USD 290 per kW per month in 2025 and wholesale colocation about USD 175 per kW per month, by DC Market Insights estimates, with power and cooling included in both.
| Price (USD per kW per month, Bangkok) | 2025 | 2030 | 2035 |
|---|---|---|---|
| Retail colocation, space and power | 290.00 | 317.06 | 346.64 |
| Wholesale colocation, space and power | 175.00 | 169.82 | 173.24 |
| Revenue per occupied MW, all streams (USD million a year) | 3.15 | 2.40 | 2.40 |
Public price lists give a check on the retail rate. A Bangkok provider lists a 42U full rack from THB 42,000 per month, a 20U half rack from THB 24,000 and a 9U quarter rack from THB 12,000, and a second provider hosted at INET facilities lists a 10U rack at THB 20,000 per month. At a DC Market Insights exchange-rate assumption of THB 33.50 per US dollar, a full rack at THB 42,000 is about USD 1,254 per month. For wholesale and blended revenue, GULF’s expectation of THB 100 million of revenue per MW at the GSA data center equals about USD 2.99 million per MW (implicitly annual), close to the USD 3.15 million per occupied MW in the DC Market Insights model for 2025. Wholesale halls set outside Bangkok are priced 5% to 8% below Bangkok in the model, and blended revenue per MW falls from USD 3.15 million in 2025 to USD 2.40 million in 2030 because wholesale leases take a larger share of capacity.
Standards and Regulation: Which Rules Shape Colocation in Thailand?
Four sets of rules shape colocation in Thailand: BOI promotion conditions, data protection and sector rules, grid and energy regulation and design standards such as TIA-942.
BOI promotion conditions. The BOI states that conditions for data center promotion include requirements related to data center construction and service standards, the Power Usage Effectiveness (PUE), and efficient water management measures. Its top incentive tier requires a PUE not exceeding 1.3 and GPU-enabled or advanced computing capability, and ISO/IEC 27001 certification is required before a company exercises its corporate income tax (CIT) exemption, according to Mondaq.
Data protection and sector rules. The PDPA, BOT cloud-outsourcing rules for regulated financial institutions and National Cyber Security Committee (NCSC) standards for critical information infrastructure all favor hosting in Thai facilities that can show certified controls, according to Mondaq.
Grid and energy regulation. A new data center screening framework covering electricity consumption, grid stability and water management, which the regulator is reportedly preparing, is expected to take effect around the fourth quarter, according to Eco-Business in August 2026, which also reported that Thailand had previously been developing a 2,000 MW Direct PPA pilot.
Design standards. According to the Telecommunications Industry Association (TIA), TIA-942-C was published in May 2024 and covers data centers including single tenant enterprise data centers and multi-tenant data centers. Tier III facilities earn USD 240.10 million of Thai colocation revenue in 2025, 78.7% of the market, by DC Market Insights estimates.
Market Segmentation: Which Segment Leads the Thailand Data Center Colocation Market?
Retail colocation leads the Thailand Data Center Colocation Market with 66.0% of 2025 revenue, and space and power leads services with 87.4%. Wholesale colocation is the fastest-growing segment at 42.68% a year because hyperscale and platform tenants pre-lease whole halls in the new campuses, while retail demand from Thai enterprises grows 19.70% a year.
By Colocation Type: Retail Leads with 66.0%
| Colocation type | 2025 (USD million) | Share 2025 | 2035 (USD billion) | CAGR 2025-2035 |
|---|---|---|---|---|
| Retail Colocation | 201.28 | 66.0% | 1.22 | 19.70% |
| Wholesale Colocation | 103.88 | 34.0% | 3.63 | 42.68% |
Retail and wholesale colocation each used about 48 MW of leased capacity in 2025 in the DC Market Insights model, but retail earns about 1.7 times as much per kW. By 2035 wholesale tenants occupy about 1,772 MW against about 243 MW for retail, and wholesale becomes 74.9% of revenue.
By Service: Space and Power Leads with 87.4%
| Service | 2025 (USD million) | Share 2025 | 2035 (USD billion) | CAGR 2025-2035 |
|---|---|---|---|---|
| Space and Power | 266.71 | 87.4% | 4.47 | 32.58% |
| Managed and Value-Added Services | 21.14 | 6.9% | 0.21 | 25.81% |
| Interconnection | 17.31 | 5.7% | 0.16 | 25.18% |
Interconnection and managed services are mostly sold to retail customers, so they grow with retail colocation rather than with wholesale halls.
By End User: IT and Telecom Leads with 50.3%
| End user | 2025 (USD million) | Share 2025 | 2035 (USD billion) | CAGR 2025-2035 |
|---|---|---|---|---|
| IT and Telecom | 153.61 | 50.3% | 3.51 | 36.74% |
| BFSI | 45.45 | 14.9% | 0.37 | 23.49% |
| Government and Public Sector | 28.31 | 9.3% | 0.27 | 25.39% |
| Media and Entertainment | 22.27 | 7.3% | 0.22 | 25.94% |
| Healthcare | 13.12 | 4.3% | 0.13 | 25.60% |
| Others | 42.40 | 13.9% | 0.34 | 23.05% |
IT and telecom includes cloud providers, digital platforms, content networks and telecom operators. Others covers retail, manufacturing, energy, logistics and education.
By Enterprise Size: Large Enterprises Lead with 74.9%
Large enterprises, including hyperscale and platform tenants, spend USD 228.67 million on colocation in Thailand in 2025 and USD 4.43 billion by 2035, a CAGR of 34.51%. Small and medium enterprises (SMEs) spend USD 76.49 million (25.1%), rising to USD 413.34 million by 2035 at 18.38% a year, almost all of it in retail racks and cages.
By Tier Level: Tier III Leads with 78.7%
Tier III facilities earn USD 240.10 million in 2025 and USD 3.60 billion by 2035, growing 31.09% a year. Tier IV, at USD 36.88 million (12.1%), grows fastest at 40.91% a year as AI halls are designed for higher resilience, while Tier I and II rooms, at USD 28.18 million (9.2%), grow 14.53% a year.
DC Exclusive: The Bangkok vs EEC Colocation Revenue Matrix
At USD 143.13 million in 2025, retail space and power in the Bangkok Metropolitan Region is the single largest cell of the matrix and 46.9% of all Thai colocation revenue.
| 2025, USD million | Retail space and power | Wholesale space and power | Interconnection | Managed services | Total |
|---|---|---|---|---|---|
| Bangkok Metropolitan Region | 143.13 | 85.70 | 14.89 | 18.18 | 261.90 |
| Other Central and Eastern Provinces | 10.91 | 3.48 | 1.09 | 1.32 | 16.80 |
| Eastern Economic Corridor | 4.41 | 9.63 | 0.56 | 0.70 | 15.30 |
| North, Northeast and South | 7.89 | 1.56 | 0.77 | 0.94 | 11.16 |
| Total | 166.34 | 100.37 | 17.31 | 21.14 | 305.16 |
Bangkok earns 54.7% of its colocation revenue from retail space and power because its older multi-tenant buildings serve banks, enterprises and network operators rack by rack. The EEC earns 62.9% from wholesale halls because its first colocation facilities, such as NTT’s 12 MW Bangkok 3 at Amata City in Chonburi, are built for large tenants. By 2035 the EEC earns USD 2.05 billion, almost as much as Bangkok at USD 2.12 billion.
The matrix is a DC Market Insights model, not a survey of operator revenue. It is built from 70 inputs: 22 capacity cohort values (11 years of national completions and colocation shares), 4 legacy capacity values by region, 8 occupancy values, 8 retail-share values by region, 8 price curves by type and region and 20 service and regional allocation weights, checked against GULF’s revenue per MW and published rack prices. The method is explained on our research methodology page.
Regional Insights: Which Region Leads the Thailand Data Center Colocation Market?
The Bangkok Metropolitan Region leads with 85.8% of 2025 revenue. In the Thailand Data Center Colocation Market, the Eastern Economic Corridor is the fastest-growing region at 63.19% a year because most new wholesale campuses are being built in Chonburi and Chachoengsao.
Bangkok Metropolitan Region Leads with 85.8% Share
The Bangkok Metropolitan Region, including Samut Prakan, earns USD 261.90 million in 2025 and USD 2.12 billion by 2035, a CAGR of 23.28%. STT GDC’s three Bangkok facilities bring its total capacity in the district to 42 MW, NTT’s Bangkok 1 in Bang Na offers 1.6 MW, and Telehouse Bangkok offers 9.5 MVA of capacity in a 9,000 sqm carrier-neutral building. Evolution Data Centres’ TH01 in Bangkok adds 12 MW in the fourth quarter of 2026 and a second 40 MW phase in the second quarter of 2027.
Other Central and Eastern Provinces Hold 5.5% Share
Other central and eastern provinces earn USD 16.80 million in 2025 and USD 410.21 million by 2035, a CAGR of 37.65%, as operators look for land and grid connections outside the Bangkok core and the EEC estates.
Eastern Economic Corridor Holds 5.0% Share
The Eastern Economic Corridor earns USD 15.30 million in 2025 and USD 2.05 billion by 2035, growing 63.19% a year to 42.3% of the market. NTT broke ground on its Bangkok 4 campus in Chonburi in July 2026, backed by a 100 MW power purchase agreement (PPA) with B.Grimm Power and with energization expected in the second quarter of 2027, and the Digital Edge, Bridge Data Centres, Skyline and True IDC campuses follow.
North, Northeast and South Hold 3.7% Share
The North, Northeast and South earn USD 11.16 million in 2025 and USD 264.62 million by 2035, a CAGR of 37.24%, mostly from retail colocation and edge sites run by telecom operators for provincial enterprises and government agencies.
Forecast Scenarios: How Could the 2035 Forecast Change?
The Thailand Data Center Colocation Market reaches USD 4.85 billion by 2035 in the base case, with a range of USD 3.53 billion to USD 5.72 billion across the low and high scenarios.
| Scenario | Assumption from 2026 | 2035 (USD billion) | CAGR 2025-2035 |
|---|---|---|---|
| Low | Colocation completions 25% below base; wholesale prices 8% lower | 3.53 | 27.72% |
| Base | Colocation operators build 52% of new national capacity from 2029; wholesale price near USD 170 per kW per month | 4.85 | 31.86% |
| High | Colocation completions 15% above base; wholesale prices 5% higher | 5.72 | 34.05% |
The low case reflects grid guarantees and power costs that delay EEC campuses; the high case assumes hyperscale and platform tenants lease rather than build most of their new Thai capacity.
Competitive Insights: Who Leads the Thailand Data Center Colocation Market?
- True IDC
- STT GDC Thailand
- NTT Global Data Centers
- Telehouse Thailand (KDDI)
- GSA Data Center (Gulf, Singtel, AIS)
- Digital Edge
- Bridge Data Centres
- Equinix
- Evolution Data Centres
- Skyline Data Center and Cloud Services
- NextGen Data Center and Cloud Services
- Zenith Data Center and Cloud Services
- Vistas Technology
- B.Grimm Power
Operating capacity is concentrated in a few Bangkok operators, and the pipeline is led by newcomers. STT GDC (42 MW across three Bangkok facilities), True IDC (an AI data center of over 20 MW, scalable up to 60 MW at its Thailand data center), NTT (17.2 MW across Bangkok 1, 2 and 3) and Telehouse hold most of the colocation capacity in operation; DC Market Insights estimates the top three operators earned about 55% of 2025 colocation revenue, based on their published capacities and the model’s average revenue per MW. Equinix intends to invest approximately USD 500 million in Thailand in phases over the next ten years, with two IBX data centers in Bangkok providing more than 3,375 cabinets at full build-out. In the pipeline, the BOI approved a 12 MW facility by Telehouse (Thailand), a subsidiary of KDDI, for THB 7.55 billion, an 84 MW facility by NextGen Data Center and Cloud Services, an 80 MW facility by Vistas Technology and a 200 MW facility by Zenith Data Center and Cloud Services in November 2025. Bridge Data Centres entered Thailand by acquiring BKK01 in Samut Prakan, which was operational at 450 kW with a further 5 MW of IT load to be fitted out, and Phase 1 of its Chonburi facility offers power capacity of about 200 MW, according to W.Media.
Recent Developments
- In January 2025, AWS launched its Asia Pacific (Thailand) Region with three Availability Zones and plans to invest more than USD 5 billion in Thailand (Source: Amazon press release).
- In November 2025, the BOI approved four data center projects worth a combined THB 100 billion, including a 12 MW Telehouse facility (Source: W.Media report).
- In March 2026, True IDC broke ground on a 250 MW AI hyperscale data center in the EEC at a cost of THB 77 billion (Source: W.Media report).
- In May 2026, USD 880 million of green loan financing was announced for the Digital Edge and B.Grimm Power joint venture’s 100 MW BKK Data Center Campus in Chonburi (Source: Milbank news release).
- In July 2026, NTT broke ground on its Bangkok 4 campus in Chonburi, backed by a 100 MW PPA with B.Grimm Power (Source: Data Center Dynamics report).
- In September 2026, Evolution Data Centres pre-leased the first 12 MW phase of its TH01 Bangkok facility to a tier 1 global hyperscaler (Source: Data Center Dynamics report).
We follow these leases, approvals and openings as they happen in our data center industry updates.
Methodology: How We Built the Thailand Data Center Colocation Market Model
DC Market Insights built the Thailand Data Center Colocation Market bottom-up from leased capacity. Colocation capacity starts at about 112 MW at the end of 2024 (98 MW in the Bangkok Metropolitan Region) and adds 11 annual cohorts from 2025 to 2035, each a share of the national completions in the Thailand Data Center Market model (37% of 95 MW in 2025, 55% of 170 MW in 2026, falling to 52% from 2029), split across four sub-regions. Occupancy rises from 76% on the legacy base in 2024 to 88% by 2028, and new cohorts are 45% leased in their opening year, 75% in the next year and 88% in the year after. Revenue is average occupied MW multiplied by price: USD 290 per kW per month for retail space and power and USD 175 for wholesale in Bangkok in 2025, with regional discounts, plus interconnection and managed services as a share of space and power revenue. The total was split by 2 colocation types, 3 services, 6 end-user groups, 2 enterprise sizes, 3 tier levels and 4 regions, and every split sums to the market total. The result was checked top-down against Cushman and Wakefield’s 113 MW of Bangkok operational capacity and 17.6% vacancy in 2025 (the model has 116 MW in the Bangkok Metropolitan Region), against 134 MW in the first half of 2026, and against GULF’s THB 100 million of revenue per MW, which equals about USD 2.99 million per MW against USD 3.15 million in the model.
Table of contents
- 01Introduction
- 1.1Market Definition and Scope
- 1.2Research Objectives
- 1.3Currency, Units and Years Covered
- 1.4Key Stakeholders
- 02Research Methodology
- 2.1Bottom-Up Leased Capacity Model
- 2.2Top-Down Checks: Revenue per MW and Rack Prices
- 2.3Data Sources and Assumptions
- 03Executive Summary
- 3.1Market Snapshot, 2025 and 2035
- 3.2Key Findings
- 3.3Analyst Viewpoint
- 04Market Dynamics
- 4.1Drivers
- 4.2Trends
- 4.3Challenges
- 4.4Opportunities
- 05Pricing Analysis
- 5.1Retail Colocation Price per kW per Month
- 5.2Wholesale Colocation Price per kW per Month
- 5.3Revenue per Occupied MW, 2025, 2030 and 2035
- 06Standards and Regulation
- 6.1BOI Promotion Conditions
- 6.2PDPA, BOT and NCSC Rules
- 6.3Grid and Energy Regulation
- 6.4TIA-942 and Tier Design Standards
- 07Supply Chain and Capacity Analysis
- 7.1Colocation Capacity Built and Occupied, 2020-2035
- 7.2Under-Construction and Planned Capacity
- 7.3Power and Land Availability
- 08Thailand Data Center Colocation Market Size and Forecast
- 8.1Market Size, 2020-2035
- 8.2Year-on-Year Growth
- 8.3Occupied Capacity and Occupancy
- 09Market by Colocation Type
- 9.1Retail Colocation
- 9.2Wholesale Colocation
- 10Market by Service
- 10.1Space and Power
- 10.2Interconnection
- 10.3Managed and Value-Added Services
- 11Market by End User
- 11.1IT and Telecom
- 11.2BFSI
- 11.3Government and Public Sector
- 11.4Media and Entertainment
- 11.5Healthcare
- 11.6Others
- 12Market by Enterprise Size
- 12.1Large Enterprises
- 12.2Small and Medium Enterprises
- 13Market by Tier Level
- 13.1Tier III
- 13.2Tier IV
- 13.3Tier I and II
- 14DC Exclusive: Bangkok vs EEC Colocation Revenue Matrix
- 14.1Revenue Stream by Sub-Region, 2025
- 14.2What the Matrix Shows
- 15Market by Region
- 15.1Bangkok Metropolitan Region
- 15.2Eastern Economic Corridor
- 15.3Other Central and Eastern Provinces
- 15.4North, Northeast and South
- 16Regional Cross-Sections
- 16.1Colocation Type by Region, 2025
- 16.2Service by Region, 2025
- 17Forecast Scenarios
- 17.1Low Scenario
- 17.2Base Scenario
- 17.3High Scenario
- 18Competitive Landscape
- 18.1Operator Capacity in Operation
- 18.2Announced Pipeline by Sponsor
- 18.3Market Concentration Estimate
- 19Company Profiles
- 19.1True IDC
- 19.2STT GDC Thailand
- 19.3NTT Global Data Centers
- 19.4Telehouse Thailand (KDDI)
- 19.5GSA Data Center (Gulf, Singtel, AIS)
- 19.6Digital Edge
- 19.7Bridge Data Centres
- 19.8Equinix
- 19.9Evolution Data Centres
- 19.10Skyline Data Center and Cloud Services
- 19.11NextGen Data Center and Cloud Services
- 19.12Zenith Data Center and Cloud Services
- 19.13Vistas Technology
- 19.14B.Grimm Power
- 20Recent Developments
- 20.1Leases and Openings
- 20.2Approvals and Financings
- 21Analyst Recommendations
- 21.1For Colocation Operators
- 21.2For Enterprise and Hyperscale Tenants
- 21.3For Investors
- Fig. 1Thailand Data Center Colocation Market Size, 2020–2035
- Fig. 2Colocation Capacity Built and Occupied, 2020-2035
- Fig. 3Market Share by Colocation Type, 2025 and 2035
- Fig. 4Market Share by Service, 2025 and 2035
- Fig. 5Market Share by End User, 2025 and 2035
- Fig. 6Market Share by Region, 2025 and 2035
- Fig. 7Forecast Scenarios, 2035
- Table 1Report Attributes
- Table 2Colocation Price per kW per Month, 2025, 2030 and 2035
- Table 3Market by Colocation Type, 2025 and 2035
- Table 4Market by Service, 2025 and 2035
- Table 5Market by End User, 2025 and 2035
- Table 6Market by Enterprise Size, 2025 and 2035
- Table 7Market by Tier Level, 2025 and 2035
- Table 8Bangkok vs EEC Colocation Revenue Matrix, 2025
- Table 9Market by Region, 2025 and 2035
- Table 10Forecast Scenarios, 2035
- Table 11Operator Capacity in Operation and Pipeline
About this report
Written by Amit Jain and reviewed by Deepti Agrawal, Senior Editor, Research. Figures are built top-down and bottom-up and reconciled before publication, with 2025 as the base year.
Read our methodologyHow we built this
- Historical period2020-2024
- Base year2025
- Forecast period2026-2035
- Sizing approachTop-down + bottom-up
Need more than the report?
Advisory on this market
Due diligence, site selection and market entry work, by the analysts who wrote this report.
See consulting servicesFrequently asked questions
USD 305.16 million in 2025, by DC Market Insights estimates, up from USD 99.07 million in 2020. The market is forecast to reach USD 4.85 billion by 2035 as wholesale campuses in Bangkok and the Eastern Economic Corridor are leased.
31.86% a year between 2025 and 2035, by DC Market Insights estimates. Growth peaks at 54.5% in 2028, when campuses now under construction are handed over and leased, and slows to 16.0% by 2035.
134 MW of data center capacity was operational in Bangkok in the first half of 2026, up 19%, with 859 MW under construction, according to Cushman and Wakefield. Bangkok had 113 MW and 17.6% colocation vacancy in 2025.
About USD 290 per kW per month for retail space and power in Bangkok and USD 175 per kW per month for wholesale halls in 2025, by DC Market Insights estimates. A Bangkok provider lists a 42U full rack from THB 42,000 per month.
66.0% of 2025 revenue goes to retail colocation, the leading segment. Wholesale colocation is the fastest-growing segment at 42.68% a year and reaches 74.9% of revenue by 2035, by DC Market Insights estimates, as hyperscale and platform tenants pre-lease whole halls.
85.8% of 2025 revenue, USD 261.90 million, is earned in the Bangkok Metropolitan Region, the leading region. The Eastern Economic Corridor is the fastest-growing region at 63.19% a year and earns USD 2.05 billion by 2035, by DC Market Insights estimates.
About 55% of 2025 revenue went to the top three operators, by DC Market Insights estimates; STT GDC Thailand, True IDC, NTT Global Data Centers and Telehouse hold most capacity in operation. Digital Edge, Bridge Data Centres, Equinix, Evolution Data Centres and GSA Data Center are expanding.
USD 3.53 billion to USD 5.72 billion is the 2035 range across the DC Market Insights low and high scenarios. The low case has colocation completions 25% below base and 8% lower wholesale prices; the high case has 15% more completions.
Get this report
How do I get the full report?
Request a quote; we reply by email within one business day.
How and when will I receive the report?
By email, within 24–48 business hours of payment.
How can I pay?
Once you accept the quote, we email you a secure payment link.
Can I see a sample first?
Yes. Request a free sample and we will email it to you.
Can the report be tailored to my needs?
Yes. We can add countries, segments or data cuts. Talk to an analyst about the scope you need.
Can I get an invoice or pay against a purchase order?
Write to sales@dcmarketinsights.com and our team will help.