
Switzerland Data Center Storage Market Size, Share & Forecast to 2035
Market at a glance
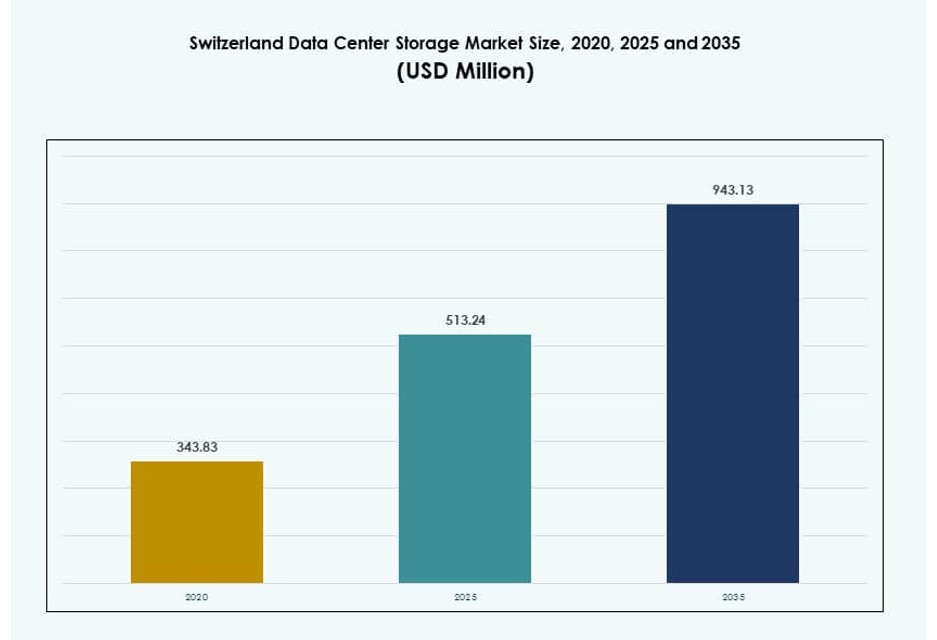
The Switzerland Data Center Storage market was worth USD 513.2 million in 2025 and is forecast to reach USD 943.1 million by 2035, growing at a 6.22% CAGR. Zurich Region accounts for over 45% of the market.
 By Amit Jain, Senior Consultant, ICT & Emerging Technologies
 Reviewed by Deepti Agrawal
Last updated 1 Jul 2026
Base year 2024 PDF + Excel
Source: DC Market Insights analysis
Key findings
Edge Storage Demand Rising from Industrial IoT and Decentralized Computing Initiatives
High Infrastructure and Operational Costs Limit Entry for Small and Medium-Sized Data Storage Players
Growth in AI, Genomics, and Research Computing Creating Demand for Scalable Storage Solutions
What is inside the report
- 01Introduction
- 02Executive Summary
- 03Market Dynamics
- 04Storage Layer / Capacity & Placement Analysis
- 05Technology Adoption & Trends
- 06Benchmarking / KPIs
- 07Cost Analysis & TCO
- 08Competitive Benchmarking
- 09Future Outlook & Innovation
- 10Switzerland Data Center Storage Market – Market Sizing & Forecast
- 18chapters
- 2020-2023Historical period
- 2025-2035Forecast period
- 10Companies profiled
Regional insights
- Zurich Region45%+
- Geneva and Lausanne Combined~35%
- Other Regions Including Basel and Bern20%
Segmentation
Companies profiled
- Swisscom
- Dell Technologies
- Hewlett Packard Enterprise (HPE)
- IBM Corporation
- NetApp
- Lenovo Group
- Cisco Systems, Inc
- Huawei Technologies Co., Ltd
- Cohesity, Inc
- Hitachi Vantara
Recent developments
Hewlett Packard Enterprise (HPE) partnered with NVIDIA to launch AI solutions tailored for enterprise data management and model deployment, enhancing hybrid cloud capabilities relevant to Switzerland's data center storage ecosystem.
at the NVIDIA GTCevent, Cohesity announced a significant expansion of its Cohesity Gaia platform to deliver one of the industry's first AI-powered search capabilities for on-premises backup data.
Vantage Data Centers invested over 370 million Swiss francs in a new hyperscale facility, Zurich 2, in Glattfelden, featuring 24 MW IT capacity with energy-efficient technologies like heat pumps and green roofs.
Full analysis
Executive summary
The Switzerland Data Center Storage Market size was valued at USD 343.83 million in 2020 to USD 513.24 million in 2025 and is anticipated to reach USD 943.13 million by 2035, at a CAGR of 6.22% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2035 |
| Switzerland Data Center Storage Market Size 2025 | USD 513.24 Million |
| Switzerland Data Center Storage Market, CAGR | 6.22% |
| Switzerland Data Center Storage Market Size 2035 | USD 943.13 Million |
Storage demand in Switzerland is growing with the shift to AI, analytics, and hybrid cloud platforms. Enterprises seek secure, high-performance systems to handle regulated workloads in BFSI, government, and healthcare sectors. Adoption of flash storage, software-defined platforms, and data lifecycle management is expanding. Vendors tailor solutions to support automation, sustainability, and compliance. Storage becomes a strategic focus for ensuring uptime, agility, and data control across mixed environments.
Zurich leads the market due to its strong financial ecosystem, data infrastructure, and hyperscale presence. Geneva and Lausanne follow as emerging hubs supporting research institutions, public agencies, and digital services. Basel and Bern contribute with pharma, government, and cross-border connectivity use cases. The distributed data center ecosystem enables regional storage growth with reliable power, regulatory alignment, and connectivity across European backbones.
Market Dynamics
Market Drivers
Rising Demand for Secure, High-Availability Storage from Regulated Sectors Like Finance and Government
The Switzerland Data Center Storage Market is expanding due to strict data protection laws and regulatory oversight. Financial institutions and government bodies need storage systems with low-latency access and fault-tolerant architectures. These users prefer in-country data storage to maintain sovereignty and compliance. It supports adoption of private and hybrid cloud models with secure storage. Vendors respond with encrypted storage arrays and zero-trust infrastructure. Hardware and software providers emphasize reliability and uptime. Multinational companies prefer Swiss data centers for neutrality and policy stability. The country’s legal framework reinforces demand for enterprise-grade storage architecture. This market supports organizations where failure or breach poses critical risks.
- For instance, Green Datacenter AG’s Metro Campus Zurich spans 46,000 m² and connects to over 700 global PoPs via direct fiber, supporting compliant in-country storage for finance workloads.
Adoption of Next-Generation Storage to Handle Advanced Analytics, AI, and Big Data Workloads
Storage infrastructure is evolving to support AI-based applications and real-time analytics. Enterprises in Switzerland implement flash arrays, NVMe, and hyperconverged systems for higher performance. Data generated from IoT sensors, video surveillance, and AI training workflows pushes storage beyond legacy formats. All-flash storage and edge-tiered storage reduce latency and improve agility. Data pipelines now demand storage that scales horizontally and vertically. The Switzerland Data Center Storage Market benefits from early AI adopters across finance, pharma, and energy. It also gains from local R&D efforts supporting industry-specific workloads. Businesses treat data as a strategic asset and invest accordingly.
- For instance, SAN solutions held 35.2% market share in 2024, driven by NVMe front-ends for performance-sensitive banking and ERP applications.
Integration of Cloud-Centric and Software-Defined Storage to Enable Flexibility and Scalability
Organizations in Switzerland shift toward software-defined storage (SDS) for improved control and cost-efficiency. SDS decouples storage from hardware, allowing dynamic scaling and automation. This shift aligns with multi-cloud and hybrid storage deployments common across Swiss enterprises. IT teams require centralized management of data workloads across public cloud, on-premises, and edge devices. Cloud-native applications also demand faster provisioning and autoscaling features. SDS platforms offer strong support for backup, archiving, and containerized environments. The Switzerland Data Center Storage Market gains traction with MSPs and telecom operators adopting storage-as-a-service. This unlocks new monetization models for providers and simplifies access for mid-size businesses.
Focus on Energy Efficiency and Sustainability Driving Investment in Modern Storage Infrastructure
Energy consumption of storage infrastructure has become a major concern in Swiss data centers. Stakeholders prefer energy-efficient drives, optimized cooling, and intelligent power management systems. Next-gen storage units are designed with sustainability and operational savings in mind. Government and corporate climate mandates push green IT adoption. Vendors offer carbon reporting and sustainability certifications with enterprise storage solutions. The Switzerland Data Center Storage Market supports businesses aiming to meet ESG targets. Colocation providers and hyperscalers invest in efficient infrastructure to reduce operating costs. It promotes long-term ROI and ensures alignment with national energy goals.
Market Trends
Edge Storage Demand Rising from Industrial IoT and Decentralized Computing Initiatives
Switzerland’s industrial sectors increasingly deploy edge computing setups for localized data processing. Edge storage becomes essential to reduce latency and manage data generated at remote sites. Sectors like manufacturing, logistics, and utilities deploy smart devices that produce real-time data. Edge-based data centers with built-in storage capabilities support autonomous decision-making. It enhances operations in regions with bandwidth constraints or regulatory needs. The Switzerland Data Center Storage Market aligns with the push for fast local response and decentralized infrastructure. Growth in private 5G, smart grids, and automation tools accelerates edge adoption. Vendors tailor rugged, compact storage for edge deployment.
Shift Toward High-Density Storage Racks to Maximize Real Estate Utilization and Operational Efficiency
Space is limited in Switzerland’s urban data centers, especially in Zurich and Geneva. Operators prioritize rack-level optimization to store more data in smaller footprints. High-density storage racks and scalable enclosures reduce the cost per TB stored. Cooling and power delivery systems are upgraded to support denser rack configurations. This trend supports hyperscale and colocation operators managing growing data volumes. The Switzerland Data Center Storage Market responds with rack-integrated storage and modular deployment models. It reduces expansion barriers while maintaining performance. Enterprises gain better TCO and resource utilization from these formats.
Demand Growing for Multi-Tenant Storage Solutions in Carrier-Neutral Facilities
Carrier-neutral facilities in Switzerland support data exchange and interconnectivity for multi-cloud use. Businesses adopt multi-tenant storage solutions to gain flexibility and cost-sharing benefits. These setups support SMEs that require secure storage without maintaining private infrastructure. Managed storage services, including storage-as-a-service and backup-as-a-service, are widely adopted. Operators optimize facilities with pooled storage, dynamic allocation, and dedicated data protection. It enables fast provisioning and regulatory compliance at scale. The Switzerland Data Center Storage Market sees increased activity from platform providers and regional ISPs. Strong network ecosystems and cross-connect capabilities fuel further demand.
Data Lifecycle Management and Compliance Driving Intelligent Storage Adoption
With growing data volumes, organizations implement lifecycle management to optimize costs and compliance. Automated tiering shifts data between performance, capacity, and archival storage based on usage patterns. Data deletion policies, GDPR readiness, and retention mandates drive intelligent storage solutions. Storage platforms now feature policy-based automation and metadata tagging. It improves governance, lowers storage costs, and enhances audit readiness. The Switzerland Data Center Storage Market integrates AI-powered storage for analytics and compliance tasks. It benefits sectors like healthcare, finance, and legal where data sensitivity is high. Vendors develop compliance-oriented features to cater to Swiss and EU standards.
Market Challenges
High Infrastructure and Operational Costs Limit Entry for Small and Medium-Sized Data Storage Players
Switzerland has some of the highest operational costs in Europe due to electricity rates, land, and labor. These cost factors limit new entrants from competing with established hyperscalers and telecom operators. SMEs find it difficult to set up and sustain independent storage infrastructure. Regulatory compliance adds further cost, especially for industries handling sensitive data. The Switzerland Data Center Storage Market requires continuous investment in hardware and management platforms. Rising utility prices also impact total cost of ownership for data center operators. It puts pressure on margins and slows expansion into underserved regions. Cost-sensitive verticals delay modernization without external support.
Skilled Workforce Shortage and Cybersecurity Threats Challenge Storage Expansion and Adoption
Switzerland faces a shortage of skilled IT professionals with expertise in cloud storage, data security, and orchestration. This talent gap restricts rapid deployment and customization of modern storage solutions. High-value industries like BFSI and pharma also face increased cyber risks targeting sensitive stored data. Storage systems must include advanced encryption, threat detection, and immutable backups. The Switzerland Data Center Storage Market requires resilient infrastructure to meet strict SLAs. Addressing threats from ransomware, insider attacks, and misconfigurations adds complexity and cost. Vendors must balance security, performance, and usability to meet buyer expectations.
Market Opportunities
Growth in AI, Genomics, and Research Computing Creating Demand for Scalable Storage Solutions
Swiss universities, biotech firms, and R&D institutes need large, scalable storage to manage massive datasets. AI training, genomic sequencing, and simulation workloads generate multi-petabyte files. The Switzerland Data Center Storage Market supports growth in scientific computing through performance-oriented storage systems. Public-private partnerships and innovation grants encourage investment in compute-linked storage.
Cloud-Native Startups and SaaS Providers Expanding Need for Flexible Storage Infrastructure
Switzerland’s growing startup ecosystem, especially in fintech and medtech, demands scalable cloud-native storage. These businesses prioritize speed, agility, and cost-efficiency in data handling. Hybrid storage with fast provisioning appeals to SaaS vendors building next-gen platforms. The Switzerland Data Center Storage Market attracts vendors offering on-demand, pay-as-you-grow models.
Market Segmentation
By Storage Type
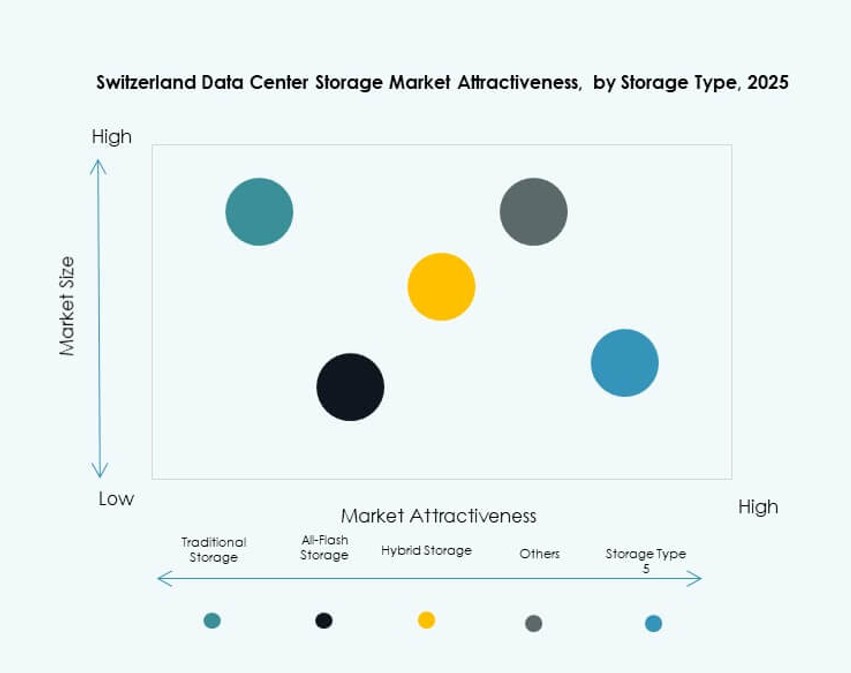
The all-flash storage segment dominates the Switzerland Data Center Storage Market due to high performance and energy efficiency. Enterprises favor flash-based arrays for real-time analytics and latency-sensitive applications. Hybrid storage also holds a significant share by balancing performance and cost. Traditional storage is gradually declining but remains relevant for archival and backup use.
By Storage Deployment
Storage Area Network (SAN) systems lead the market with high-speed connectivity and enterprise-grade availability. SAN is widely used in BFSI, telecom, and healthcare sectors for mission-critical workloads. NAS systems are gaining traction among SMEs for their ease of use and cost-effectiveness. DAS systems serve edge deployments and branch offices with simple configuration.
By Component
Hardware holds the larger share in the Switzerland Data Center Storage Market due to continuous infrastructure modernization. High-capacity drives, enclosures, and controllers represent major investments. Software is growing fast, led by SDS, backup platforms, and data management tools. Vendors bundle software with hardware for integrated performance.
By Medium
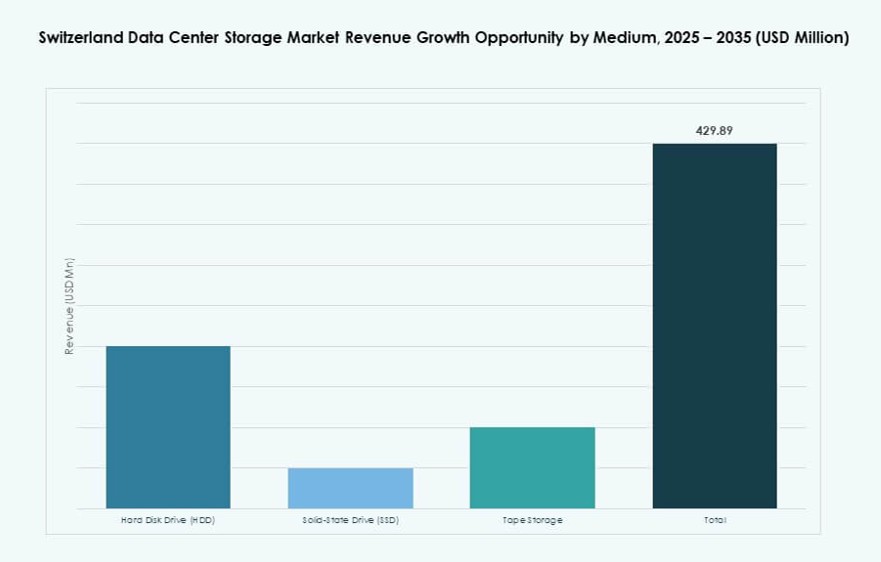
Solid-State Drives (SSD) dominate the market because of speed, reliability, and declining cost per GB. SSD adoption is high in AI, financial analytics, and hybrid cloud deployments. HDD remains in use for bulk storage and cold data needs. Tape storage is niche, used mainly in long-term archival and compliance-driven environments.
By Deployment Model
Cloud-based storage leads the deployment model segment due to flexibility, scalability, and growing SaaS adoption. Hybrid storage is rising as enterprises combine cloud agility with on-prem security. On-premises deployment still serves sectors with strict compliance requirements like government and healthcare. It supports workflows that demand full data control.
By Application
The IT and telecom segment is the largest end-user of data center storage in Switzerland. It supports digital platforms, video services, and application hosting. BFSI follows closely, driven by the need for secure, high-throughput storage. Government and healthcare also show strong demand due to regulatory compliance. Other sectors such as retail and manufacturing contribute to market growth through digital transformation.
Regional Insights
Zurich Region Holds Over 45% Market Share Due to Dense Data Center Ecosystem and Financial Sector Presence
Zurich dominates the Switzerland Data Center Storage Market with over 45% share. It hosts most of the country’s hyperscale and colocation facilities, supported by strong network infrastructure. Major banks, insurers, and cloud firms operate storage-intensive platforms in this region. Zurich benefits from real estate readiness, power availability, and connectivity to European IXPs. It attracts both global vendors and enterprise customers with stringent data security requirements.
- For instance, Vantage Data Centers announced its ZRH2 campus in April 2024, providing 24MW of critical IT capacity across 21,000 square meters to support hyperscalers and AI workloads.
Geneva and Lausanne Combined Account for Around 35% Market Share Driven by Public Sector and Academia
Geneva and Lausanne are emerging as strong secondary data center hubs. Together, they hold around 35% of the market share. Geneva supports international organizations, embassies, and NGOs with compliant storage solutions. Lausanne benefits from proximity to research institutions and startups focused on innovation. Both cities benefit from multilingual talent pools and access to renewable energy resources.
Other Regions Including Basel and Bern Contribute 20% Market Share Backed by Industry and Government Demand
Basel and Bern collectively hold around 20% share of the Switzerland Data Center Storage Market. Basel’s pharma and life sciences industry relies on secure, high-capacity data platforms. Bern hosts federal government infrastructure and agencies requiring secure digital workflows. These cities support mid-size data centers and edge nodes connected to Zurich-Geneva backbones. Their role is expected to grow as storage decentralization accelerates.
- For instance, Equinix ZH5 in the broader Zurich-area ecosystem supports N+1 power and cooling redundancy across 71,800 square feet of usable space.
Competitive Insights
- Swisscom
- Dell Technologies
- Hewlett Packard Enterprise (HPE)
- IBM Corporation
- NetApp
- Lenovo Group
- Cisco Systems, Inc.
- Huawei Technologies Co., Ltd.
- Cohesity, Inc.
- Hitachi Vantara
The Switzerland Data Center Storage Market features a mix of domestic and global technology providers. Swisscom maintains a strong local presence with integrated data and cloud services. Global players such as Dell, HPE, and IBM lead in hardware and software-defined storage offerings. NetApp and Cohesity focus on data management, backup, and hybrid cloud solutions. Cisco and Lenovo support enterprise-grade systems with robust infrastructure portfolios. Huawei and Hitachi Vantara contribute to dense storage deployment with scalable products. It remains competitive due to ongoing innovation in flash storage, disaggregated systems, and AI-integrated platforms. The market favors vendors offering energy-efficient, flexible, and compliance-ready solutions.
Recent Developments
- In March 2025, Hewlett Packard Enterprise (HPE) partnered with NVIDIA to launch AI solutions tailored for enterprise data management and model deployment, enhancing hybrid cloud capabilities relevant to Switzerland’s data center storage ecosystem.
- In March 2025, at the NVIDIA GTCevent, Cohesity announced a significant expansion of its Cohesity Gaia platform to deliver one of the industry’s first AI-powered search capabilities for on-premises backup data.
- In April 2024, Vantage Data Centers invested over 370 million Swiss francs in a new hyperscale facility, Zurich 2, in Glattfelden, featuring 24 MW IT capacity with energy-efficient technologies like heat pumps and green roofs.
Table of contents
- 01Introduction
- 1.1Market Definition & Scope
- 1.2Research Methodology
- 1.2.1Primary Research
- 1.2.2Secondary Research
- 1.2.3Data Validation & Assumptions
- 1.3Market Segmentation Framework
- 02Executive Summary
- 2.1Market Snapshot
- 2.2Key Findings
- 2.3Analyst Recommendations
- 2.4Market Outlook (2025–2035)
- 03Market Dynamics
- 3.1Market Drivers
- 3.2Market Restraints
- 3.3Market Opportunities
- 3.4Challenges & Risks
- 3.5Value Chain Analysis
- 3.6Porter’s Five Forces Analysis
- 3.7PESTEL Analysis
- 3.8Market Attractiveness Analysis
- 3.8.1Storage Type
- 3.8.2Storage Deployment
- 3.8.3Component
- 3.8.4Medium
- 3.8.5Deployment Model
- 3.8.6Application
- 04Storage Layer / Capacity & Placement Analysis
- 4.1External infrastructure & facility-level integration
- 4.2Room-level storage distribution & containment integrity
- 4.3Rack-level & node-level storage management (array, server, device)
- 4.4Multi-layer storage stack evaluation (facility → array → pool →
- 4.5Storage risk & resilience modeling (hot spots, load spikes, failure modes)
- 05Technology Adoption & Trends
- 5.1Flash & NVMe adoption trends (All-Flash Arrays, NVMe-oF, Storage-Class Memory)
- 5.2Software-defined storage & disaggregation (SDS, object storage, erasure coding)
- 5.3Telemetry, sensor & analytics integration
- 5.4Orchestration & workload-aware storage (CIOps / AIOps)
- 5.5Kubernetes CSI integration, policy-based tiering, workload-aware QoS (latency/IOPS throttling)
- 5.6Convergence of compute, network & storage (disaggregated / composable infrastructure)
- 06Benchmarking / KPIs
- 6.1Performance & incident metrics
- 6.2Hot-spot mitigation / recovery time
- 6.3Cost & efficiency metrics
- 6.4Storage effectiveness & utilization indices
- 6.5Data protection KPIs
- 07Cost Analysis & TCO
- 7.1Hardware vs software vs services costs
- 7.2CapEx vs OpEx ROI & migration models
- 7.3Predictive maintenance & lifecycle cost savings
- 7.4Data lifecycle cost modelling
- 08Competitive Benchmarking
- 8.1Vendor share by region / vertical
- 8.2Vendor vs technology mapping
- 8.3Partnerships & M&A
- 8.4Service provider plays
- 09Future Outlook & Innovation
- 9.1NVMe-over-Fabric and composable storage as mainstream
- 9.2Computational & smart storage (in-drive processing / NVDIMM)
- 9.3AI-driven storage ops & autonomous provisioning
- 9.4Sustainability & density innovations
- 9.5Next-gen media & protocols
- 9.6Data sovereignty, privacy & compliance features
- 9.7Heat / energy link back to facilities
- 10Switzerland Data Center Storage Market – Market Sizing & Forecast
- 10.1Historical Market Size (2020–2025)
- 10.2Forecast Market Size (2026–2035)
- 10.3Market Growth Rate Analysis
- 10.4Market Outlook by Region
- 11Switzerland Data Center Storage Market – By Storage Type
- 11.1Traditional Storage
- 11.2All-Flash Storage
- 11.3Hybrid Storage
- 11.4Others
- 12Switzerland Data Center Storage Market – By Storage Deployment
- 12.1Storage Area Network (SAN) System
- 12.2Network-attached storage (NAS) System
- 12.3Direct-Attached Storage (DAS) System
- 12.4Others
- 13Switzerland Data Center Storage Market – By Component
- 13.1Hardware
- 13.2Software
- 14Switzerland Data Center Storage Market – By Medium
- 14.1Hard disk drive (HDD)
- 14.2Solid-state drive (SSD)
- 14.3Tape Storage
- 15Switzerland Data Center Storage Market – By Deployment Model
- 15.1On-premises
- 15.2Cloud-based
- 15.3Hybrid
- 16Switzerland Data Center Storage Market – By Application
- 16.1IT and Telecommunications
- 16.2BFSI
- 16.3Government
- 16.4Healthcare
- 16.5Others
- 17Competitive Landscape
- 17.1Market Share Analysis
- 17.2Key Player Strategies
- 17.3Mergers, Acquisitions & Partnerships
- 17.4Product & Service Launches
- 18Company Profiles
- 18.1Swisscom
- 18.2U-Blox
- 18.3Avaloq
- 18.4ELCA
- 18.5Dell Technologies
- 18.6Cohesity, Inc.
- 18.7Hewlett Packard Enterprise Development LP (HPE)
- 18.8Cisco Systems, Inc.
- 18.9Lenovo Group
- 18.10Toshiba Corporation
- 18.11NEC Corporation
- 18.12NetApp
- 18.13IBM Corporation
- 18.14Quantum Corporation
- 18.15Nutanix, Inc.
- 18.16Huawei Technologies Co., Ltd.
- 18.17DataDirect Networks
- 18.18Hitachi Vantara
- 18.19Fujitsu Limited
- 18.20Micron Technology, Inc.
- 18.21Others
About this report
Written by Amit Jain and reviewed by Deepti Agrawal, Senior Editor, Research. Figures are built top-down and bottom-up and reconciled before publication, with 2024 as the base year.
Read our methodologyHow we built this
- Historical period2020-2023
- Base year2024
- Forecast period2025-2035
- Sizing approachTop-down + bottom-up
Need more than the report?
Advisory on this market
Due diligence, site selection and market entry work, by the analysts who wrote this report.
See consulting servicesFrequently asked questions
The Switzerland Data Center Storage Market was valued at USD 513.24 million in 2025 and is projected to reach USD 943.13 million by 2035.
The Switzerland Data Center Storage Market is expected to grow at a CAGR of 6.22% during the forecast period from 2025 to 2035.
In 2025, the all-flash storage segment held the largest share of the Switzerland Data Center Storage Market due to its high performance and energy efficiency.
Key drivers include AI-driven workloads, strict data sovereignty laws, and rising adoption of hybrid and cloud-native storage architectures across regulated industries.
Leading players include Swisscom, Dell Technologies, IBM, HPE, NetApp, Cisco, Huawei, Lenovo, and Cohesity, each offering specialized storage technologies and platforms.
Zurich commanded the largest share of the Switzerland Data Center Storage Market in 2025, driven by its financial sector, strong connectivity, and hyperscale presence.
Get this report
How do I get the full report?
Request a quote; we reply by email within one business day.
How and when will I receive the report?
By email, within 24-48 business hours of payment.
How can I pay?
Once you accept the quote, we email you a secure payment link.
Can I see a sample first?
Yes. Request a free sample and we will email it to you.
Can the report be tailored to my needs?
Yes. We can add countries, segments or data cuts. Talk to an analyst about the scope you need.
Can I get an invoice or pay against a purchase order?
Write to sales@dcmarketinsights.com and our team will help.