
KSA Data Center Infrastructure Market Size, Share & Forecast to 2035
Market at a glance
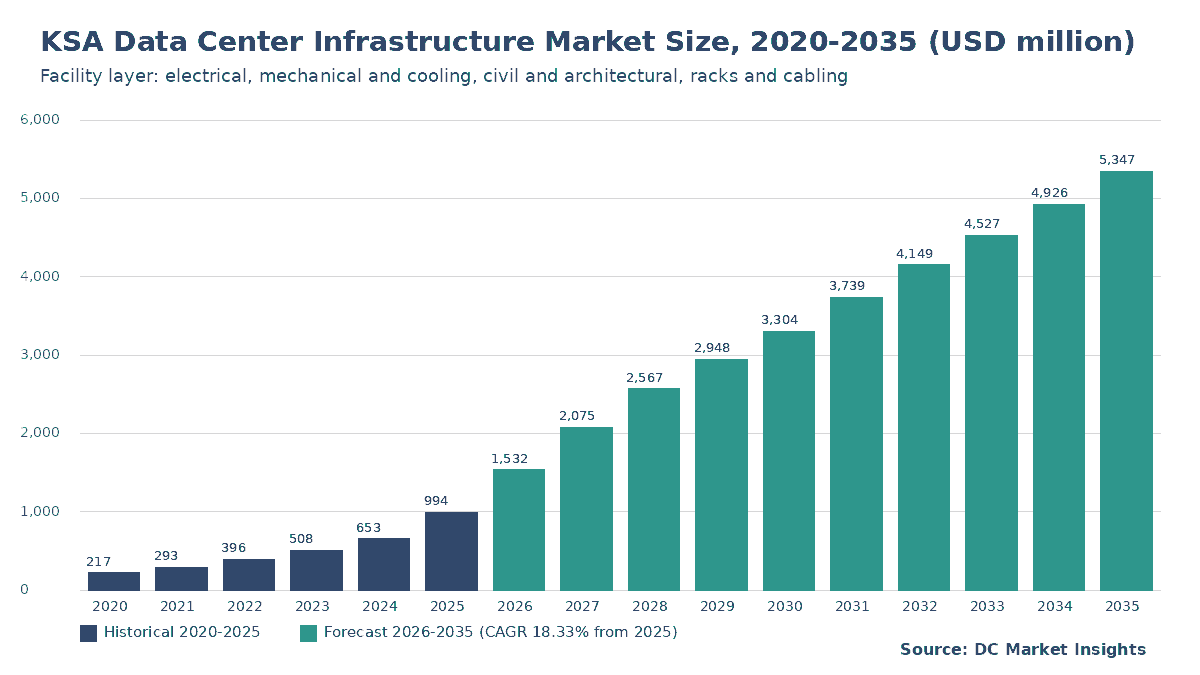
The KSA Data Center Infrastructure market was worth USD 993.6 million in 2025 and is forecast to reach USD 5,350.0 million by 2035, growing at a 18.33% CAGR.
 By Amit Jain, Senior Consultant, ICT & Emerging Technologies
 Reviewed by Deepti Agrawal
Last updated 19 Oct 2026
Base year 2025 PDF + Excel
Key findings
Grid Connections and Power Demand Peaks
What is inside the report
- 01Introduction
- 02Executive Summary
- 03Market Dynamics
- 04Pricing Analysis
- 05Standards and Regulation
- 06DC Exclusive: KSA AI and Cloud Campus Pipeline Tracker
- 07Market Segmentation
- 08Regional Insights
- 09City Hub Analysis
- 10Forecast Scenarios
- 13chapters
- 2020–2024Historical period
- 2026–2035Forecast period
- —Companies profiled
Segmentation
Full analysis
The KSA Data Center Infrastructure Market is valued at USD 1.53 billion in 2026 and is projected to reach USD 5.35 billion by 2035, up from USD 993.61 million in 2025, a CAGR of 18.33% from 2025 to 2035 (DC Market Insights estimate). Saudi Arabia’s money in this market is set by one number: the Ministry of Communications and Information Technology (MCIT) plan for more than 1,300 MW of data center capacity before 2030, against about 344 MW of IT load in service at the end of 2025 on DC Market Insights counts. Closing that gap means roughly 990 MW of new halls between 2026 and 2030, and every megawatt needs about USD 9.15 million of power trains, chillers, shells, racks and cabling before a single server arrives. The build receipt for 2025 is 95 MW of booked new capacity × USD 9.15 million per MW = USD 869.25 million, plus 310.91 MW of average installed load × USD 0.40 million of upgrades = USD 124.36 million. Upgrades and Retrofits is the fastest-growing project type at 27.14% a year as the 2018–2024 fleet is densified for AI, and NEOM and Tabuk is the fastest-growing region at 34.75% a year because the DataVolt campus at Oxagon is planned at 1.5 GW.
Key Market Statistics: How Big Is the KSA Data Center Infrastructure Market in 2026?
DC Market Insights values the KSA Data Center Infrastructure Market at USD 1.53 billion in 2026, 54.21% above the USD 993.61 million spent in 2025, as the first Amazon Web Services (AWS), Microsoft and center3 halls of the current wave are fitted out.
- Market size 2025: USD 993.61 million (DC Market Insights estimate).
- Market size 2026: USD 1.53 billion.
- Market size 2030: USD 3.30 billion.
- Market size 2035: USD 5.35 billion.
- CAGR 2025–2035: 18.33% in the base case; USD 3.81 billion (low case) to USD 6.63 billion (high case) in 2035.
- Largest infrastructure type: Electrical Infrastructure, USD 399.10 million or 40.2% of 2025 spend.
- Fastest-growing segment: AI and High Performance Computing data centers at 28.92% a year, reaching 33.0% of spend by 2035.
- Leading region: Central Region (Riyadh), 48.0% of 2025 spend; fastest region: NEOM and Tabuk at 34.75% a year.
- Largest city hub: Riyadh, USD 437.19 million in 2025.
- Market leader: Schneider Electric with about 12% of 2025 spend (DC Market Insights assessment); the top five suppliers hold about 42%.
Key Takeaways: What Should Buyers of KSA Data Center Infrastructure Know?
- Spend grows 5.4 times from USD 993.61 million in 2025 to USD 5.35 billion in 2035 because installed IT load rises from 344 MW to 2,639 MW under the MCIT 1,300 MW goal and the AI campus pipeline.
- Electrical Infrastructure keeps 40–41% of spend because every Saudi hall carries 2N medium-voltage switchgear, uninterruptible power supply (UPS) systems and diesel standby for 45 °C summers.
- Upgrades and Retrofits rise from 12.5% to 25.7% of the market because the early Riyadh and Jeddah fleet must be re-engineered for 40–130 kW AI racks.
- NEOM and Tabuk lifts its share from 3.0% to 11.0% because the DataVolt Oxagon campus moves AI capacity out of the Riyadh grid.
Executive Summary: What Is the KSA Data Center Infrastructure Market Worth from 2020 to 2035?
The KSA Data Center Infrastructure Market size was valued at USD 217.45 million in 2020, reached USD 993.61 million in 2025, and is anticipated to reach USD 5.35 billion by 2035, at a CAGR of 18.33% during the forecast period, according to DC Market Insights estimates.
| Attribute | Detail |
|---|---|
| Historical period | 2020–2024 |
| Base year | 2025 |
| Forecast period | 2026–2035 |
| Market size 2025 | USD 993.61 million |
| Market size 2026 | USD 1.53 billion |
| CAGR 2025–2035 | 18.33% |
| Market size 2035 | USD 5.35 billion |
| Segments covered | Infrastructure type, project type, data center type, tier rating |
| Regions covered | Central, Eastern, Western, NEOM and Tabuk, Southern and Northern |
KSA data center infrastructure spend grew 35.51% a year from 2020 to 2025 as new IT completions rose from 20 MW to 70 MW a year. The step to USD 1.53 billion in 2026 comes from 120 MW of completions, led by the AWS region that Amazon has tied to a more than USD 5.3 billion investment and the Microsoft Saudi Arabia East region, which Microsoft says will be available to customers in November 2026. Growth slows to about 8.5% a year by 2035 as completions settle at 300–320 MW a year and the facility cost per MW rises 3% a year.
Market Scope: What Does KSA Data Center Infrastructure Cover?
KSA Data Center Infrastructure covers the physical facility layer inside Saudi data centers, worth USD 993.61 million in 2025: the equipment and works that power, cool, house and connect IT racks.
Included
Electrical infrastructure (utility substations inside the fence, medium-voltage switchgear, transformers, UPS, batteries, busway, power distribution units and diesel generators), mechanical and cooling infrastructure (chillers, dry coolers, computer room air handlers, liquid cooling loops and coolant distribution units), civil, structural and architectural works (shell, raised floors, fire detection and suppression, physical security) and racks, cabling and physical network pathways, in new builds and in upgrades of operating halls.
Excluded
Servers, storage and network switches (the IT line of the KSA Data Center Market), land, electricity bills, Saudi Electricity Company grid reinforcement outside the site, colocation and cloud revenue, facility management contracts and data center infrastructure management software, which sits in the KSA Data Center Infrastructure Management (DCIM) Market, a separate USD 10.66 million software market on this site.
How the Segments Fit Together
The four infrastructure types sum to the market every year; the same total is split again by project type (new build vs upgrades), data center type and tier rating, and by five Saudi regions and 12 city hubs, each summing to USD 993.61 million in 2025.
Why Do KSA Data Center Infrastructure Market Estimates Differ?
DC Market Insights puts the market at USD 1.53 billion in 2026; published figures for the same name range from a few hundred million to several billion dollars because they count different layers and different capacity bases.
Broader definitions add servers, storage and network equipment, which can double or triple the value, or they add colocation rent and electricity. Narrower ones count only part of the facility layer, or count only the capacity live in 2023 and miss the 2026 hyperscale wave. The previous edition of this report valued 2025 at USD 357.87 million on a smaller capacity base; this edition rebuilds the number bottom-up from MW completions. Out of scope here are IT hardware, edge micro data centers below 100 kW, telecom towers, cloud services revenue and data center operations services.
| Element | In this report | Why |
|---|---|---|
| Power, cooling, shell, racks and cabling (new build) | Yes, USD 869.25 million in 2025 | Core facility layer |
| Upgrades and retrofits of operating halls | Yes, USD 124.36 million in 2025 | Same equipment bought for existing sites |
| Servers, storage, switches | No | IT line of the KSA Data Center Market |
| DCIM software | No | Separate DCIM report |
| Colocation rent, electricity | No | Operating revenue, not infrastructure |
Buyers inside scope include hyperscale cloud providers, colocation and wholesale developers, AI campus developers, government entities and ministries, banks, and small and mid-sized enterprises (SMEs) that build their own server rooms.
What Is Driving Saudi Data Center Infrastructure Spending?
Three Saudi-specific programmes account for most of the 990 MW of completions modelled for 2026–2030, worth USD 10.72 billion of facility capital in the KSA Data Center Infrastructure Market.
MCIT’s 1,300 MW Capacity Goal Before 2030
The MCIT data center plan targets more than 1,300 MW of national capacity before 2030 with possible investment of over USD 18 billion in data centers and renewable energy (according to MCIT, as reported in 2021). DC Market Insights models installed IT load reaching 1,284 MW in 2030, so the goal is treated as a ceiling, not a floor; meeting it requires 250 MW of completions in 2030 alone, 3.6 times the 70 MW completed in 2025.
HUMAIN’s AI Factory Programme with NVIDIA, AMD and xAI
HUMAIN, the Public Investment Fund (PIF) AI company, agreed with NVIDIA Corporation (NVIDIA) on AI factories of up to 500 MW over five years, starting with 18,000 GB300 systems (Source: NVIDIA, May 2025). An AMD, Cisco and HUMAIN joint venture plans 1 GW by 2030 with a 100 MW first phase, and xAI announced a 500 MW site with HUMAIN in November 2025. These halls run at 40–130 kW per rack, which is why AI and High Performance Computing data centers grow 28.92% a year in this model.
Hyperscale Cloud Regions Opening in 2026
AWS plans to invest more than USD 5.3 billion in a Saudi region with three availability zones (Source: Amazon, March 2024), and Microsoft says its Saudi Arabia East datacenter region in the Eastern Province opens in November 2026. Google Cloud and PIF announced a USD 10 billion AI hub that expands the existing Dammam region (Source: Google Cloud, May 2025). Together these regions explain why the Eastern Province grows 19.18% a year, faster than Riyadh’s 16.19%.
Which Trends Are Reshaping KSA Data Center Infrastructure?
Two design shifts lift mechanical and Tier IV spend in the KSA Data Center Infrastructure Market, where Tier IV designs reach USD 1.60 billion by 2035.
Liquid-Ready Halls for 45 °C Ambient Conditions
Saudi summers push dry-bulb temperatures past 45 °C, so new AI halls pair direct-to-chip liquid loops with high-temperature water that needs fewer compressor hours. DC Market Insights models mechanical and cooling infrastructure growing 18.78% a year to USD 1.35 billion in 2035, the fastest of the four infrastructure types.
Carrier-Neutral Tier III Builds under CST Rules
The Communications, Space and Technology Commission (CST) Data Centre Services Regulations, in force since 1 January 2024, require new Tier II and Tier III facilities to be carrier-neutral and set three-year registrations (according to CST). Tier III designs hold 66.0% of 2025 spend, and Tier IV rises from 24.0% to 30.0% by 2035 as AI and government buyers ask for concurrent maintainability plus fault tolerance.
Market Restraints: What Holds Back KSA Data Center Infrastructure Projects?
Grid timing and imported equipment are the two restraints that cut the low-case 2035 value to USD 3.81 billion, 28.8% below the base case.
Grid Connections and Power Demand Peaks
Saudi power demand rose about 10% year on year in the first half of 2025, and multi-hundred-MW campuses must queue for 380 kV connections and new substations (DC Market Insights estimate of typical queue times: 18–36 months). If completions from 2027 run 30% below plan, the market reaches USD 3.81 billion in 2035 instead of USD 5.35 billion.
Imported Switchgear, Chillers and Long Lead Times
DC Market Insights estimates that about 75% of facility equipment by value is imported; transformers and generators carry 50–80 week lead times in 2026. Each three-month slip moves about USD 519 million, one quarter of the USD 2.07 billion modelled for 2027, into 2028.
Where Are the Opportunities in KSA Data Center Infrastructure?
Retrofits and NEOM-area campuses together add USD 1.81 billion of annual spend between 2025 and 2035, the two largest openings for suppliers in the KSA Data Center Infrastructure Market.
Retrofitting the 2018–2024 Fleet for AI Racks
Upgrades and Retrofits grow from USD 124.36 million in 2025 to USD 1.37 billion in 2035, a 27.14% CAGR, as 344 MW of air-cooled halls in Riyadh, Jeddah and Dammam receive liquid loops, higher-rated busway and new UPS strings.
NEOM and Oxagon Campus Packages
The DataVolt and NEOM agreement covers a USD 5 billion first phase of a 1.5 GW net-zero AI factory at Oxagon, planned to operate by 2028 (according to DataVolt and NEOM, February 2025). DC Market Insights puts NEOM and Tabuk at 11.0% of national data center infrastructure spend by 2035, up from 3.0% in 2025.
How Much Does Data Center Infrastructure Cost per MW in Saudi Arabia?
DC Market Insights puts KSA data center infrastructure at USD 9.15 million per MW of new IT load in 2025, rising to USD 12.23 million per MW by 2035.
| Year | Facility layers (USD m per new MW) | Racks and cabling (USD m per new MW) | Total (USD m per new MW) | Upgrades (USD m per installed MW-year) |
|---|---|---|---|---|
| 2020 | 7.42 | 0.50 | 7.92 | 0.33 |
| 2025 | 8.60 | 0.55 | 9.15 | 0.40 |
| 2030 | 9.97 | 0.61 | 10.58 | 0.48 |
| 2035 | 11.56 | 0.67 | 12.23 | 0.55 |
Public anchors bracket these values: the DataVolt first phase is USD 5 billion for a 1.5 GW plan (about USD 3.3 million per MW of the full plan, before later phases), while HUMAIN’s programme cost of about USD 77 billion includes IT hardware. Saudi Arabia’s per-MW cost sits below the DC Market Insights global facility average of USD 10.7 million because of lower land and labour costs, partly offset by heavier cooling for desert climate.
Which Rules and Standards Shape KSA Data Center Infrastructure?
Three Saudi legal texts and two design standards decide where and how the USD 1.53 billion of 2026 KSA data center infrastructure is built.
- CST Data Centre Services Regulations (in force 1 January 2024): registration, carrier neutrality for new Tier II/III sites, three-year licences (according to CST).
- Personal Data Protection Law (PDPL): in force 14 September 2023 and fully enforceable by the Saudi Data and Artificial Intelligence Authority (SDAIA) from 14 September 2024 (according to SDAIA), keeping regulated data in Saudi halls.
- Draft Global AI Hub Law: CST consultation from 14 April to 14 May 2025 on Private, Extended and Virtual hubs that host foreign-government data under its own law (according to CST).
- Saudi Building Code (SBC) fire and electrical chapters, applied to every new shell and to fire suppression design.
- Uptime Tier and ANSI/TIA-942 (American National Standards Institute / Telecommunications Industry Association) ratings, which buyers use to specify redundancy.
DC Exclusive: KSA AI and Cloud Campus Pipeline Tracker: 10 Projects, 4.55 GW Named
This DC Market Insights tracker for KSA data center infrastructure is a modelled estimate built from 14 inputs; it counts 4.55 GW of named Saudi campus capacity against 990 MW of completions modelled for 2026–2030, so only 21.8% of the named pipeline is assumed to be finished within the decade’s first half.
| Project | Region | Named capacity / budget | Timing |
|---|---|---|---|
| HUMAIN AI factories with NVIDIA | Central / Eastern | Up to 500 MW | Five years from 2025 |
| AMD, Cisco and HUMAIN joint venture | Not stated | 1,000 MW; 100 MW first phase | By 2030 |
| xAI and HUMAIN | Not stated | 500 MW | Announced November 2025 |
| AWS and HUMAIN AI Zone | Not stated | 50 MW | 2028 |
| DataVolt Oxagon AI factory | NEOM and Tabuk | 1,500 MW; USD 5 billion first phase | 2028 |
| center3 (stc) programme | National | 300 MW by 2027; 1,000 MW by 2030 | 2027–2030 |
| AWS Saudi region | Not stated | USD 5.3 billion+ | 2026 |
| Microsoft Saudi Arabia East | Eastern | 3 availability zones | November 2026 |
| Google Cloud and PIF AI hub | Eastern (Dammam) | USD 10 billion | From 2025 |
| Alfanar four data centers | Central and Eastern | USD 1.4 billion | Announced |
The tracker shows why the base case stops short of the announcements: the named MW alone would need USD 41.6 billion of facility capital at 2025 prices, about four times the USD 10.72 billion modelled for 2026–2030.
| Region (2025, USD m) | Electrical | Mechanical and Cooling | Civil and Architectural | Racks and Cabling |
|---|---|---|---|---|
| Central Region (Riyadh) | 191.57 | 115.95 | 138.36 | 31.05 |
| Eastern Province (Dammam and Khobar) | 107.76 | 65.22 | 77.83 | 17.47 |
| Western Region (Jeddah and Makkah) | 67.85 | 41.06 | 49.00 | 11.00 |
| NEOM and Tabuk | 11.97 | 7.25 | 8.65 | 1.94 |
| Southern and Northern Regions | 19.96 | 12.08 | 14.42 | 3.24 |
Which Infrastructure Segments Carry the Value in Saudi Data Centers?
Electrical Infrastructure is the largest KSA data center infrastructure segment at USD 399.10 million (40.2%) in 2025, and AI and High Performance Computing data centers are the fastest-growing buyer type at 28.92% a year.
By Infrastructure Type: Electrical Leads with 40.2%
| Infrastructure type | 2025 (USD m) | Share 2025 | 2035 (USD m) | CAGR 2025–2035 |
|---|---|---|---|---|
| Electrical Infrastructure | 399.10 | 40.2% | 2,195.45 | 18.59% |
| Mechanical and Cooling Infrastructure | 241.56 | 24.3% | 1,350.95 | 18.78% |
| Civil Structural and Architectural | 288.26 | 29.0% | 1,445.50 | 17.50% |
| Racks Cabling and Physical Network | 64.69 | 6.5% | 355.19 | 18.57% |
By Project Type: Upgrades Grow Fastest at 27.14%
| Project type | 2025 (USD m) | Share 2025 | 2035 (USD m) | CAGR 2025–2035 |
|---|---|---|---|---|
| New Build | 869.25 | 87.5% | 3,974.14 | 16.42% |
| Upgrades and Retrofits | 124.36 | 12.5% | 1,372.95 | 27.14% |
By Data Center Type: AI and HPC Rise to 33.0%
| Data center type | 2025 (USD m) | Share 2025 | 2035 (USD m) | CAGR 2025–2035 |
|---|---|---|---|---|
| Hyperscale and Cloud | 377.57 | 38.0% | 1,764.54 | 16.67% |
| Colocation and Wholesale | 258.34 | 26.0% | 1,176.36 | 16.37% |
| AI and High Performance Computing | 139.11 | 14.0% | 1,764.54 | 28.92% |
| Enterprise and Government | 218.59 | 22.0% | 641.65 | 11.37% |
By Tier Rating: Tier III Holds 66.0%
| Tier rating | 2025 (USD m) | Share 2025 | 2035 (USD m) | CAGR 2025–2035 |
|---|---|---|---|---|
| Tier III | 655.78 | 66.0% | 3,422.14 | 17.97% |
| Tier IV | 238.47 | 24.0% | 1,604.13 | 21.00% |
| Tier I and II | 99.36 | 10.0% | 320.82 | 12.44% |
Which Saudi Region Leads Data Center Infrastructure Spending?
The Central Region (Riyadh) leads KSA data center infrastructure with USD 476.93 million, 48.0% of 2025 spend, while NEOM and Tabuk grows fastest at 34.75% a year to USD 588.18 million in 2035.
| Region | 2025 (USD m) | Share 2025 | 2035 (USD m) | CAGR 2025–2035 |
|---|---|---|---|---|
| Central Region (Riyadh) | 476.93 | 48.0% | 2,138.84 | 16.19% |
| Eastern Province (Dammam and Khobar) | 268.27 | 27.0% | 1,550.66 | 19.18% |
| Western Region (Jeddah and Makkah) | 168.91 | 17.0% | 802.06 | 16.86% |
| NEOM and Tabuk | 29.81 | 3.0% | 588.18 | 34.75% |
| Southern and Northern Regions | 49.69 | 5.0% | 267.35 | 18.33% |
Central Region (Riyadh)
Riyadh hosts government, banking and most colocation capacity, and the center3 programme of about 20 sites targets 300 MW of installed capacity by 2027 (according to center3). The region’s share falls from 48.0% to 40.0% by 2035 as power-heavy AI campuses move to the coast and the north-west.
Eastern Province (Dammam and Khobar)
The Microsoft Saudi Arabia East region and the expanded Google Cloud Dammam region make the Eastern Province the second-largest market at 27.0% of 2025 spend, growing 19.18% a year on access to Saudi Aramco-area gas power and Gulf subsea cables.
Western Region (Jeddah and Makkah)
Jeddah’s Red Sea cable landings support USD 168.91 million of 2025 spend; the region grows 16.86% a year, slower than the national 18.33%, because land and grid headroom near the city are tighter.
NEOM and Tabuk
The 1.5 GW DataVolt Oxagon plan makes NEOM and Tabuk the fastest-growing region for KSA data center infrastructure at 34.75% a year, with renewable power as the selling point.
Southern and Northern Regions
Abha, Jazan, Hail and Al Jouf hold 5.0% of spend through government disaster-recovery and edge sites, growing in line with the market at 18.33%.
Which Saudi Cities Are the Largest Data Center Infrastructure Hubs?
Riyadh is the largest KSA data center infrastructure hub at USD 437.19 million in 2025, and NEOM (Oxagon) is the fastest-growing large hub at 38.28% a year.
| Rank | City hub | Region | 2025 (USD m) | 2035 (USD m) | CAGR 2025–2035 |
|---|---|---|---|---|---|
| 1 | Riyadh | Central | 437.19 | 1,871.48 | 15.65% |
| 2 | Dammam | Eastern | 158.98 | 909.01 | 19.05% |
| 3 | Jeddah | Western | 139.11 | 641.65 | 16.52% |
| 4 | Al Khobar | Eastern | 69.55 | 374.30 | 18.33% |
| 5 | Jubail | Eastern | 39.74 | 267.35 | 21.00% |
| 6 | Al Kharj | Central | 39.74 | 267.35 | 21.00% |
| 7 | Other Cities | Various | 24.85 | 133.68 | 18.32% |
| 8 | Makkah | Western | 19.87 | 106.94 | 18.33% |
| 9 | Madinah | Western | 19.87 | 106.94 | 18.33% |
| 10 | NEOM (Oxagon) | NEOM and Tabuk | 19.87 | 507.97 | 38.28% |
| 11 | Abha | Southern | 14.90 | 80.21 | 18.33% |
| 12 | Tabuk | NEOM and Tabuk | 9.94 | 80.21 | 23.22% |
NEOM (Oxagon) overtakes Al Khobar by 2035 in the base case; Jubail and Al Kharj each grow 21.00% a year on industrial power and Riyadh overflow land.
How Could the KSA Data Center Infrastructure Forecast Change by 2035?
The 2035 value of the KSA Data Center Infrastructure Market ranges from USD 3.81 billion to USD 6.63 billion, around a base case of USD 5.35 billion, depending on how many announced MW are energised.
| Scenario | Assumption | 2035 (USD m) |
|---|---|---|
| Low | Completions 30% below base from 2027 (grid and equipment delays) | 3,809.52 |
| Base | 990 MW completed 2026–2030; 2,639 MW installed by 2035 | 5,347.09 |
| High | Completions 25% above base from 2027 (faster HUMAIN and NEOM phases) | 6,628.40 |
Who Are the Leading KSA Data Center Infrastructure Suppliers?
Schneider Electric leads KSA data center infrastructure supply with about 12% of 2025 spend and the top five suppliers hold about 42% (DC Market Insights assessment based on installed-base references and local manufacturing).
- Schneider Electric
- Vertiv
- ABB
- Eaton
- Siemens
- Huawei Digital Power
- Alfanar
- Legrand
- Johnson Controls
- Trane Technologies
- Daikin
- Carrier
- Rittal
- Caterpillar
- Cummins
Alfanar is both a Saudi switchgear maker and a developer, with a USD 1.4 billion plan for four data centers in Riyadh and Dammam (according to Alfanar). Developers such as center3, DataVolt, HUMAIN, Equinix (USD 1 billion announced at LEAP 2025) and the hyperscalers buy through general contractors and specify the equipment brands. Sibling markets for the same buildings are covered in the KSA Data Center Colocation Market and the Middle East Data Center Infrastructure Market.
What Happened Recently in KSA Data Center Infrastructure?
Six dated events since 2024 set the 2026–2030 build curve of the KSA Data Center Infrastructure Market.
- In January 2024, the CST Data Centre Services Regulations came into force (Source: CST).
- In March 2024, AWS announced a more than USD 5.3 billion investment and a Saudi region with three availability zones (Source: Amazon).
- In February 2025, DataVolt and NEOM signed a USD 5 billion first phase of a 1.5 GW AI factory at Oxagon (Source: DataVolt).
- In May 2025, HUMAIN and NVIDIA announced AI factories of up to 500 MW (Source: NVIDIA).
- In August 2025, center3 set targets of 300 MW by 2027 and 1 GW by 2030 (Source: center3).
- In August 2026, Microsoft confirmed that Saudi Arabia East opens in November 2026 (Source: Microsoft).
Methodology: How the KSA Data Center Infrastructure Model Was Built
The model multiplies 2,480 MW of Saudi IT completions from 2026 to 2035 by facility cost per MW and adds upgrades on the installed base, giving USD 993.61 million in 2025 and USD 5.35 billion in 2035.
- Capacity: installed IT load 110 MW at end-2019, 344 MW at end-2025, 1,284 MW in 2030 and 2,639 MW in 2035 (1.5% retired a year); completions 70 MW (2025), 120 MW (2026), 250 MW (2030), 320 MW (2035), booked 50/50 in the completion year and the year before.
- Unit values: facility layers USD 8.60 million per MW in 2025 (+3% a year), racks and cabling USD 0.55 million (+2%), upgrades USD 0.40 million per installed MW-year (USD 0.55 million by 2035), all DC Market Insights estimates aligned to the global facility cost of USD 10.7 million per MW.
- Splits: electrical 42%, mechanical 25% and civil 33% of new-build facility value; upgrades 45/30/15/10 across the four types.
Three bound checks: (1) 1,284 MW installed in 2030 sits just under the MCIT goal of more than 1,300 MW (ceiling); (2) USD 10.72 billion of 2026–2030 facility capital is about one-third of the USD 33 billion announced by AWS, Google Cloud and PIF, center3, DataVolt, Alfanar and Equinix, consistent with IT and land taking the rest (ceiling); (3) the Alfanar and Equinix budgets alone, USD 2.4 billion, are below the USD 3.21 billion of new-build spend modelled for 2026–2027 (floor). Parent and sibling figures are in the KSA Data Center Market and the KSA Data Center Infrastructure Management (DCIM) Market; the full approach is in our research methodology.
Table of contents
- 01Introduction
- 1.1Market Definition and Scope
- 1.2Included, Excluded and How the Segments Fit Together
- 1.3Why Estimates Differ
- 02Executive Summary
- 2.1Market Snapshot, 2025, 2026 and 2035
- 2.2Key Market Statistics
- 2.3Key Takeaways
- 03Market Dynamics
- 3.1Driver: MCIT's 1,300 MW Capacity Goal Before 2030
- 3.2Driver: HUMAIN's AI Factory Programme with NVIDIA, AMD and xAI
- 3.3Driver: Hyperscale Cloud Regions Opening in 2026
- 3.4Trend: Liquid-Ready Halls for 45 °C Ambient Conditions
- 3.5Trend: Carrier-Neutral Tier III Builds under CST Rules
- 3.6Restraint: Grid Connections and Power Demand Peaks
- 3.7Restraint: Imported Switchgear, Chillers and Long Lead Times
- 3.8Opportunity: Retrofitting the 2018–2024 Fleet for AI Racks
- 3.9Opportunity: NEOM and Oxagon Campus Packages
- 04Pricing Analysis
- 4.1Facility Cost per MW, 2020, 2025, 2030 and 2035
- 4.2Upgrade Cost per Installed MW-Year
- 05Standards and Regulation
- 5.1CST Data Centre Services Regulations
- 5.2Personal Data Protection Law
- 5.3Draft Global AI Hub Law
- 5.4Saudi Building Code and Tier Ratings
- 06DC Exclusive: KSA AI and Cloud Campus Pipeline Tracker
- 6.110 Named Projects, 4.55 GW
- 6.2Region × Infrastructure Type Matrix, 2025
- 07Market Segmentation
- 7.1By Infrastructure Type: Electrical, Mechanical and Cooling, Civil Structural and Architectural, Racks Cabling and Physical Network
- 7.2By Project Type: New Build, Upgrades and Retrofits
- 7.3By Data Center Type: Hyperscale and Cloud, Colocation and Wholesale, AI and High Performance Computing, Enterprise and Government
- 7.4By Tier Rating: Tier III, Tier IV, Tier I and II
- 08Regional Insights
- 8.1Central Region (Riyadh)
- 8.2Eastern Province (Dammam and Khobar)
- 8.3Western Region (Jeddah and Makkah)
- 8.4NEOM and Tabuk
- 8.5Southern and Northern Regions
- 09City Hub Analysis
- 9.1Riyadh, Dammam, Jeddah, Al Khobar, Jubail, Al Kharj
- 9.2Makkah, Madinah, NEOM (Oxagon), Abha, Tabuk and Other Cities
- 10Forecast Scenarios
- 10.1Low, Base and High Cases to 2035
- 11Competitive Insights
- 11.1Schneider Electric
- 11.2Vertiv
- 11.3ABB
- 11.4Eaton
- 11.5Siemens
- 11.6Huawei Digital Power
- 11.7Alfanar
- 11.8Legrand, Johnson Controls, Trane Technologies, Daikin, Carrier, Rittal, Caterpillar and Cummins
- 12Recent Developments
- 12.1Dated Events, January 2024 to August 2026
- 13Methodology
- 13.1Capacity Base and Unit Values
- 13.2Three Bound Checks
- Fig. 1KSA Data Center Infrastructure Market Size, 2020–2035 (USD million)
- Table 1Market Attributes
- Table 2Scope Comparison
- Table 3Facility Cost per MW
- Table 4Campus Pipeline Tracker
- Table 5Region × Infrastructure Type Matrix, 2025
- Table 6By Infrastructure Type
- Table 7By Project Type
- Table 8By Data Center Type
- Table 9By Tier Rating
- Table 10By Region
- Table 11Top 12 City Hubs
- Table 12Forecast Scenarios
About this report
Written by Amit Jain and reviewed by Deepti Agrawal, Senior Editor, Research. Figures are built top-down and bottom-up and reconciled before publication, with 2025 as the base year.
Read our methodologyHow we built this
- Historical period2020–2024
- Base year2025
- Forecast period2026–2035
- Sizing approachTop-down + bottom-up
Need more than the report?
Advisory on this market
Due diligence, site selection and market entry work, by the analysts who wrote this report.
See consulting servicesFrequently asked questions
USD 1.53 billion in 2026, up 54.21% from USD 993.61 million in 2025, according to DC Market Insights estimates. The market is projected to reach USD 5.35 billion by 2035, a CAGR of 18.33% from 2025.
It is the USD 993.61 million (2025) facility layer inside Saudi data centers: electrical power trains, cooling, civil and architectural works, racks and cabling, in new builds and upgrades. Servers, storage, land, electricity and DCIM software are excluded.
AI and High Performance Computing data centers grow fastest at 28.92% a year, from USD 139.11 million in 2025 to USD 1.76 billion in 2035, as HUMAIN, xAI and AMD-backed AI campuses need 40–130 kW racks.
About USD 9.15 million per MW of new IT load in 2025 (USD 8.60 million facility layers plus USD 0.55 million racks and cabling), rising to USD 12.23 million by 2035, on DC Market Insights unit values.
The Central Region (Riyadh) leads with USD 476.93 million, 48.0% of 2025 spend. NEOM and Tabuk grows fastest at 34.75% a year on the 1.5 GW DataVolt Oxagon plan.
DC Market Insights models 1,284 MW of installed IT load in 2030, up from 344 MW at end-2025, just under the MCIT goal of more than 1,300 MW before 2030.
Electrical Infrastructure is largest at USD 399.10 million, 40.2% of 2025 spend, because Saudi halls carry 2N switchgear, UPS and diesel standby. Mechanical and cooling grows fastest of the four types at 18.78% a year.
Schneider Electric leads with about 12% of 2025 spend (DC Market Insights assessment); Vertiv, ABB, Eaton and Siemens complete a top five holding about 42%, with Alfanar the main Saudi manufacturer.
USD 1.53 billion for 2026 counts only the facility layer on a bottom-up MW base. Estimates that add servers, storage, colocation rent or electricity are larger; those counting only 2023 capacity are smaller.
The 2035 value ranges from USD 3.81 billion (completions 30% lower from 2027) to USD 6.63 billion (25% higher), around a base case of USD 5.35 billion.
Get this report
How do I get the full report?
Request a quote; we reply by email within one business day.
How and when will I receive the report?
By email, within 24–48 business hours of payment.
How can I pay?
Once you accept the quote, we email you a secure payment link.
Can I see a sample first?
Yes. Request a free sample and we will email it to you.
Can the report be tailored to my needs?
Yes. We can add countries, segments or data cuts. Talk to an analyst about the scope you need.
Can I get an invoice or pay against a purchase order?
Write to sales@dcmarketinsights.com and our team will help.